Medicare Open Enrollment Explained: Your Simple 2026 Guide

Medicare Open Enrollment Explained: Your Simple 2026 Guide

Last Tuesday, a client named Margaret sat at her kitchen table surrounded by fifteen different insurance flyers, all claiming to have the best plan for 2026. She felt paralyzed by the fear that choosing the wrong one would mean losing the specialist she has seen for ten years. If your mailbox looks like Margaret’s, you aren’t alone. Having medicare open enrollment explained in plain English is the only way to escape that feeling of being buried under a mountain of jargon. We know it’s frustrating when every letter you open mentions a different 2026 premium change or benefit update.

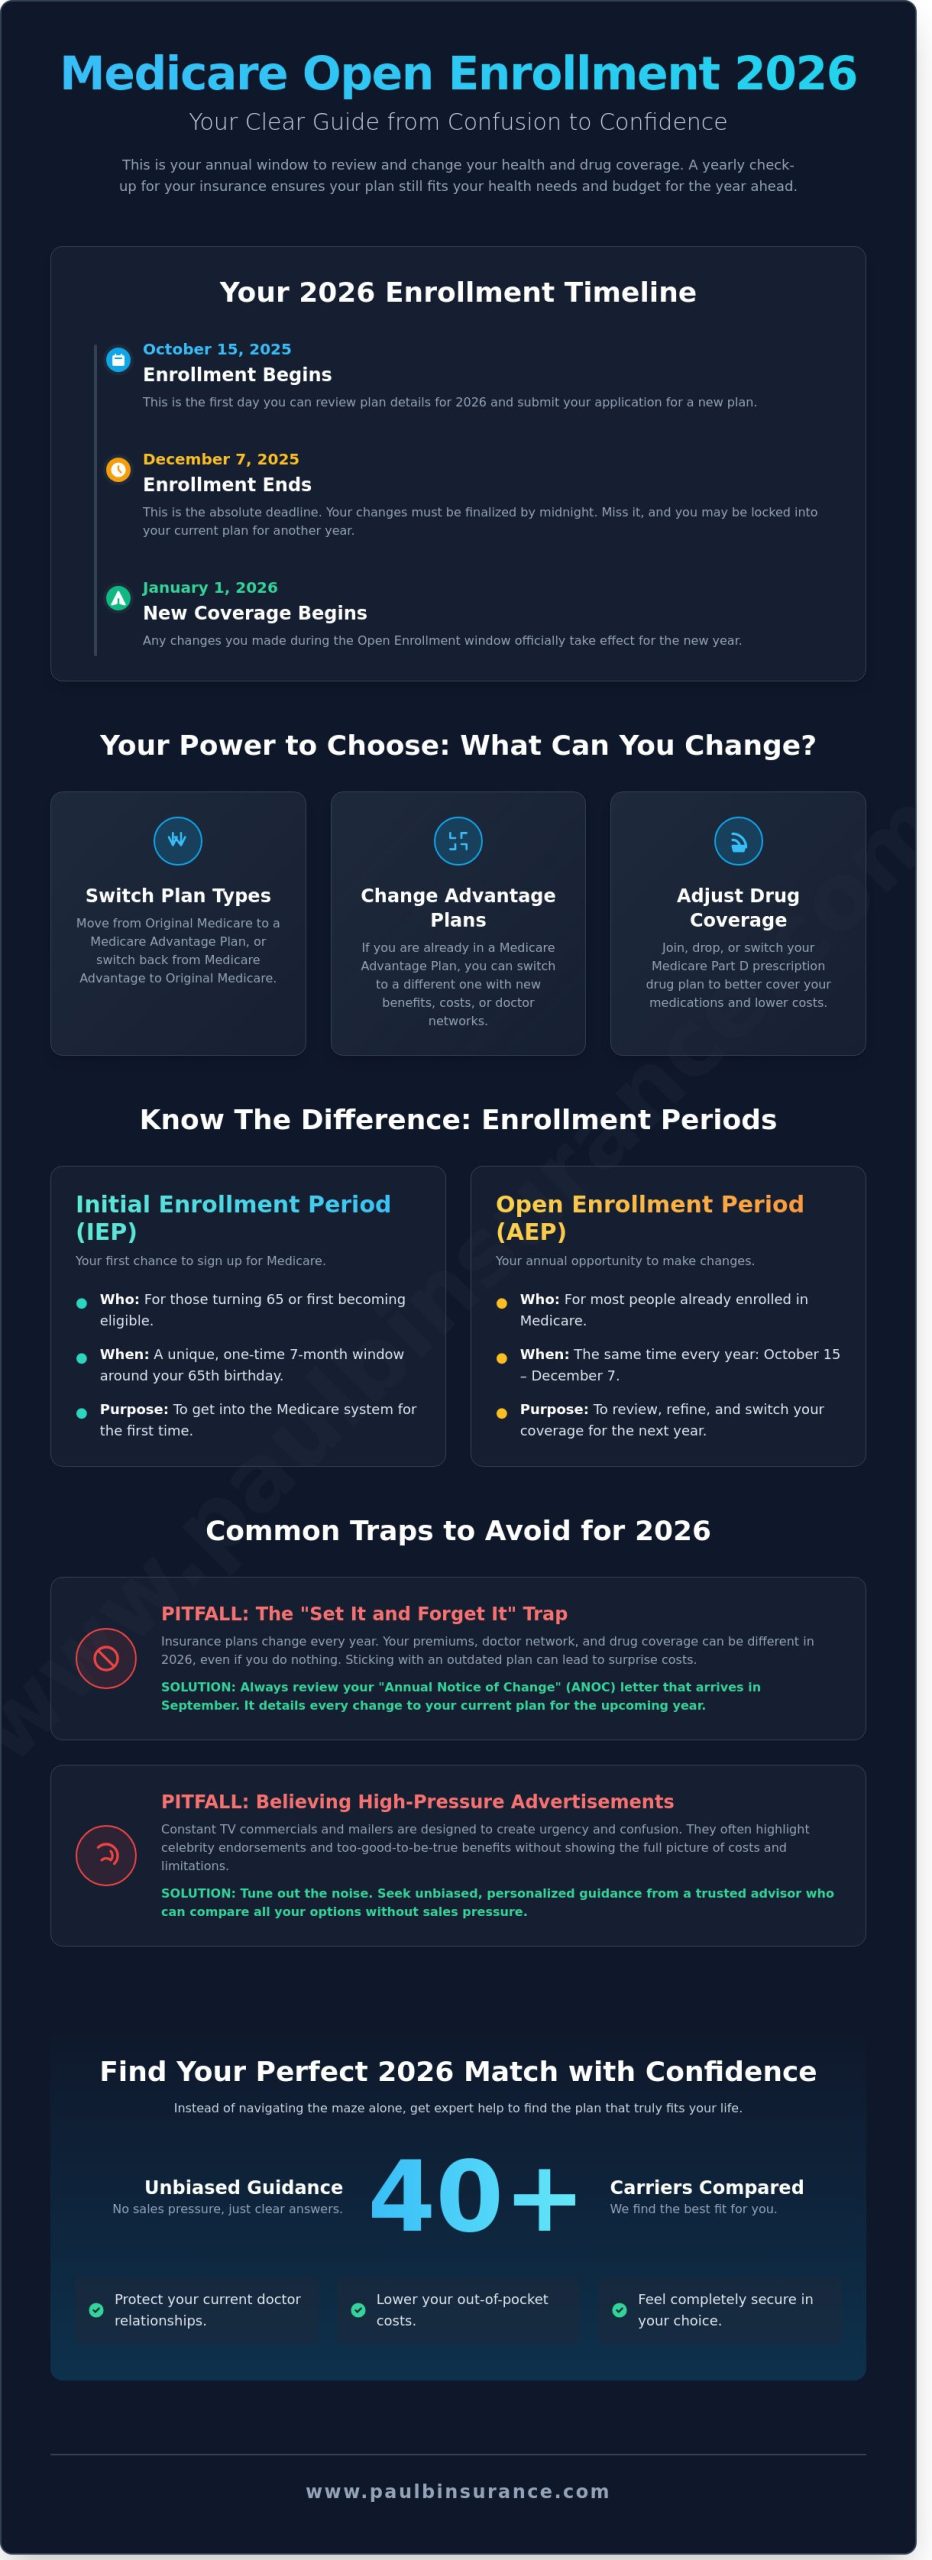
At The Modern Medicare Agency, we believe you deserve to feel steady and secure during this important window, which runs from October 15 to December 7, 2025. Our goal is to move you from a state of confusion to total confidence by simplifying the complex rules. We promise to show you exactly how to protect your current doctor relationships and lower your out-of-pocket costs without any sales pressure. This guide provides a clear timeline of the 2026 deadlines, a breakdown of what you can change right now, and a simple checklist to ensure you don’t miss a single beat.

Key Takeaways

  • Mark your calendar for the 2026 window between October 15 and December 7 to ensure you have plenty of time to review your options without feeling rushed.
  • We have medicare open enrollment explained in simple steps, showing you how to easily move between Original Medicare and Advantage plans for the upcoming year.
  • Learn to spot common pitfalls like the “set it and forget it” trap and discover how to tune out high-pressure advertisements that cause unnecessary stress.
  • See how we compare over 40 different carriers to find your perfect 2026 match, giving you the unbiased guidance you need to feel completely secure in your choice.

What is Medicare Open Enrollment? The Basics for 2026

Medicare can feel like a maze of confusing dates and complex choices. We see people every day who feel overwhelmed by the stacks of mail and constant phone calls from insurance companies. Our goal is to help you move from confusion to confidence. To get started, medicare open enrollment explained simply is this: it’s your annual window to review and change your health and drug coverage to ensure it matches your needs for the coming year.

This period, also known as the Annual Election Period (AEP), is the one time each year when most people already enrolled in Medicare can switch plans. Whether you want to move from Original Medicare to a private plan or just find a better way to cover your prescriptions, this is your chance. Understanding What is an Open Enrollment Period? is the first step toward taking control of your healthcare costs for 2026. It’s not about being sold a policy; it’s about making sure you aren’t overpaying for benefits you don’t use.

The Purpose of the Annual Enrollment Window

Why does the government allow this yearly reset? It’s because the insurance market doesn’t stand still. Every year, insurance companies adjust their premiums, change their doctor networks, and update their lists of covered medications. A plan that was perfect for you in 2025 might have much higher out-of-pocket costs in 2026. This window exists so you don’t get stuck in a plan that no longer serves your health or your budget.

For 2026, a review is more essential than ever. We’ve seen significant shifts in how drug costs are structured, including the ongoing impact of the $2,000 out-of-pocket cap on prescriptions. Even if you’re happy with your current coverage, you should check your “Annual Notice of Change” (ANOC) letter. We can help you compare these updates against other available Medicare Part D options to see if a different plan would save you money. We simplify the jargon so you know exactly how your benefits will look on January 1st.

OEP vs. Initial Enrollment: Knowing the Difference

It’s easy to get these terms mixed up, but they serve very different purposes. Your Initial Enrollment Period is a one-time window unique to you. It usually happens around your 65th birthday, starting three months before you turn 65 and ending three months after. That’s when you first sign up for Medicare. If you’re looking for a clear guide for those just starting out, we have resources specifically for first-timers.

The Medicare Open Enrollment Period is different because it happens at the same time for everyone, regardless of when they turned 65. It runs from October 15 through December 7. While Initial Enrollment is about getting into the system, OEP is about refining your choices. Think of it as an annual check-up for your insurance. We act as your advocate during this time, offering unbiased guidance to ensure you stay protected without the stress of doing it alone.

Key Dates: Your 2026 Medicare Open Enrollment Timeline

We know the calendar can feel like an enemy when you’re trying to make sense of your health coverage. The dates seem to rush at you, and the pressure to choose the right plan can feel heavy. Having the medicare open enrollment explained in a simple, step-by-step way is the best way to move from confusion to confidence. We’ve mapped out the essential dates for your 2026 coverage so you don’t have to worry about missing a thing.

  • October 15, 2025: This is the official start date. It’s the first day you can submit your 2026 plan changes. We recommend having your choices ready before this date so you can click “submit” with peace of mind.
  • December 7, 2025: This is the hard deadline. Once the clock strikes midnight, the window for the Annual Enrollment Period closes. You must have your enrollment finalized by this date.
  • January 1, 2026: This is the day your new coverage and benefits officially begin. Any changes you made during the fall will take effect as soon as the ball drops on New Year’s Day.

If you miss the December 7 deadline, you’re likely stuck with your current coverage for the rest of 2026. This can be a scary thought if your favorite doctor left the network or your prescription costs jumped up. Unless you qualify for a Special Enrollment Period due to moving or losing other coverage, you won’t be able to make changes until the following year. Following the Official Medicare Enrollment Rules ensures you stay protected and avoid these costly gaps in care.

The Pre-Enrollment Period: September and October

Your preparation actually starts before the official window opens. In late September, keep a close eye on your mailbox for the Annual Notice of Change (ANOC). We recommend starting your plan comparison in early October so you aren’t rushed. The Annual Notice of Change (ANOC) is your cheat sheet for 2026 plan updates.

The Medicare Advantage Open Enrollment Window

There’s a separate window that runs from January 1 to March 31 every year. This specific period is only for those who are already enrolled in a Medicare Advantage plan. We often call this a “safety valve” because it allows you to make one more change if you realize your new 2026 plan isn’t the right fit. If you’re feeling unsure about your current choice, you can look through our Medicare Advantage guide to see if a different path might serve you better. We’re here to make sure you never feel trapped in a plan that doesn’t work for you.

What Changes Can You Make During Open Enrollment?

We know that looking at a stack of insurance papers feels like staring at a puzzle with missing pieces. This period is your chance to put those pieces together so you can breathe easier. Having medicare open enrollment explained in simple terms helps you take control of your health care for the coming year. During this window, you have the freedom to make several specific moves to protect your health and your savings. We are here to guide you through each one of them.

You can use this time to perform the following actions:

  • Switch from Original Medicare (Part A and Part B) to a Medicare Advantage plan.
  • Move from one Medicare Advantage plan to another to take advantage of better 2026 benefits.
  • Join, drop, or switch a Medicare Part D prescription drug plan to lower your pharmacy costs.
  • Return to Original Medicare from a Medicare Advantage plan if you prefer more flexibility.

The official Medicare Open Enrollment information confirms these choices are available to most beneficiaries. Our goal is to make sure you feel confident in whatever choice you make.

Updating Your Medicare Advantage Coverage

In 2026, many plans have updated their provider networks and added new extra benefits. Your current plan might have been perfect last year, but it may no longer be the best option if your primary doctor or specialist left the network. We suggest checking our Medicare Advantage guide to see how these plans have evolved. Don’t feel stuck in a plan that doesn’t serve you anymore. We can help you compare the latest 2026 benefit packages to find a fit that feels right.

Managing Your Part D Prescription Drug Plan

Drug costs are a major concern for almost everyone we talk to. Formularies change every January. This means a drug that was covered at a low cost in 2025 might move to a more expensive tier in 2026. A massive change for 2026 is the full implementation of the $2,000 out of pocket cap on prescription drugs. This effectively replaces the old “donut hole” structure with a simpler, more protective limit. You can read our guide to Medicare Part D to understand these new 2026 rules. We want to ensure you don’t pay a penny more than necessary at the pharmacy counter.

The Role of Medicare Supplement (Medigap) Plans

It’s a common mistake to think you can jump into a Medigap plan without any questions asked during this time. Medicare Supplement plans have different rules than Advantage plans. In most states, switching to Medigap insurance usually requires medical underwriting. This means a company can look at your health history before accepting your application. If you drop your Medigap plan during the medicare open enrollment explained period without a solid backup, you might find it hard to get that coverage back. We are here to help you avoid these risky moves and keep your coverage secure.

Common Pitfalls and How to Prepare for 2026

Many seniors fall into the “Set It and Forget It” trap every autumn. Even if you loved your coverage in 2025, your plan is almost certainly different for the new year. Insurance companies adjust their terms every January 1st; they don’t stay static. You might find that while your monthly premium stayed the same, your deductible for a specific tier of medication jumped by $50 or more. When you have medicare open enrollment explained by a dedicated advocate, you can spot these hidden traps early and protect your retirement savings.

Don’t let the high-pressure TV commercials or generic mailers dictate your health care. Those loud advertisements often promise “free” benefits that might not even be available in your specific county or with your trusted doctors. We focus on your unique situation, not a generic script from a corporate call center. We want to ensure your specific medications are still covered in the 2026 formulary and that your preferred hospitals remain in-network. If they aren’t, we’ll find a plan that keeps them there.

Reading Your 2026 Annual Notice of Change (ANOC)

This document usually arrives in your mailbox by late September. “The ANOC is the most important piece of mail you will receive this year, yet most people throw it away.” We help our clients decode this document for free so they aren’t hit with a surprise bill in January. There are three critical things we look for in your ANOC:

  • Premium changes: Even a small monthly increase adds up over twelve months.
  • Copay updates: Check if your cost for a specialist visit or physical therapy has gone up.
  • Drug list shifts: Insurance companies move medications between “tiers” frequently, which can drastically change your out-of-pocket costs.

If your regular prescription moved from a Tier 2 to a Tier 4, your costs could triple overnight. You can check your current coverage against new options on our Medicare Part D page.

Evaluating Your Health Needs for the Coming Year

Has your health changed in the last 12 months? Maybe you’ve received a new diagnosis or your doctor mentioned a possible surgery for later in 2026. We look at your total out-of-pocket maximum rather than just focusing on the lowest premium. A plan with a $0 premium might actually be the most expensive choice if you have frequent specialist visits or upcoming procedures. We simplify the jargon so you know exactly how it works. You can learn more about how we compare these options in our Medicare Advantage guide.
If you’re feeling overwhelmed by the 2026 changes, schedule a call with Paul today for a simple, no-pressure consultation that moves you from confusion to confidence.

Medicare Open Enrollment Explained: Your Simple 2026 Guide

We know how heavy the weight of these choices feels. By 2026, the Medicare system has grown even more complex, and you shouldn’t have to carry that burden alone. When you work with an independent broker, you get an advocate who sits on your side of the table. A captive agent works for a single insurance company. That means their loyalty is to their employer, not to you. We’re different. We compare plans from over 40 different carriers to find the one that fits your life, not the other way around. We want to make sure you have the right fit for your specific health needs without any bias toward a single brand.

This service doesn’t cost you a single penny. We get paid by the insurance companies, so our professional guidance is provided at no cost to you. Our goal is simple. We want to take you from a state of confusion to a place of total confidence. Having medicare open enrollment explained by a pro ensures you don’t miss out on better benefits or lower premiums available this year. You deserve to have someone in your corner who isn’t rushed or pressured by sales quotas. We focus on your peace of mind above all else, ensuring you understand every detail of your coverage.

Why a Local Advisor Makes a Difference

Whether you live in New York, Florida, or California, we understand the local networks that matter to you. Medicare isn’t just a national program; it’s a local one. A doctor available in Los Angeles might not be in a network in Miami. We stay with you every month of the year, not just during the busy enrollment season. If you get a confusing bill in July or a coverage notice in October, we’re here to help you solve it. You can find more details in our Medicare guide to help you understand how these local options impact your wallet.

Ready for a Stress-Free 2026? Let Us Help

We’ve developed a simple 5-step process to audit your current coverage and ensure it still serves you well. This audit is essential because plan details change every single year. Our process includes:

  • Current Plan Review: We look at what you have now and what it will cost in 2026.
  • Doctor Verification: We confirm your specialists are still in-network for the coming year.
  • Prescription Check: We run your 2026 drug list through every available plan to find the lowest total cost.
  • Benefit Comparison: We look for extra perks like dental insurance or vision coverage.
  • Seamless Enrollment: We handle the paperwork so you don’t have to worry about mistakes.

To get started, please gather your current list of medications and the names of your primary doctors. We want to make sure your 2026 coverage is seamless and stress-free. Having medicare open enrollment explained clearly is the first step toward a worry-free year. If you’re ready to secure your health future, you can reach out to us today to start your personalized coverage audit.

Take Control of Your 2026 Healthcare Future

Navigating the 2026 season doesn’t have to be a source of stress. Now that you’ve had medicare open enrollment explained, you know that the window between October 15 and December 7 is your best chance to secure the right coverage. We’ve seen many people fall into common traps by sticking with plans that no longer serve them, but we’re here to protect you from those mistakes. Our team provides unbiased guidance from 40+ carriers to ensure you get the best fit for your specific needs.

We’re currently licensed in 34+ states and use a proven 5-step process to move you from confusion to confidence. You won’t find any high-pressure sales tactics here; we’re dedicated advocates who want to see you empowered. It’s about more than just insurance; it’s about your peace of mind and financial security. Let us handle the complex details so you can focus on what matters most in 2026. We simplify the jargon so you know exactly how your plan works before you ever sign.

Schedule a Call With Paul for a Free 2026 Coverage Audit and let’s make this your simplest enrollment yet. We’re ready to walk beside you every step of the way.

Frequently Asked Questions

Is Medicare Open Enrollment the same as the Marketplace Open Enrollment?

No, these are two completely separate events with different dates and rules. Medicare Open Enrollment runs from October 15 to December 7, 2026, and is specifically for people already enrolled in Medicare. The Health Insurance Marketplace is for individuals under age 65 who don’t have government coverage. We’ve seen many seniors get confused by the overlapping dates, but keeping them separate ensures you don’t miss your chance to update your 2026 benefits.

Can I change my Medicare Supplement (Medigap) plan during Open Enrollment?

You can apply for a new Medigap plan at any time, but doing so during the fall enrollment period doesn’t guarantee acceptance. Unlike Medicare Advantage, most states allow Medigap insurers to ask health questions and deny coverage based on pre-existing conditions. Having medicare open enrollment explained by a professional helps you understand if you’ll need to pass a health screening before making a switch for the 2026 calendar year.

What happens if I am happy with my current plan and do nothing?

Your current coverage will typically renew automatically for January 1, 2027, if you take no action. However, we strongly advise against this approach because plans change their costs and benefits every year. In 2026, 90 percent of plans have adjusted their drug lists or co-pays. Reviewing your Annual Notice of Change ensures you aren’t surprised by a sudden price hike or a dropped medication when the new year starts.

How many times can I change my plan during the Open Enrollment period?

You can submit a new choice as many times as you want between October 15 and December 7. Medicare only honors the very last application they receive before the midnight deadline on the final day. We help you compare options thoroughly so you don’t feel rushed. This flexibility allows us to make sure you have the exact coverage you need for 2026 without any lingering doubts or stress.

Will I be penalized if I switch from Medicare Advantage back to Original Medicare?

There’s no federal financial penalty for returning to Original Medicare, but you might face challenges getting a Supplement plan. If you’ve been on an Advantage plan for more than 12 months, insurers in 46 states can charge more or deny you a Medigap policy. We guide you through these rules to protect you from losing the comprehensive coverage you expect. Having medicare open enrollment explained clearly means you won’t make a move that leaves you vulnerable.

Does Open Enrollment apply to me if I just started Medicare last month?

Yes, this period applies to you even if your coverage began as recently as September or October 2026. You can use this time to change your Medicare Advantage or Part D prescription plan for the upcoming year. It’s an excellent opportunity to fix any initial choices that don’t feel right. We’ll look at your current doctors and prescriptions to see if a different 2026 plan offers better value or more peace of mind.

How do I know if my medications are still covered for 2026?

You should check the 2026 formulary, which is the official list of covered drugs for your specific plan. Plans often move medications to different tiers, which changes your out-of-pocket cost. Since the $2,000 cap on prescription costs is now standard practice, many companies have updated their coverage rules. We can run a personalized search for you to confirm every single one of your medications is still on the list for next year.

Can a Medicare broker charge me for their help during Open Enrollment?

No, we never charge you a fee for our services or guidance. Our help is completely free to you because we’re compensated by the insurance companies. This allows us to act as your personal advocate without adding any financial burden to your retirement. You get expert, unbiased advice and a simplified process at no cost. We’re here to help you move from confusion to confidence throughout the entire 2026 enrollment season.
Paul Barrett

Article by

Paul Barrett

Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.

He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.

📞 631-358-5793 | paulbinsurance.com
What Is Medicare Part B and What Does It Actually Cover?

The complete guide to Medicare’s medical insurance — every service it covers, exactly what it costs in 2026, how it works with group insurance and VA benefits, and the excess charges most people have never heard of until they get a surprise bill.

The Short Answer

Medicare Part B is medical insurance — it covers doctor visits, outpatient care, preventive services, durable medical equipment, and more. Unlike Part A, Part B is not premium-free for anyone: everyone pays a monthly premium (202.90in2026formostpeople),anannualdeductible(283), and 20% coinsurance on most covered services, with no yearly cap on that 20% under Original Medicare alone. Whether you need to enroll at 65, and whether delaying is safe, depends heavily on your employment status and your employer’s size — getting this wrong is one of the most consequential and permanent mistakes in all of Medicare.

Key Takeaways

  • Part B is never premium-free — everyone pays a monthly premium, and higher earners pay significantly more through IRMAA.
  • The 20% coinsurance under Original Medicare alone has no yearly cap — this is the single biggest financial risk in Medicare, and it’s the reason Medigap and Medicare Advantage exist.
  • Whether you can safely delay Part B without a penalty depends on your employer’s size: 20+ employees generally allows delay; fewer than 20 generally does not.
  • Missing your enrollment window triggers a permanent 10% penalty for every 12-month period you went without coverage.
  • Veterans can and generally should enroll in Part B even with VA benefits, since Medicare and VA coverage don’t coordinate — each only pays for care received within its own system.
  • “Excess charges” from non-participating providers can add up to 15% on top of what Medicare approves, and only some Medigap plans protect you from them.

What Part B Actually Covers

While Part A handles hospital room and board, Part B is the half of Original Medicare that covers medical care and most services delivered outside a hospital admission — doctor visits, outpatient procedures, and ongoing medical needs.

What’s covered

  • Doctor visits — primary care and specialists
  • Outpatient surgeries and procedures
  • Diagnostic lab work, X-rays, and MRIs
  • Emergency room visits
  • Ambulance services
  • Outpatient mental health care
  • Physical, occupational, and speech therapy
  • Chemotherapy and radiation received in an outpatient clinic
  • Durable Medical Equipment (DME) — wheelchairs, oxygen equipment, blood sugar monitors, walkers, and similar equipment
  • Ambulatory surgical center services

Preventive services: the part Medicare gets genuinely right

Most preventive services are covered at 100%, with no deductible and no copay, as long as your provider accepts Medicare assignment. This includes:

  • Your one-time “Welcome to Medicare” wellness visit, available within your first 12 months on Part B
  • Annual wellness visits after that
  • Flu shots and most other recommended vaccines
  • Mammograms
  • Colonoscopies and other cancer screenings
  • Diabetes and cardiovascular screenings
  • Many other screenings recommended by the U.S. Preventive Services Task Force

Paul’s Honest Take: This is one of the most underused parts of Medicare, full stop. I’ve had clients who paid for a private physical every year out of habit and never realized their annual wellness visit through Medicare was completely free. If you haven’t used your Welcome to Medicare visit or your annual wellness visit, that’s real value sitting on the table.

What’s NOT covered

  • Routine dental care — cleanings, fillings, dentures, extractions
  • Routine vision exams and eyeglasses
  • Hearing aids (though diagnostic hearing tests ordered by a doctor may be covered)
  • Long-term custodial nursing home care — help with daily living activities, as opposed to short-term skilled or medical care
  • Routine prescription drugs you pick up at a retail pharmacy — that’s Part D’s job, not Part B’s
  • Cosmetic surgery, unless medically necessary (such as reconstruction after an accident or mastectomy)
  • Most care received outside the United States, with very limited exceptions
  • Routine foot care, such as nail trimming, in the absence of a qualifying medical condition
  • Acupuncture, except for a narrow, specific chronic low back pain benefit
  • Concierge medicine fees and membership-style charges some practices add on top of standard care
  • Long-term care insurance-style services, including most home-based personal care that isn’t tied to a skilled medical need

Paul’s Honest Take: The dental and vision exclusions are the ones that surprise people most, especially since they’re such routine parts of healthcare for most adults. This is exactly why so many Medicare Advantage plans build dental, vision, and hearing benefits into their coverage — Original Medicare was simply never designed to include them, and that gap doesn’t go away on its own.

What Part B Costs in 2026

Part B has three separate cost components, and understanding all three matters:

Cost Component

2026 Amount

Standard monthly premium

$202.90

Annual deductible

$283

Coinsurance on most covered services

20%

The premium is deducted automatically from your Social Security check if you’re already collecting benefits. If you’re not yet collecting Social Security, you’ll receive a bill, typically every three months.

The deductible works differently than Part A’s — it’s a straightforward annual figure. You pay the first $283 of Medicare-approved outpatient costs each calendar year, and then Medicare’s cost-sharing kicks in.

The coinsurance is where the real risk lives. After your deductible is met, Medicare pays 80% of the Medicare-approved amount for most covered services, and you’re responsible for the remaining 20%. There is no yearly cap on this 20% under Original Medicare alone. If you have a $100,000 course of cancer treatment, your 20% share is $20,000 — unless you have a Medigap policy or Medicare Advantage plan absorbing that cost.

Paul’s Honest Take: I put this in bold because it’s genuinely the single most important number in this entire guide. That uncapped 20% is the whole reason Medigap and Medicare Advantage exist as products in the first place. Original Medicare by itself was never designed to protect you from a truly expensive year — it was designed to cover 80% of it and leave the rest to you.

IRMAA: What Higher Earners Actually Pay

If your income is above certain thresholds, you’ll pay more for Part B through the Income-Related Monthly Adjustment Amount (IRMAA) — based on your tax return from two years prior. For 2026, that means your 2024 income determines your premium tier.

2024 Income (Individual)

2024 Income (Married, Joint)

Total Part B / Month

$109,000 or less

$218,000 or less

$202.90

$109,001 – $137,000

$218,001 – $274,000

$284.10

$137,001 – $171,000

$274,001 – $342,000

$405.80

$171,001 – $205,000

$342,001 – $410,000

$527.50

$205,001 – $499,999

$410,001 – $749,999

$649.20

$500,000 and above

$750,000 and above

$689.90

At the top tier, you’re paying more than three times the standard premium. If your income has recently dropped — retirement, the loss of a spouse, or certain other life-changing events — you can appeal your IRMAA determination using Form SSA-44.

Do You Have to Enroll? And What Happens If You Don’t?

Technically, Part B is optional — Medicare won’t force you into it. But opting out without a valid alternative is genuinely risky, because of how the penalty structure works.

If you don’t sign up during your Initial Enrollment Period (the 7-month window around your 65th birthday) and you don’t have qualifying employer coverage, you’ll face a permanent 10% penalty added to your premium for every full 12-month period you went without Part B. That penalty doesn’t expire — you pay it for as long as you have Part B, which for most people means for the rest of your life.

Example: If you delayed enrollment by 24 full months without a valid exception, you’d pay an extra 20% on top of the standard $202.90 premium in 2026 — roughly $40.58 more, every month, permanently.

How Part B Works with Group Insurance

Just like Part A, whether you can safely delay Part B without penalty comes down to one specific number: how many employees your company has.

Companies with 20 or more employees: If you or your spouse are actively working and covered by a genuine group health plan, your workplace insurance is primary, and you can legally delay Part B without any penalty. When that employment or coverage eventually ends, you get an 8-month Special Enrollment Period to enroll in Part B penalty-free.

Companies with fewer than 20 employees: Medicare automatically becomes your primary insurer at 65, regardless of your employment status. You need to enroll in Part B right on schedule. If you don’t, your small employer’s plan can legally refuse to pay claims that Medicare should have covered first — potentially leaving you responsible for the full cost.

Paul’s Honest Take: I say this in nearly every guide I write, because it’s genuinely one of the costliest misunderstandings I encounter: “I have good coverage at work” and “I’m protected from Medicare’s enrollment deadlines” are two completely different statements, and whether the second one is true depends entirely on your employer’s size — not how generous the coverage feels. Confirm the actual employee count before you decide to delay anything.

Retiree Coverage Is Not the Same as Active Employer Coverage

This is a distinction that catches a genuinely large number of people off guard: the “20 or more employees” exception only applies to active employment. If you retire and your former employer offers you retiree health benefits — sometimes a genuinely good, comprehensive plan — that coverage does not create a Special Enrollment Period the way active group coverage does, and it does not exempt you from enrolling in Part B on time.

Paul’s Honest Take: I’ve seen this mistake more than once, and it’s an especially painful one because it happens to people who did everything right during their working years. Someone retires with a strong retiree health plan from a large employer, assumes it works the same way their active coverage did, and delays Part B — only to find out later that retiree coverage was never a valid reason to delay in the first place. The moment you stop actively working, that clock starts, regardless of how good your retiree plan looks on paper. If you’re retiring and keeping employer retiree benefits, treat enrolling in Part B as something to handle right on schedule, not something retiree coverage lets you postpone.

Why You Need Both Part A and Part B for Medigap or Medicare Advantage

Here’s a foundational requirement worth understanding clearly, since it shapes every other coverage decision in Medicare: you must be enrolled in both Part A and Part B before you can buy a Medigap policy or enroll in a Medicare Advantage plan. Neither product exists as a standalone substitute for Original Medicare — both are built specifically to work alongside it.

  • Medigap fills the cost-sharing gaps left by Original Medicare (Parts A and B) — it has nothing to fill in if you’re not enrolled in both parts to begin with.
  • Medicare Advantage legally must provide at least the same coverage as Parts A and B combined, which is only possible because you’re required to be enrolled in both before a Medicare Advantage carrier can enroll you.

Paul’s Honest Take: This surprises people who assume they can somehow “skip” Part B and go straight into a Medicare Advantage plan to avoid the extra premium. It doesn’t work that way — Part B enrollment, and its premium, is a prerequisite either way, whether you end up on Original Medicare with Medigap or on a Medicare Advantage plan. There’s no path through Medicare that avoids the Part B premium once you’re actually using the system.

Does Medicare Work If You’re a Veteran?

Yes — and if you have VA health benefits, understanding how the two systems relate is genuinely important, because they work differently than most people assume.

Medicare and VA benefits do not coordinate. These are two entirely separate systems that each pay only for care received within their own network. Medicare doesn’t pay for care you receive at a VA facility, and VA benefits don’t pay for care you receive from a non-VA doctor or hospital. You, the veteran, choose which system to use each time you seek care.

Here’s the critical point: having VA benefits does not exempt you from Medicare’s enrollment deadlines. VA coverage is not considered a qualifying reason to delay Part B without penalty. If you don’t enroll in Part B during your Initial Enrollment Period and you’re relying solely on VA benefits, you can still trigger the permanent late enrollment penalty.

Why the VA itself recommends enrolling in Medicare anyway:

  • It gives you access to civilian doctors and hospitals outside the VA system
  • VA healthcare funding depends on annual Congressional appropriations, which isn’t guaranteed to remain stable
  • If VA authorizes only part of your needed care at a non-VA facility, Medicare can help cover the rest
  • Having both gives you meaningfully more flexibility and security than relying on either system alone

Paul’s Honest Take: This is one of the most common misconceptions I run into with veterans specifically, and it’s an expensive one to get wrong. Good VA coverage feels like it should be enough, and it might genuinely handle most of your care — but it doesn’t protect you from the Part B enrollment clock the way employer coverage from a large company can. The VA itself actively encourages enrolling in Medicare Parts A and B for exactly this reason. If you have VA benefits and are approaching 65, this is worth a direct conversation before you assume you’re covered.

Veterans who enroll in Part B can also purchase a Medigap policy, which can be particularly valuable if you use non-VA providers regularly — though if you primarily rely on VA facilities for most of your care, the value of an added Medigap policy may be more limited, and worth weighing carefully.

How Long Does It Actually Take to Get Part B Approved?

This is one of the most practical, and most overlooked, pieces of planning — especially if you’re leaving a job after 65 and coordinating your Part B start date around the end of your employer coverage. Applying isn’t instant, and the timeline depends heavily on which enrollment window you’re using.

Enrollment Situation

Typical Processing Time

When Coverage Actually Starts

Initial Enrollment Period (around 65)

2–4 weeks, sometimes up to 6

1st of your birthday month (if applied in the 3 months before) or 1st of the month after you apply (if applied during or after your birthday month)

Special Enrollment Period (leaving employer coverage)

4–8 weeks, sometimes longer

1st of the month after your application is submitted

General Enrollment Period (Jan 1–Mar 31, missed window)

4–6 weeks

1st of the month after you apply

Why the Special Enrollment Period takes longer: applying after leaving employer coverage requires two forms, not one — Form CMS-40B (the actual Part B application) and Form CMS-L564 (Request for Employment Information), which your employer needs to complete to verify you had qualifying coverage. Social Security has to manually review both, which is exactly why this route consistently takes longer than a standard Initial Enrollment Period application.

Paul’s Honest Take: This timeline question comes up constantly with clients who are retiring or leaving a job after 65, and it deserves real attention — not just because of the penalty risk we’ve already covered, but because a slow approval can leave you with an actual gap in coverage if you time it too tightly. My standard advice: start this process at least 2 to 3 months before you need Part B to actually begin, not the week your employer coverage ends. If your former employer is slow to complete their portion of Form CMS-L564, that alone can hold up the entire application — so it’s worth following up with your HR or benefits department directly rather than assuming it’s been submitted.

Practical tips to avoid delays

  • Apply online through SSA.gov whenever possible. It’s consistently the fastest method — mailed or faxed forms are more prone to getting lost or delayed.
  • If you’re on a Special Enrollment Period, submit Form CMS-L564 alongside Form CMS-40B, not separately. They need to arrive together, and one incomplete form can stall the whole application.
  • Expect a short intake lag even with online applications. It can take several business days for an online submission to actually appear on a local Social Security agent’s screen — don’t panic if you call shortly after applying and they say they don’t see it yet.
  • Once approved, you don’t have to wait for your physical card. Your Medicare Beneficiary Identifier typically appears in your online Social Security or Medicare.gov account within a day or two of approval, and you can print a temporary card from there — the physical card generally arrives by mail within about 30 days.

Excess Charges: The Cost Almost Nobody Knows to Ask About

Here’s a detail that surprises even people who’ve been on Medicare for years: not every doctor who accepts Medicare agrees to accept Medicare’s approved amount as full payment.

Providers fall into three categories:

  • Participating providers accept Medicare assignment, meaning they agree to accept the Medicare-approved amount as payment in full. This covers the vast majority of providers — roughly 98% of doctors nationally.
  • Non-participating providers still accept Medicare patients but haven’t agreed to accept the standard rate. They can charge an excess charge of up to 15% above the Medicare-approved amount.
  • Opted-out providers have left the Medicare system entirely and can charge whatever they want under a private contract — Medicare pays nothing at all for care from these providers, except in emergencies.

How excess charges actually work: if the Medicare-approved amount for a service is $300 and you see a non-participating provider, they can legally charge up to an additional $45 (15%) on top, for a total bill of $345 — and that excess amount doesn’t count toward your Part B deductible.

Eight states currently prohibit or limit excess charges entirely: Connecticut, Massachusetts, Minnesota, New York, Ohio, Pennsylvania, Rhode Island, and Vermont. If you live in one of these states, you’re generally shielded from excess charges from providers within your state — though you could still face them if you receive care from a non-participating provider elsewhere.

Paul’s Honest Take: This is exactly why Medigap Plan G matters so much for people who want maximum flexibility. Plan G covers excess charges in full — Plan N does not. If you’re the kind of person who wants the freedom to see any doctor without worrying about billing surprises, that distinction is worth understanding clearly before you pick between the two. And regardless of which plan you choose, it’s always worth asking a new provider directly whether they accept Medicare assignment before your first appointment.

The HSA Rule: Part B Closes the Door Too

If you’re hoping to keep contributing to a Health Savings Account, know this clearly: enrolling in Part B — or any part of Medicare — ends your ability to make new HSA contributions. This isn’t unique to Part B; it applies the moment you enroll in Medicare in any form, including premium-free Part A.

If keeping your HSA active matters to you, the only way to legally delay both Part A and Part B is through qualifying employer coverage — which, as covered above, generally requires an employer with 20 or more employees. And because Part A enrollment can be backdated up to 6 months once you do enroll, it’s smart to stop HSA contributions 6 months before you plan to sign up for Medicare or file for Social Security, whichever comes first.

Frequently Asked Questions

Is there a cap on what I’ll pay for Part B services in a year? Not under Original Medicare alone — the 20% coinsurance has no yearly limit. A Medigap policy or Medicare Advantage plan is what actually caps your exposure.

What happens if I don’t sign up for Part B on time? You’ll generally face a permanent 10% penalty on your premium for every 12-month period you went without coverage, unless you qualify for a Special Enrollment Period through active employer coverage.

Do I need Part B if I have good coverage through a small employer? Almost certainly yes. If your employer has fewer than 20 employees, Medicare becomes your primary insurer at 65 regardless of your job coverage, and not enrolling can leave you exposed to unpaid claims and a lifelong penalty.

Do veterans need Medicare Part B if they have VA benefits? Generally, yes. Medicare and VA benefits don’t coordinate — each only pays for care within its own system — and VA coverage doesn’t exempt you from Medicare’s enrollment deadlines or penalties.

What is a Part B excess charge? An additional charge, up to 15% above the Medicare-approved amount, that a non-participating provider can legally bill you. It doesn’t count toward your deductible, and only Medigap Plan G (among current plans) covers it in full.

Can I keep contributing to my HSA if I enroll in Part B? No. Enrolling in any part of Medicare, including Part B, ends your HSA contribution eligibility going forward.

How long does it take to get approved for Part B? It depends on the enrollment window. Initial Enrollment Period applications typically process in 2–4 weeks. Special Enrollment Period applications, used when leaving employer coverage, generally take 4–8 weeks since Social Security must manually verify your prior coverage using Form CMS-L564. Start the process at least 2–3 months before you need coverage to begin, especially when coordinating around a job ending.

The Bottom Line

Part B is the half of Medicare that covers your everyday medical care — and it’s also where the real financial exposure of Original Medicare lives, thanks to that uncapped 20% coinsurance. Whether you should enroll at 65, whether you can safely delay, and how much of that exposure you’re carrying all depend on details specific to your situation: your employer’s size, your income, your VA status, and which doctors you actually see.

If you want help sorting out exactly how Part B applies to your specific circumstances — or want to understand how Medigap or Medicare Advantage could close that uncapped coinsurance gap — that’s exactly the conversation I have with clients every day, at no cost to you.

Call 631-358-5793 or visit paulbinsurance.com to set up a time to talk it through.

Paul Barrett, CMIP, is the founder of The Modern Medicare Agency, based in Melville, NY, and has spent 18+ years exclusively helping people navigate Medicare — never life insurance, never annuities, just Medicare. He’s licensed in 37 states, represents more than 40 carriers, and has personally helped over 5,000 clients choose coverage that actually fits their lives.

Figures current as of 2026 and sourced from CMS, Medicare.gov, and the Social Security Administration. Individual circumstances vary, especially around employer coverage, VA benefits, and income-based premiums — always verify your specific situation before making enrollment decisions.

Sources

Related Post

Scroll to Top

Request a Callback with
Paul Barrett

Fill out the form below, and we'll call you within 24 hours.