
You can switch Medigap carriers in Missouri during your policy’s anniversary window, typically from about a month before to about a month after that date, without answering health questions, as long as you move to the same lettered plan you already have. Move to a plan with richer benefits or try to switch outside that window, and the new carrier can ask about your health history before approving you.
TL;DR:
- Your protected window runs from 30 days before to 30 days after your policy’s original effective date, not its purchase date or latest bill.
- Guaranteed issue applies only when you switch to the identical plan letter; moving from Plan G to Plan N or richer coverage can trigger underwriting.
- Compare local premiums with Missouri’s Rate Shopper Tool, which updates rates twice monthly, then confirm quotes directly because discounts or payment methods may change them.
- Keep your existing policy active until the new carrier confirms approval and the effective date in writing; cancel only after replacement coverage begins.
Table of Contents
- What Missouri’s Medigap anniversary rule actually means
- Who qualifies and what counts as a same-letter switch
- How to find your anniversary date and compare plans before the window opens
- Step-by-step checklist to switch carriers during your window
- Limits, underwriting triggers, and mistakes that cost people money
- How Paul Barrett and our team help Missourians use this window
- Why shopping your anniversary window is worth the effort
- Get help using your anniversary window with Paul B Insurance
- FAQ
- Sources
What Missouri’s Medigap anniversary rule actually means
Missouri built this rule to keep Medigap carriers competing for your business every year instead of just once, when you first enroll. The Missouri Department of Commerce and Insurance requires carriers to accept a same-letter switch from another Missouri policyholder during the protected window, with no medical underwriting and no new waiting periods for pre-existing conditions.
The timing matters more than most people realize. Missouri’s shopping guide describes the window as the period starting 30 days before your policy’s anniversary date and ending 30 days after it, giving you a window of about two months to shop and apply. Some state materials also reference a June 1 through July 30 shopping period, which reflects guidance tied to specific plan cycles rather than a separate universal rule. Your own anniversary date, not a fixed calendar date, is what controls your personal window in most cases.
Your anniversary date is the day your current policy first took effect, not the date you bought it or the date on your most recent bill. That effective date appears in a few predictable places:
- Your policy schedule or declarations page, usually on the first page of your contract
- Your annual renewal notice, which carriers are required to send before premiums change
- Your premium invoice, which sometimes lists the policy’s original effective date in small print
Confirming this date before you start shopping prevents the single most common error in this process: applying too early or too late and losing your guaranteed-issue protection for the year.
Who qualifies and what counts as a same-letter switch
This protection applies to anyone who already holds a Missouri Medigap policy and wants to move to a different carrier offering the identical plan letter. If you have Plan G now, moving to another company’s Plan G during your window is protected. The same logic applies to Plan A, Plan D, Plan K, Plan L, and other standardized letters sold in Missouri.
What trips people up is assuming any plan change counts. It does not. Here is the practical breakdown:
- A Plan G to Plan G switch between carriers is protected and guaranteed issue during your window.
- A Plan G to Plan N switch, or any move to a plan with different benefits, is treated as a new application and can involve medical underwriting.
- Older or nonstandard policies sold before Missouri adopted the current standardized letters may need special handling, since a direct same-letter match may not exist.
If you are on a nonstandard or legacy plan, your options depend on what Missouri carriers currently offer for that coverage level. It is worth confirming availability before you assume a clean, protected swap is possible, since not every carrier sells every letter in every part of the state.
For readers who want the broader legal context behind these protections, our guide to guaranteed issue rights for Medigap walks through how state-level rights like this one interact with federal guaranteed-issue events.
How to find your anniversary date and compare plans before the window opens
Start by pulling your most recent renewal notice and policy schedule. Both documents should list your policy’s effective date, which is your anniversary date for this purpose. If you cannot locate either one, call your current carrier’s customer service line and ask directly. Carriers are used to this question and can usually confirm the date in a single call.
Once you have a confirmed date, use the Missouri Medigap Rate Shopper Tool to compare same-letter premiums across carriers before your window opens. You will enter your zip code, age, and smoker status, and the tool returns rate comparisons for plans sold in your area.
The Missouri Department of Commerce and Insurance updates rate data in this tool twice monthly, so checking close to your shopping window gives you current pricing rather than outdated figures.
A few habits make this step worth the time:
- Run the comparison at least a few weeks before your window opens so you have time to request quotes and ask follow-up questions.
- Save screenshots or printouts of the rates you find, since premiums can shift between your research and your application date.
- Note which carriers are actively selling in your county, since not every company serves every part of Missouri.
Pro Tip: Call two or three carriers directly after using the Rate Shopper Tool, since published rates sometimes differ slightly from what you’re quoted once household discounts or payment methods are factored in.
Step-by-step checklist to switch carriers during your window
Once you know your anniversary date and have compared same-letter rates, the actual switch follows a predictable sequence. Missouri’s shopping guide outlines the acceptable proof and timing, and following these steps in order keeps you from losing guaranteed-issue protection or creating a coverage gap.
- Confirm your exact window dates. Count 30 days before and 30 days after your policy anniversary, and mark both dates clearly so you know your application deadline.
- Gather your documentation. Pull your renewal notice, your most recent premium invoice, and your policy schedule showing your current plan letter and effective date. Any one of these typically satisfies a new carrier’s proof requirement.
- Request final quotes from the carriers you shortlisted using the Rate Shopper Tool, confirming the quoted rate still applies and asking what paperwork they require.
- Submit your application either directly with the new carrier or through a licensed agent, making sure the plan letter matches your current coverage exactly.
- Confirm your new policy’s effective date in writing before you do anything else. Carriers will typically set this to align with your anniversary window.
- Keep your old policy active until you have written confirmation that the new policy has been approved and its effective date has arrived.
- Cancel your old policy only after the new one is active, submitting cancellation in writing and keeping a copy for your records.
If a carrier denies your application or tries to apply underwriting to what should be a protected same-letter switch, contact the Missouri Insurance Consumer Hotline at 800-726-7390. The Department of Commerce and Insurance can intervene when a carrier appears to be misapplying the anniversary rule. For a broader look at the mechanics of switching outside this specific window, our step-by-step guide to switching Medicare Supplement plans covers the general process carriers expect.
Limits, underwriting triggers, and mistakes that cost people money
The anniversary rule protects a lot, but it does not erase every restriction in the Medigap market. Switching to a plan with more benefits than your current letter almost always triggers medical underwriting, and a carrier can deny you or add waiting periods for pre-existing conditions if your health history raises concerns.
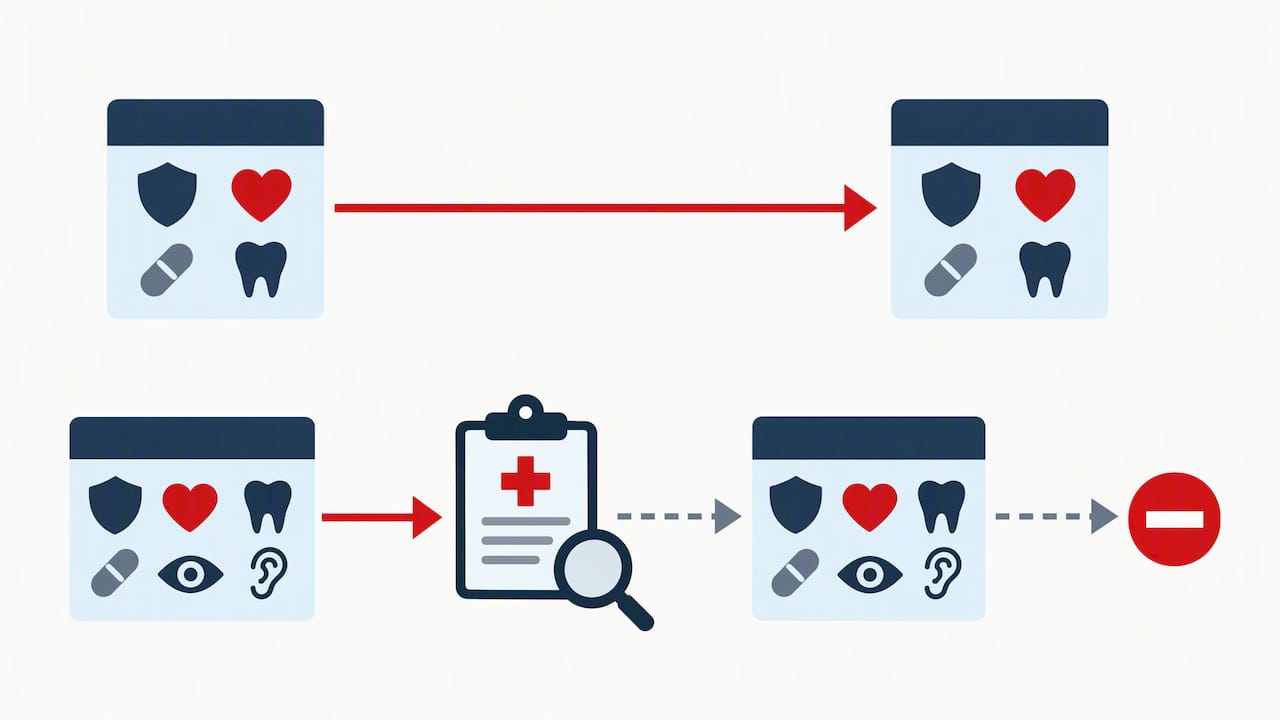
Not every carrier accepts switches to plans with fewer benefits either. Availability varies, and some companies simply do not sell every standardized letter in every Missouri county, which can narrow your real options even when the rule technically allows the move.
One decision carries more weight than the rest: switching from Medigap to a Medicare Advantage plan ends your Medigap coverage entirely, according to Medicare. If you later want to return to Medigap, you may face medical underwriting outside a guaranteed-issue event, so this is not a decision to make casually during an anniversary window.
Common mistakes we see include:
- Canceling the old policy before the new one’s effective date is confirmed, creating a coverage gap.
- Showing up to apply without a renewal notice, invoice, or policy schedule, which slows down the proof-of-coverage process.
- Assuming the anniversary rule applies to a plan upgrade, then being surprised by a medical questionnaire.
- Missing the 60-day window entirely because the anniversary date was never confirmed in advance.
How Paul Barrett and our team help Missourians use this window
We have experience helping Medicare consumers and spend a good part of each year assisting Missouri policyholders with this rule. We confirm your anniversary date against your paperwork, run comparisons across the carriers active in your area, and handle the application paperwork so nothing gets submitted late or incomplete.
Here is what that support typically looks like:
- We verify policy effective dates using available documents or by contacting carriers.
- We compare same-letter rates across carriers licensed in the county.
- We prepare and submit applications, confirming effective dates before cancellation.
- If a carrier disputes or applies underwriting incorrectly, we assist in documenting the issue and contacting the Missouri Insurance Consumer Hotline.
If you are unsure whether your situation qualifies for a protected switch, that is exactly the kind of question worth asking before you submit anything.
Why shopping your anniversary window is worth the effort
Premiums for the identical plan letter can differ meaningfully between carriers in the same Missouri zip code, and most people never find that out because they assume their current company’s renewal rate is the market rate. It usually is not.
The anniversary rule exists precisely so you can test that assumption every year without medical risk. Skipping it because the paperwork feels tedious is the real cost, not the ten minutes it takes to pull your renewal notice and run a rate comparison.
— Paul
Get help using your anniversary window with Paul B Insurance
Working through anniversary-date confirmation, rate comparisons, and carrier paperwork on your own is doable, but it takes time most people would rather spend elsewhere. We handle the full process: confirming your anniversary date, comparing same-letter rates across Missouri carriers, submitting your application, and confirming your new effective date before you cancel anything.
- We help confirm anniversary windows to guide timing.
- We provide comparisons of same-letter premiums across carriers active in your area.
- We assist with application submission and confirm effective dates to avoid gaps.
| What we check | Why it matters |
|---|---|
| Your policy’s anniversary date | Sets the exact 60-day window you have to switch |
| Same-letter rates across carriers | Shows whether you’re overpaying for identical coverage |
| New policy’s effective date | Prevents a coverage gap when you cancel the old plan |
If you would like a free review of your current Medicare Supplement plan and a side-by-side look at what else is available in your area, reach out to our team and bring your renewal notice and policy schedule. We will handle the rest.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Is there Medicare in Missouri?
Yes, Medicare operates in Missouri the same way it does nationwide, covering eligible residents aged 65 and older along with younger people who qualify due to disability. Missouri residents can also purchase Medigap, Medicare Advantage, and Part D plans from carriers licensed in the state.
What is the biggest mistake seniors make when enrolling in Medicare?
One of the most common and costly mistakes is missing a guaranteed-issue window, whether that’s the federal Medigap Open Enrollment Period or a state-specific right like Missouri’s anniversary rule. Missing these windows can mean facing medical underwriting later, which may raise your premium or limit your options.
What is the open enrollment period for Medigap coverage?
The federal Medigap Open Enrollment Period lasts six months, starting the first month you’re 65 or older and enrolled in Medicare Part B. Missouri’s anniversary rule is a separate, state-specific right that gives existing policyholders an additional yearly window to switch carriers without underwriting.
How many people in Missouri will lose Medicaid?
We don’t have publicly listed figures on Medicaid enrollment changes in Missouri to share here. For current Medicaid eligibility and enrollment information, Missouri residents should check directly with the Missouri Department of Social Services.
Sources
- 2025 Medigap shopping guide — Missouri Department of Commerce and Insurance
- If you already have a Medigap policy — switching or dropping | Medicare