
Your Medigap open enrollment period is a one-time, six-month window. It begins on the first day of the month in which you are both 65 or older and enrolled in Medicare Part B. For those six months, any insurer selling Medigap in your state has to sell you a policy, whatever your health history. Once the window closes, it does not come back around the way Medicare’s fall enrollment does, so the timing is worth getting right.
This guide covers how the window is calculated, what changes if you work past 65 or are on Medicare because of a disability, what insurers can and cannot do, and what to do if you have already missed it.
TL;DR
- Medigap open enrollment lasts six months and starts the first month you have Part B and are 65 or older. Medicare.gov confirms it happens once.
- During the window, insurers cannot deny you, charge more for health conditions, or use medical underwriting. A waiting period is allowed only for coverage tied to a pre-existing condition.
- Delaying Part B because of employer coverage also delays your window. It starts when Part B starts, not when you turn 65.
- Medicare’s October 15 to December 7 open enrollment is a different thing. It does not give you a Medigap guarantee.
- People under 65 on Medicare have no federal Medigap guarantee. Many states fill the gap, so check your state’s rules.
Table of Contents
- What the Medigap open enrollment period is
- How to find your start and end dates
- What insurers can and cannot do during the window
- What happens if you miss it
- Medigap open enrollment is not Medicare open enrollment
- If you are under 65 on Medicare
- Perspective: why we tell people to treat this window as a deadline
- A checklist for your window
- Get help comparing Medigap plans
- FAQ
- Sources
What the Medigap open enrollment period is
Medigap, also called Medicare Supplement insurance, is sold by private insurers. It helps pay costs that Original Medicare leaves behind, such as deductibles, coinsurance and copayments. Because private companies sell it, they normally get to ask health questions before they sell you a policy. That is called medical underwriting, and it is how an applicant with a heart condition or diabetes can be turned down or quoted a higher price.
The open enrollment period suspends that. Under federal law you get a six-month Medigap Open Enrollment period that starts the first month you have Part B and are 65 or older. It is your best chance to buy any Medigap plan offered in your area at the rate your age and location earn, with no health screening.
Three features make it unusual:
- It is personal. Your window depends on your own Part B date, not on a calendar date that applies to everyone.
- It is one time. Medigap open enrollment does not repeat every year, unlike Medicare’s annual open enrollment.
- It is a protection, not a deadline to buy. You can buy a policy any time. The window just guarantees the terms.
How to find your start and end dates
The rule is simple: the clock starts the month you are 65 or older and have Part B. It starts on the first day of that month, so your birthday date within the month does not shorten it.
Here are a few worked examples. They are illustrations, not dates for anyone in particular.
| Situation | Part B starts | Medigap window |
|---|---|---|
| You turn 65 in a given month and sign up for Part B right away | That month (if your birthday is on the 1st, the month before) | Six months from the first day of the month Part B starts |
| You turn 65 but keep working with employer coverage and delay Part B for a year | A year later | Six months starting the first day of that later month |
| You enroll in Part B at 66 after a gap | The month Part B begins | Six months from that month |
If your birthday falls on the first of the month, Medicare counts you as turning 65 the month before, which can move your Part B start. Our guide on when Part B starts walks through that detail. For a second look at the length of the window, see how long the Medigap open enrollment period lasts.
If you are still working at 65
Many people keep employer or union coverage past 65 and delay Part B. That is allowed, and it often makes sense. Your Medigap window follows Part B. Medicare explains that employer coverage often resembles Medigap, and that your one-time window starts once you sign up for Part B and lasts six months, even if you sign up while you still have employer coverage.
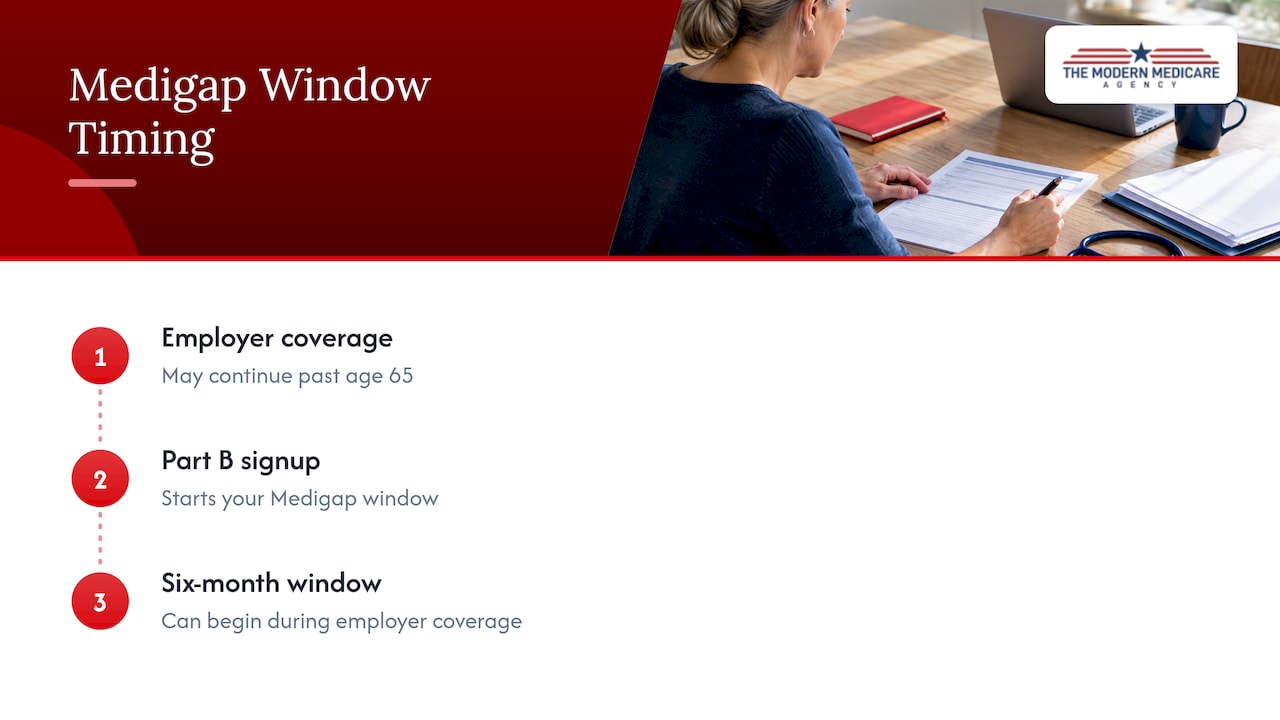
The practical point: do not buy Medigap while an employer plan is still your main coverage unless you have a reason. Wait until you enroll in Part B, then use your window. If you are not sure which of your coverages pays first, ask your benefits office before you decide.
What insurers can and cannot do during the window
This is the part that protects people with health problems. During your window, an insurance company cannot refuse to sell you a Medigap policy it offers, and cannot use medical underwriting to deny coverage because of pre-existing health problems. It also cannot make you wait for coverage to start, with one exception: coverage related to a pre-existing condition.
In plain terms:
- No denial. A cancer history or a heart condition cannot be the reason you are turned down.
- No health-based surcharge. Federal law bars charging more for pre-existing conditions during this period.
- Some waiting is possible. A policy may delay coverage for a condition you had before, which is why a policy’s start terms matter. If you had other qualifying coverage before, ask the agent or insurer how it applies to any waiting period.
- Choice is still yours. The guarantee covers policies the insurer sells. Not every company sells every plan letter in every state, so the lineup depends on where you live.
This is also where an independent view helps. Pricing for the same plan letter can differ from carrier to carrier, and a guarantee of acceptance is not a guarantee of a good price. We compare carriers side by side so you can see that difference before you pick.
What happens if you miss it
Missing the window does not mean you can never get Medigap. It means the insurer gets underwriting back. According to Medicare, after the period ends an insurer may charge you more, offer fewer policy options, or deny your application if you don’t meet its medical underwriting requirements.
What that looks like in practice depends on your health:
- Healthy applicants often still get approved, sometimes at a fair price. The risk is lower for them, but it is not zero, and health can change before you apply.
- Applicants with conditions may be declined outright by some carriers, offered only certain plans, or quoted higher rates.
- Everyone faces questions about their medical history and sometimes a review of prescription records.
If you see a recommended plan that has dental or vision features, remember that Medigap generally does not pay for routine dental care. Planning ahead for dental care as you age is separate from your Medigap choice, and it is something we cover with standalone dental plans.
Guaranteed issue rights are a second route
Some events give you a Medigap guarantee outside the first window. Examples include losing certain employer retiree coverage or a Medicare Advantage plan ending. The conditions are specific, and the time limit to act is short. Read our overview of Medigap guaranteed issue rights and how these rights work in detail if you think you have had a qualifying event.
States also add protections. Thirty-seven states require Medigap insurers to issue policies to beneficiaries 65 and older after certain qualifying events, and 29 of those cover changes in employer retiree coverage. Your state insurance department can tell you what applies where you live.
Medigap open enrollment is not Medicare open enrollment
This mix-up is common, and it is especially easy to fall into at this time of year. Medicare’s annual open enrollment runs October 15 through December 7 each year. It lets you change Medicare Advantage and Part D plans. It does not create a Medigap guarantee.
Federal rules give beneficiaries only one guaranteed-issue Medigap open enrollment period in their lifetime. You can apply for a Medigap policy during the fall period, but the insurer can still underwrite you unless another protection applies.
| Medigap open enrollment | Medicare annual open enrollment | |
|---|---|---|
| How often | Once | Every year |
| Length | Six months | October 15 to December 7 |
| Starts | The month you are 65+ and have Part B | Same dates for everyone |
| What it guarantees | Acceptance for a Medigap policy without health screening | Changes to Medicare Advantage and Part D plans |
If you are comparing the two, our pages on Medicare open enrollment and every key Medicare enrollment date lay out the calendar.
The birthday rule in some states
A handful of states go further than federal law. The birthday rule exists in 16 states and lets current Medigap holders switch plans without medical underwriting around their birthday. The window typically opens 30 days before the birthday and runs at least 30 days after it, and in many cases it only lets you move to a policy with the same or lesser benefits, sometimes only with the same insurer. Check your state’s exact terms before you count on it.
If you are under 65 on Medicare
People who qualify for Medicare through disability, and those with end-stage renal disease, often ask whether they get the same protection. Federally, they do not. There are no federal guaranteed issue protections for beneficiaries under 65, but many states have their own rules. Thirty-eight states require insurers to offer at least one kind of Medigap policy to under-65 beneficiaries with disabilities during an initial open enrollment period, regardless of medical conditions.
That has real consequences:
- In many states you get a guaranteed window, but in some it is shorter, or limits you to one or a few plan types.
- In states without a rule, an insurer may decline you or charge more because of your health.
- When you turn 65, you get the federal six-month window at that point, regardless of where you live. Many people on disability Medicare wait for that date if the state offers nothing.
Because the rules differ by state, this is one area where a specialist can save you hours of calls. Your state insurance department or your state’s SHIP counseling program can also confirm the details.
Perspective: why we tell people to treat this window as a deadline
We have helped Medicare consumers since 2007, and the pattern is consistent. People rarely regret using their Medigap window on purpose. They regret the ones they let slip by, usually because a letter got lost, an employer plan changed, or nobody explained that the window only comes once.
Our view is education first. The window does not oblige you to buy Medigap, and Medigap is not right for everyone. Some people are better served by Medicare Advantage, and that is a legitimate choice. But if you think you might ever want Medigap, the six months after Part B starts is when the choice is easiest and fairest. Learn your dates, ask for quotes from several carriers, and decide without pressure. If you are leaning toward Medicare Advantage, remember that going back to Medigap later may mean underwriting. That trade-off should be a decision you make knowingly, not a surprise.
— Paul
A checklist for your window
- Confirm your Part B start date. It sets the clock. Your Medicare card or your Social Security account shows it.
- Write down your end date. Count six months from the first day of that month.
- Decide what you need. Think about how often you see doctors, whether you travel, and how much cost uncertainty you can live with.
- Compare carriers for the same plan letter. Benefits are standardized across insurers, so price and service are the differences. Our guide to choosing a Medicare Supplement covers the choices.
- Apply well before the window closes. Give yourself weeks, not days, in case a form is wrong.
- Pair it with drug coverage. Medigap does not cover prescriptions, so look at Part D plans at the same time.
Get help comparing Medigap plans
We are independent agents with access to more than 40 carriers, so we can show you how the same plan letter is priced across companies. We do not rely on pressure and we focus on what fits you. If your window is open now, or you want to check whether you have another route to guaranteed coverage, start with our Medicare Supplement (Medigap) page and we will go through your options with you. You can also read the full Medigap guide first.
If you are choosing the best time to apply, our article on why open enrollment is the best time to apply explains the reasoning in more depth.
FAQ
When is Medigap open enrollment?
It begins on the first day of the month you are 65 or older and enrolled in Part B, and it lasts six months. Because it depends on your own Part B start date, it is different for each person. Check your Medicare card for the Part B date and count from the first of that month.
Can you be denied Medigap during open enrollment?
No. During this period an insurer cannot refuse to sell you a Medigap policy it offers, and it cannot use medical underwriting because of pre-existing health problems. It can apply a waiting period for coverage tied to a pre-existing condition. That applies to policies the company sells in your state.
Does Medigap open enrollment come back every year?
No. It is a one-time period, unlike Medicare’s annual open enrollment from October 15 to December 7. A few states offer an annual window for changing plans, such as the birthday rule, but that is a state rule rather than a federal one.
Can I get Medigap if I am under 65 and on disability?
It depends on your state. Federal law has no guarantee for people under 65, but 38 states require insurers to offer at least one Medigap policy to under-65 beneficiaries with disabilities during an initial period. Ask your state insurance department or an independent agent what your state requires.
Sources
- Get ready to buy | Medicare.gov
- When can I buy a Medigap policy? | Medicare.gov
- Medigap Guaranteed Issue Requirements: An Overview of Federal and State Rules | KFF
- The birthday rule: a gift to Medigap enrollees? | Medicare Resources
- Aging | DC Implant & Cosmetic Dentistry