Medicare Information: Find Free, Reliable Help and Counseling

Medicare Information: Find Free, Reliable Help and Counseling

To learn how to find a reliable source of Medicare information, start with Medicare’s official customer support at 1-800-633-4227, according to the Centers for Medicare & Medicaid Services.

It’s understandable to feel unsure when plan choices, provider details, and enrollment questions all seem connected. You don’t have to sort through them alone. This guide will show you which resource fits each need and how to get clear, impartial help through SHIP counseling.

You’ll learn what Medicare can answer by phone, how Medicare.gov can help you compare plans, and how SHIP counselors support beneficiaries, families, and caregivers. Starting with the right resource can help you move from uncertainty to a more confident next step.

Key Takeaways

  • For official Medicare questions, call 1-800-633-4227; use Medicare.gov to compare plans and find providers.
  • SHIP counselors offer one-on-one Medicare counseling and education to beneficiaries, families, and caregivers.
  • Choose the resource that matches your need, whether it’s program information, plan comparisons, or personal counseling.
  • Rely on official Medicare resources for program details, then use impartial guidance to make sense of your options.
  • When you’re ready to compare Medicare Advantage, Medigap, or Part D plans, an independent broker can help you understand available choices.

Contacting Medicare by phone or live chat

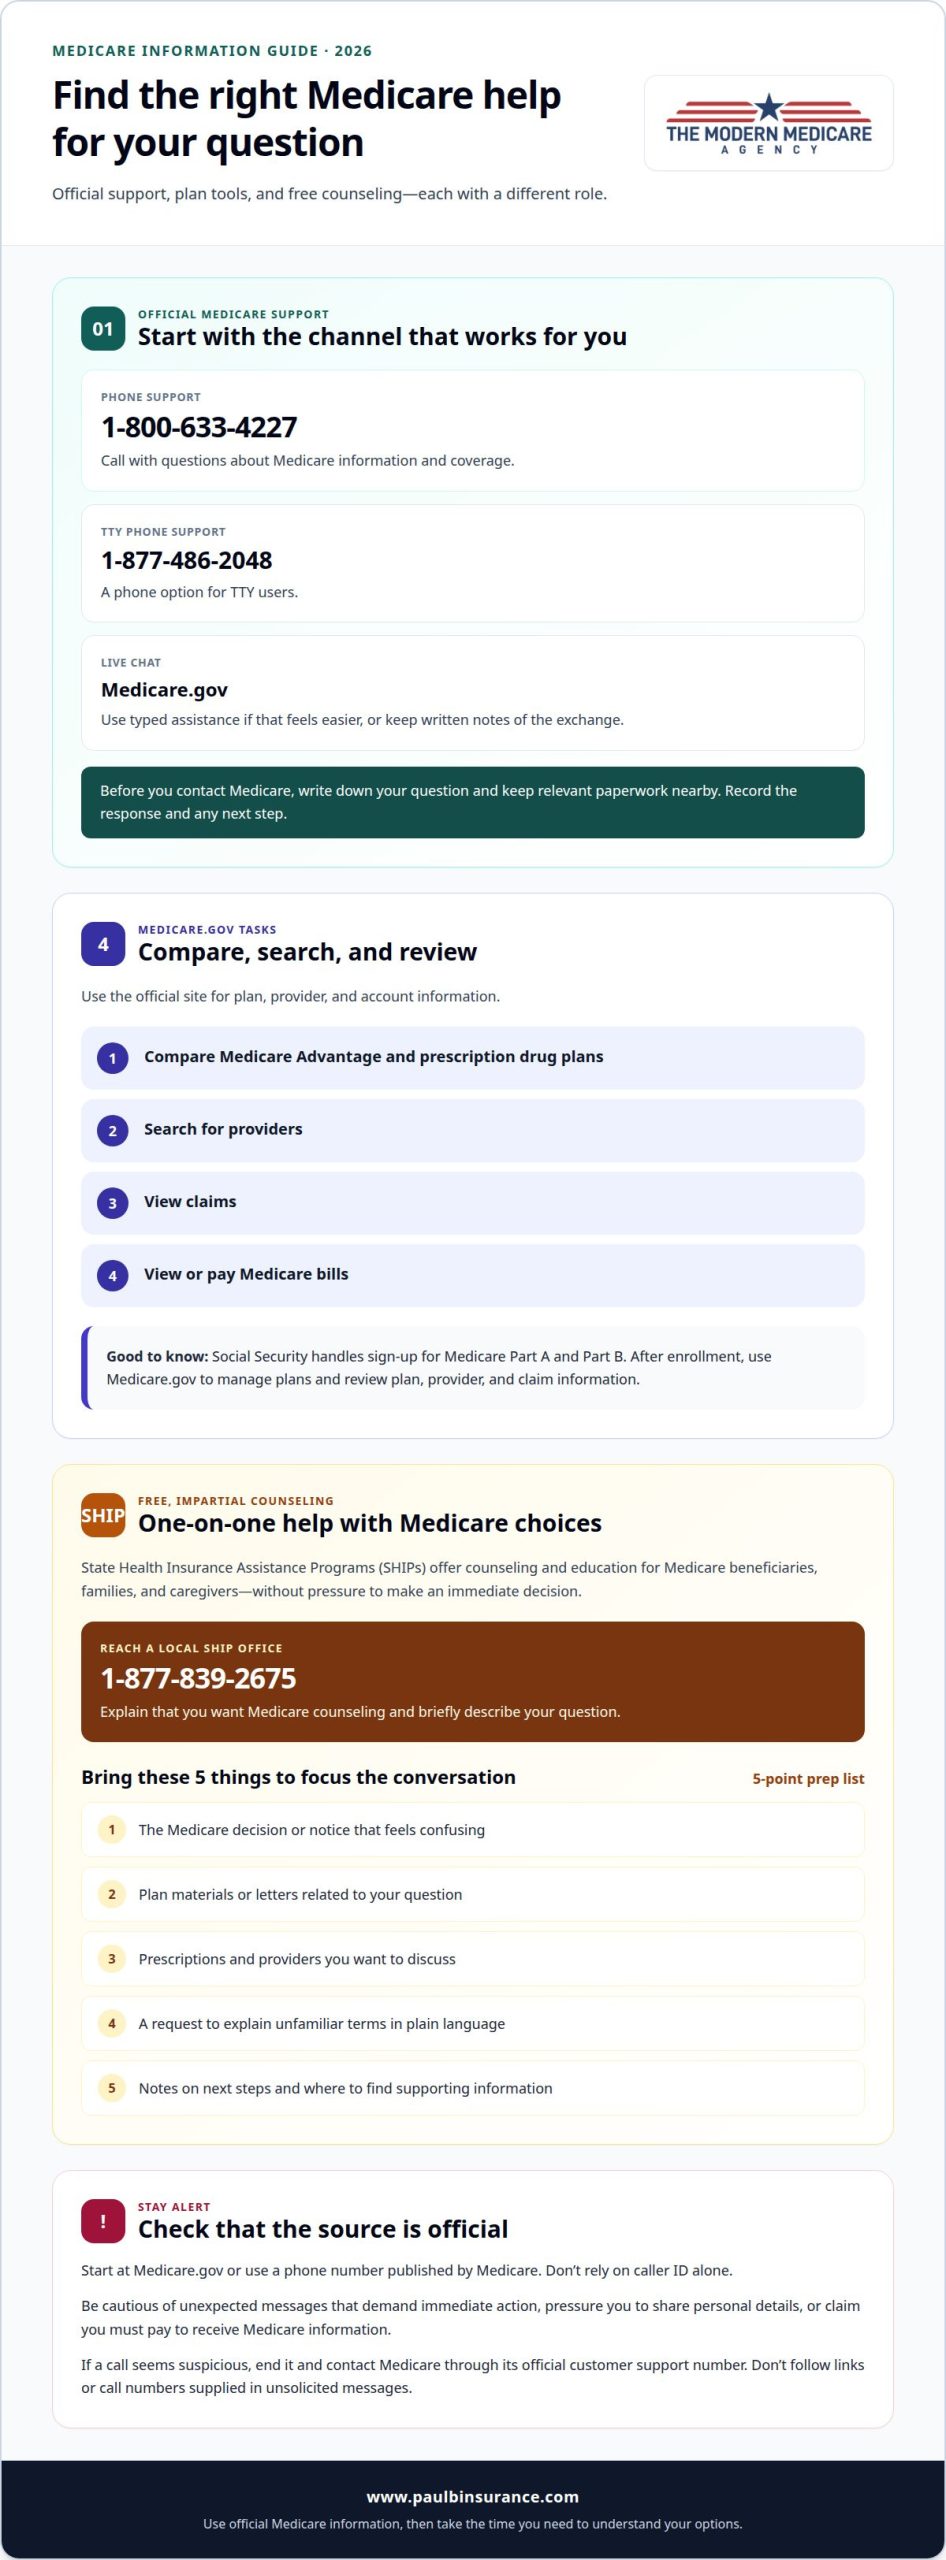
For an official answer about Medicare, use Medicare customer support or the live chat on Medicare.gov. According to the Centers for Medicare & Medicaid Services, people can call 1-800-633-4227 to ask Medicare customer support questions. TTY users can call Medicare at 1-877-486-2048, according to the Centers for Medicare & Medicaid Services. These are useful starting points for questions about Medicare information and coverage.

Before calling, write down your question and the coverage type, notice, or enrollment step involved. For example, ask where to find information about a claim or which Medicare resource explains a plan detail. Keep relevant paperwork nearby, but share personal information only when it’s needed for the conversation. A concise question can make the answer easier to understand and help you decide what to do next.

Medicare initial enrollment is a key consideration for people approaching age 65 or who have recently turned 65, according to the Centers for Medicare & Medicaid Services. If this applies to you, ask Medicare which enrollment information is relevant to your situation. Note the response and any next step. If the answer refers to a form or notice, ask for its exact name so you can locate the correct information afterward.

Medicare-eligible people can also contact customer support through live chat on Medicare.gov. Chat can be useful if typing is easier than calling or you want written notes of the exchange. State your question plainly, such as asking where Medicare explains a coverage term. For complicated topics, break your question into smaller points and ask the representative to address them one at a time.

To verify that a Medicare website or phone number is legitimate, start at Medicare.gov or use a phone number published by Medicare rather than trusting one in an unexpected message. Don’t rely on caller ID alone. End a suspicious call and contact Medicare through its official customer support number.

Warning signs include unexpected messages demanding immediate action, pressure to share personal details, or claims that you must pay to receive Medicare information. Treat unsolicited calls and messages cautiously, and don’t follow their links or call the numbers they provide. If you believe someone is giving Medicare false information, report your concern through an official Medicare channel.

Choose the contact method that fits your question: phone support for direct questions, TTY for accessible phone contact, and Medicare.gov live chat for typed assistance. Record the date, your question, and any next step. These notes make it easier to follow up without relying on memory.

Free, impartial Medicare counseling

Medicare choices can feel difficult when coverage details affect your everyday care. A State Health Insurance Assistance Program, known as SHIP, offers one-on-one assistance, counseling, and education for Medicare beneficiaries, their families, and caregivers. SHIP counseling can help you understand Medicare information without pressure to make an immediate decision.

SHIP counselors can help explain how Medicare choices relate to your needs. Bring a specific question, such as how to understand a coverage notice or what to consider when reviewing plan options. You can also describe the care you use and the prescriptions you take, so the conversation stays relevant to your situation.

To make a counseling session useful, prepare a short list before you speak with a counselor:

  • Write down the Medicare decision or notice that is confusing you.
  • Gather plan materials or letters related to that question.
  • List the prescriptions and providers you want to discuss.
  • Ask the counselor to explain unfamiliar terms in plain language.
  • Note any next steps and where to find supporting information.

Preparation helps keep the discussion focused. If you’re reviewing coverage, for example, ask how a plan’s rules relate to your care and prescriptions. If an answer raises another question, ask for clarification before moving on. You can also request a simpler explanation. You don’t need to understand every detail at once.

SHIP assistance is especially useful when you want to learn about Medicare before making a choice. A counselor can help you understand the information and identify questions to resolve, while you remain in control of the decision. SHIP also serves caregivers helping a parent or another family member. Bring the person’s questions and relevant plan information to keep the discussion focused.

To reach a local State Health Insurance Assistance Program office, call 1-877-839-2675. When you contact the office, explain that you want Medicare counseling and briefly describe your question. This gives staff a clear starting point for directing you to local assistance. Keep the number with your Medicare notes so you can find it again when another coverage question arises.

After a session, review your notes and separate confirmed answers from questions that still need attention. Use the counselor’s explanations to understand your options, then consult official Medicare resources for program details. Combining these resources can make complicated information easier to follow without rushing you into a decision.

Using Medicare.gov to compare plans and find providers

Medicare.gov brings several useful Medicare tasks together. You can compare Medicare Advantage and prescription drug plans, search for providers, view claims, and view or pay Medicare bills. If you’re wondering how to find a reliable source of Medicare information, start with the official tool that matches your question. This keeps your search focused on the plan, provider, or record you need.

How do Social Security and Medicare.gov differ? Social Security handles sign-up for Medicare Part A and Part B. After enrollment, use Medicare.gov to manage plans and review plan, provider, and claim information.

To compare plans, enter the requested information and review the available options. Consider coverage alongside the providers and prescriptions that matter to you. For 2026, review the cost details shown for each plan as well as its coverage. Don’t choose by plan name alone. The right comparison depends on the benefits and care you expect to use.

Use the provider search to look for a doctor, hospital, or other provider. Enter a name or location details, then review the results. A listing can help you find options, but it won’t answer every question about whether a particular plan covers a specific service. Review the plan and service details together.

To check whether a doctor, hospital, drug, or service is covered by Medicare, search for providers on Medicare.gov and review coverage details for the plan or service. For prescriptions, use the drug-plan comparison tool and include the medications you take.

Medicare.gov can also help after you receive care. Sign in to view claims and bills, then review what Medicare processed. If something raises a question, note the claim or bill details and date of care. This gives you specific information to refer to when seeking an explanation.

For official Medicare eligibility, enrollment, and deadline rules, use Medicare.gov for program and plan information, and Social Security to sign up for Part A and Part B. If you’re learning how to find a reliable source of Medicare information about an enrollment step, look for official instructions that address your situation.

Before comparing, gather details that make your review specific:

  • Names of providers or hospitals you want to search for.
  • Prescriptions to include in plan comparisons.
  • A Medicare claim or bill you need to understand.
  • The coverage question you want the comparison to answer.

Keep your review focused on your needs. Medicare.gov brings plan comparisons, provider searches, claims, and bills together in one place. If a result leaves a coverage question unresolved, note the plan or service involved and seek clarification through an official Medicare channel.
Medicare Information: Find Free, Reliable Help and Counseling

State Health Insurance Assistance Programs (SHIPs)

A State Health Insurance Assistance Program, or SHIP, provides one-on-one Medicare assistance, counseling, and education for beneficiaries, their families, and caregivers. This personal support is useful when a general explanation leaves you unsure how information applies to your coverage choices.

A SHIP conversation can focus on the question that matters most to you. Bring a plan notice and ask what its terms mean, or discuss how to compare coverage based on your providers and prescriptions. The goal is to understand the information clearly, then decide what action makes sense for you.

To make your time productive, prepare a short agenda. Choose one main decision and gather only the materials related to it. A focused discussion might cover:

  • A Medicare letter or plan notice you find difficult to understand.
  • Questions about comparing coverage choices.
  • How your providers or prescriptions fit into a plan review.
  • What official information could help answer a remaining question.

Caregivers can use SHIP support, too. If you’re helping a parent, ask which Medicare decision they want to discuss. Bring relevant plan information and write down questions beforehand. During the conversation, encourage them to describe their own priorities. This keeps the discussion centered on the beneficiary, not assumptions made on their behalf.

SHIP counseling can help distinguish between different kinds of questions. Asking what a Medicare term means is educational; comparing plan choices requires attention to the person’s coverage needs; and a question about a claim or bill may require reviewing the document itself. Naming the issue helps the counselor focus the conversation and identify useful next steps.

After speaking with a counselor, organize your notes into three parts: what you understand, what decision remains, and what information you still need. You might understand a notice but still need to compare how plans handle a prescription. This simple record gives you a clear basis for follow-up instead of making you start over from memory.

To reach a local SHIP office, call 1-877-839-2675. Tell the office you’re seeking Medicare counseling, then give a brief description of your topic. A concise example helps: “I need help understanding a plan notice,” or “I’m comparing coverage choices.” Keep your questions and related papers together for the conversation.

SHIP is a useful resource for one-on-one help understanding Medicare information. Use it to clarify your questions, discuss your circumstances, and identify a practical next step. For details about a specific plan or Medicare program rule, follow up with the relevant official information.

What are the most reliable official sources for Medicare information?

Start with Medicare.gov for Medicare coverage and plan tasks. The site lets you compare Medicare Advantage and prescription drug plans, find providers, view claims, and view or pay Medicare bills. These tools can help you review plan options, locate care, or understand a bill. Choose the tool that matches your question instead of relying on a general search result.

Use Social Security to sign up for Medicare Part A and Part B. After enrollment, use Medicare.gov to manage plans. This distinction directs your question to the right agency: ask Social Security about signing up, then use Medicare.gov to compare plans or review claims.

The Centers for Medicare & Medicaid Services, or CMS, administers Medicare. For direct customer support questions, call Medicare’s official number: 1-800-633-4227. TTY users can call 1-877-486-2048. Use these numbers when you need help finding official program information or understanding where to direct a question.

For one-on-one education, a State Health Insurance Assistance Program (SHIP) serves Medicare beneficiaries, families, and caregivers through counseling and assistance. SHIP can help when you understand a general rule but want to discuss how it relates to your situation. Its role differs from Medicare.gov’s self-service tools and Medicare customer support.

Match the source to the task:

  • Medicare.gov: Compare plans, search for providers, view claims, or review bills.
  • Social Security: Get information about signing up for Medicare Part A and Part B.
  • Medicare customer support: Ask program questions by phone.
  • SHIP: Get one-on-one Medicare counseling and education.

Before sharing personal details, make sure a site or phone number belongs to the official organization. Type the agency’s name into your browser, then use its own navigation to find the relevant page. Avoid phone numbers from unexpected calls or messages. If a message claims to be from Medicare, contact Medicare separately through its official support number.

When comparing plans, consider Medicare.gov results alongside your care needs. Keep the providers and prescriptions you want to consider nearby, and review coverage details rather than judging plans by their names. If an official page leaves a term unclear, write down its exact wording and ask Medicare support or a SHIP counselor to explain it.

A reliable approach in 2026 is to use official sources for program information and plan tools, then seek personal counseling when you need help applying that information. Each resource has a distinct purpose, so choosing the right one can make the next step clearer.

The Modern Medicare Agency

When official information leaves you unsure how to compare plan options, The Modern Medicare Agency offers personalized guidance as an independent brokerage. It helps people considering Medicare Advantage, Medigap, or Part D plans understand their choices. The agency complements, rather than replaces, Medicare and government resources for official program rules.

The agency compares plans from over 40 carriers and supports clients across more than 34 states. Bring your questions about coverage, providers, or prescriptions, and discuss what matters most to you. You can then consider your options with clearer information and decide what fits your needs.

For personal help comparing Medicare plan options, contact The Modern Medicare Agency for a free consultation.

Take Your Next Step With Confidence

Your next Medicare decision can begin with one clear question: what matters most to you in your coverage? Writing down that priority can help focus conversations and keep you from feeling rushed. Reliable Medicare information gives you a foundation, while personal guidance can help you understand how choices relate to your needs. Knowing how to find a reliable source of Medicare information isn’t about making every decision at once. It’s about taking the next step with clarity.

The Modern Medicare Agency helps people compare Medicare Advantage Plans, Medicare Supplement (Medigap) Plans, and Medicare Part D Plans. If you’re ready to talk through your options, you’re welcome to contact The Modern Medicare Agency. Bring the questions you still have and the coverage priorities that matter to you. A thoughtful conversation can help you consider your choices at your own pace.

The best person to contact depends on what you need: Medicare for official program questions, Medicare.gov to compare plans and find providers, and a State Health Insurance Assistance Program (SHIP) counselor for one-on-one guidance. TTY users can call 1-877-486-2048.

Frequently Asked Questions

Who is the best person to talk to about Medicare?

The right resource depends on whether you need an official program answer or help weighing plan choices. Contact Medicare for official program questions and speak with a SHIP counselor for one-on-one Medicare education. If you’re choosing among Medicare Advantage, Medigap, or Part D plans, an independent broker can help compare options. Before the conversation, write down the decision you’re facing to keep the discussion focused on your needs.

How does Medicare.gov help compare plans, coverage, and costs?

Medicare.gov lets you compare Medicare Advantage and prescription drug plans using details relevant to your care. When reviewing drug coverage, include the prescriptions you take instead of judging plans by their names alone. You can also search for providers, review claims, and view or pay Medicare bills. Use the comparison results to identify coverage or cost questions that need a closer look.

What information can Medicare beneficiaries get from 1-800-MEDICARE?

Medicare beneficiaries can call 1-800-MEDICARE with customer support questions about the program. If a letter or online notice uses a term you don’t understand, describe the wording and ask where to find the official explanation. Keep the notice nearby so you can refer to its title and details. For TTY access, Medicare lists a separate number for callers who use text telephone service.

How can State Health Insurance Assistance Programs (SHIPs) provide free Medicare counseling?

SHIPs offer one-on-one counseling and education to Medicare beneficiaries, family members, and caregivers. A conversation can help you organize a difficult decision, such as identifying questions to ask about coverage before choosing a plan. Bring the specific issue you want to discuss and ask the counselor to explain unfamiliar terms. This personal support can help you approach your next step with greater clarity.

How can I find local Medicare help and counseling in my state?

Call 1-877-839-2675 to reach your local State Health Insurance Assistance Program office. Tell the office which state you live in and whether you’re seeking help for yourself or supporting a family member. Briefly describe the question you want to discuss, such as a confusing plan notice or a choice you’re weighing. This gives the local office a clear starting point for directing your request.
Paul Barrett

Article by

Paul Barrett

Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.

He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.

📞 631-358-5793 | paulbinsurance.com
What Is Medicare Part B and What Does It Actually Cover?

The complete guide to Medicare’s medical insurance — every service it covers, exactly what it costs in 2026, how it works with group insurance and VA benefits, and the excess charges most people have never heard of until they get a surprise bill.

The Short Answer

Medicare Part B is medical insurance — it covers doctor visits, outpatient care, preventive services, durable medical equipment, and more. Unlike Part A, Part B is not premium-free for anyone: everyone pays a monthly premium (202.90in2026formostpeople),anannualdeductible(283), and 20% coinsurance on most covered services, with no yearly cap on that 20% under Original Medicare alone. Whether you need to enroll at 65, and whether delaying is safe, depends heavily on your employment status and your employer’s size — getting this wrong is one of the most consequential and permanent mistakes in all of Medicare.

Key Takeaways

  • Part B is never premium-free — everyone pays a monthly premium, and higher earners pay significantly more through IRMAA.
  • The 20% coinsurance under Original Medicare alone has no yearly cap — this is the single biggest financial risk in Medicare, and it’s the reason Medigap and Medicare Advantage exist.
  • Whether you can safely delay Part B without a penalty depends on your employer’s size: 20+ employees generally allows delay; fewer than 20 generally does not.
  • Missing your enrollment window triggers a permanent 10% penalty for every 12-month period you went without coverage.
  • Veterans can and generally should enroll in Part B even with VA benefits, since Medicare and VA coverage don’t coordinate — each only pays for care received within its own system.
  • “Excess charges” from non-participating providers can add up to 15% on top of what Medicare approves, and only some Medigap plans protect you from them.

What Part B Actually Covers

While Part A handles hospital room and board, Part B is the half of Original Medicare that covers medical care and most services delivered outside a hospital admission — doctor visits, outpatient procedures, and ongoing medical needs.

What’s covered

  • Doctor visits — primary care and specialists
  • Outpatient surgeries and procedures
  • Diagnostic lab work, X-rays, and MRIs
  • Emergency room visits
  • Ambulance services
  • Outpatient mental health care
  • Physical, occupational, and speech therapy
  • Chemotherapy and radiation received in an outpatient clinic
  • Durable Medical Equipment (DME) — wheelchairs, oxygen equipment, blood sugar monitors, walkers, and similar equipment
  • Ambulatory surgical center services

Preventive services: the part Medicare gets genuinely right

Most preventive services are covered at 100%, with no deductible and no copay, as long as your provider accepts Medicare assignment. This includes:

  • Your one-time “Welcome to Medicare” wellness visit, available within your first 12 months on Part B
  • Annual wellness visits after that
  • Flu shots and most other recommended vaccines
  • Mammograms
  • Colonoscopies and other cancer screenings
  • Diabetes and cardiovascular screenings
  • Many other screenings recommended by the U.S. Preventive Services Task Force

Paul’s Honest Take: This is one of the most underused parts of Medicare, full stop. I’ve had clients who paid for a private physical every year out of habit and never realized their annual wellness visit through Medicare was completely free. If you haven’t used your Welcome to Medicare visit or your annual wellness visit, that’s real value sitting on the table.

What’s NOT covered

  • Routine dental care — cleanings, fillings, dentures, extractions
  • Routine vision exams and eyeglasses
  • Hearing aids (though diagnostic hearing tests ordered by a doctor may be covered)
  • Long-term custodial nursing home care — help with daily living activities, as opposed to short-term skilled or medical care
  • Routine prescription drugs you pick up at a retail pharmacy — that’s Part D’s job, not Part B’s
  • Cosmetic surgery, unless medically necessary (such as reconstruction after an accident or mastectomy)
  • Most care received outside the United States, with very limited exceptions
  • Routine foot care, such as nail trimming, in the absence of a qualifying medical condition
  • Acupuncture, except for a narrow, specific chronic low back pain benefit
  • Concierge medicine fees and membership-style charges some practices add on top of standard care
  • Long-term care insurance-style services, including most home-based personal care that isn’t tied to a skilled medical need

Paul’s Honest Take: The dental and vision exclusions are the ones that surprise people most, especially since they’re such routine parts of healthcare for most adults. This is exactly why so many Medicare Advantage plans build dental, vision, and hearing benefits into their coverage — Original Medicare was simply never designed to include them, and that gap doesn’t go away on its own.

What Part B Costs in 2026

Part B has three separate cost components, and understanding all three matters:

Cost Component

2026 Amount

Standard monthly premium

$202.90

Annual deductible

$283

Coinsurance on most covered services

20%

The premium is deducted automatically from your Social Security check if you’re already collecting benefits. If you’re not yet collecting Social Security, you’ll receive a bill, typically every three months.

The deductible works differently than Part A’s — it’s a straightforward annual figure. You pay the first $283 of Medicare-approved outpatient costs each calendar year, and then Medicare’s cost-sharing kicks in.

The coinsurance is where the real risk lives. After your deductible is met, Medicare pays 80% of the Medicare-approved amount for most covered services, and you’re responsible for the remaining 20%. There is no yearly cap on this 20% under Original Medicare alone. If you have a $100,000 course of cancer treatment, your 20% share is $20,000 — unless you have a Medigap policy or Medicare Advantage plan absorbing that cost.

Paul’s Honest Take: I put this in bold because it’s genuinely the single most important number in this entire guide. That uncapped 20% is the whole reason Medigap and Medicare Advantage exist as products in the first place. Original Medicare by itself was never designed to protect you from a truly expensive year — it was designed to cover 80% of it and leave the rest to you.

IRMAA: What Higher Earners Actually Pay

If your income is above certain thresholds, you’ll pay more for Part B through the Income-Related Monthly Adjustment Amount (IRMAA) — based on your tax return from two years prior. For 2026, that means your 2024 income determines your premium tier.

2024 Income (Individual)

2024 Income (Married, Joint)

Total Part B / Month

$109,000 or less

$218,000 or less

$202.90

$109,001 – $137,000

$218,001 – $274,000

$284.10

$137,001 – $171,000

$274,001 – $342,000

$405.80

$171,001 – $205,000

$342,001 – $410,000

$527.50

$205,001 – $499,999

$410,001 – $749,999

$649.20

$500,000 and above

$750,000 and above

$689.90

At the top tier, you’re paying more than three times the standard premium. If your income has recently dropped — retirement, the loss of a spouse, or certain other life-changing events — you can appeal your IRMAA determination using Form SSA-44.

Do You Have to Enroll? And What Happens If You Don’t?

Technically, Part B is optional — Medicare won’t force you into it. But opting out without a valid alternative is genuinely risky, because of how the penalty structure works.

If you don’t sign up during your Initial Enrollment Period (the 7-month window around your 65th birthday) and you don’t have qualifying employer coverage, you’ll face a permanent 10% penalty added to your premium for every full 12-month period you went without Part B. That penalty doesn’t expire — you pay it for as long as you have Part B, which for most people means for the rest of your life.

Example: If you delayed enrollment by 24 full months without a valid exception, you’d pay an extra 20% on top of the standard $202.90 premium in 2026 — roughly $40.58 more, every month, permanently.

How Part B Works with Group Insurance

Just like Part A, whether you can safely delay Part B without penalty comes down to one specific number: how many employees your company has.

Companies with 20 or more employees: If you or your spouse are actively working and covered by a genuine group health plan, your workplace insurance is primary, and you can legally delay Part B without any penalty. When that employment or coverage eventually ends, you get an 8-month Special Enrollment Period to enroll in Part B penalty-free.

Companies with fewer than 20 employees: Medicare automatically becomes your primary insurer at 65, regardless of your employment status. You need to enroll in Part B right on schedule. If you don’t, your small employer’s plan can legally refuse to pay claims that Medicare should have covered first — potentially leaving you responsible for the full cost.

Paul’s Honest Take: I say this in nearly every guide I write, because it’s genuinely one of the costliest misunderstandings I encounter: “I have good coverage at work” and “I’m protected from Medicare’s enrollment deadlines” are two completely different statements, and whether the second one is true depends entirely on your employer’s size — not how generous the coverage feels. Confirm the actual employee count before you decide to delay anything.

Retiree Coverage Is Not the Same as Active Employer Coverage

This is a distinction that catches a genuinely large number of people off guard: the “20 or more employees” exception only applies to active employment. If you retire and your former employer offers you retiree health benefits — sometimes a genuinely good, comprehensive plan — that coverage does not create a Special Enrollment Period the way active group coverage does, and it does not exempt you from enrolling in Part B on time.

Paul’s Honest Take: I’ve seen this mistake more than once, and it’s an especially painful one because it happens to people who did everything right during their working years. Someone retires with a strong retiree health plan from a large employer, assumes it works the same way their active coverage did, and delays Part B — only to find out later that retiree coverage was never a valid reason to delay in the first place. The moment you stop actively working, that clock starts, regardless of how good your retiree plan looks on paper. If you’re retiring and keeping employer retiree benefits, treat enrolling in Part B as something to handle right on schedule, not something retiree coverage lets you postpone.

Why You Need Both Part A and Part B for Medigap or Medicare Advantage

Here’s a foundational requirement worth understanding clearly, since it shapes every other coverage decision in Medicare: you must be enrolled in both Part A and Part B before you can buy a Medigap policy or enroll in a Medicare Advantage plan. Neither product exists as a standalone substitute for Original Medicare — both are built specifically to work alongside it.

  • Medigap fills the cost-sharing gaps left by Original Medicare (Parts A and B) — it has nothing to fill in if you’re not enrolled in both parts to begin with.
  • Medicare Advantage legally must provide at least the same coverage as Parts A and B combined, which is only possible because you’re required to be enrolled in both before a Medicare Advantage carrier can enroll you.

Paul’s Honest Take: This surprises people who assume they can somehow “skip” Part B and go straight into a Medicare Advantage plan to avoid the extra premium. It doesn’t work that way — Part B enrollment, and its premium, is a prerequisite either way, whether you end up on Original Medicare with Medigap or on a Medicare Advantage plan. There’s no path through Medicare that avoids the Part B premium once you’re actually using the system.

Does Medicare Work If You’re a Veteran?

Yes — and if you have VA health benefits, understanding how the two systems relate is genuinely important, because they work differently than most people assume.

Medicare and VA benefits do not coordinate. These are two entirely separate systems that each pay only for care received within their own network. Medicare doesn’t pay for care you receive at a VA facility, and VA benefits don’t pay for care you receive from a non-VA doctor or hospital. You, the veteran, choose which system to use each time you seek care.

Here’s the critical point: having VA benefits does not exempt you from Medicare’s enrollment deadlines. VA coverage is not considered a qualifying reason to delay Part B without penalty. If you don’t enroll in Part B during your Initial Enrollment Period and you’re relying solely on VA benefits, you can still trigger the permanent late enrollment penalty.

Why the VA itself recommends enrolling in Medicare anyway:

  • It gives you access to civilian doctors and hospitals outside the VA system
  • VA healthcare funding depends on annual Congressional appropriations, which isn’t guaranteed to remain stable
  • If VA authorizes only part of your needed care at a non-VA facility, Medicare can help cover the rest
  • Having both gives you meaningfully more flexibility and security than relying on either system alone

Paul’s Honest Take: This is one of the most common misconceptions I run into with veterans specifically, and it’s an expensive one to get wrong. Good VA coverage feels like it should be enough, and it might genuinely handle most of your care — but it doesn’t protect you from the Part B enrollment clock the way employer coverage from a large company can. The VA itself actively encourages enrolling in Medicare Parts A and B for exactly this reason. If you have VA benefits and are approaching 65, this is worth a direct conversation before you assume you’re covered.

Veterans who enroll in Part B can also purchase a Medigap policy, which can be particularly valuable if you use non-VA providers regularly — though if you primarily rely on VA facilities for most of your care, the value of an added Medigap policy may be more limited, and worth weighing carefully.

How Long Does It Actually Take to Get Part B Approved?

This is one of the most practical, and most overlooked, pieces of planning — especially if you’re leaving a job after 65 and coordinating your Part B start date around the end of your employer coverage. Applying isn’t instant, and the timeline depends heavily on which enrollment window you’re using.

Enrollment Situation

Typical Processing Time

When Coverage Actually Starts

Initial Enrollment Period (around 65)

2–4 weeks, sometimes up to 6

1st of your birthday month (if applied in the 3 months before) or 1st of the month after you apply (if applied during or after your birthday month)

Special Enrollment Period (leaving employer coverage)

4–8 weeks, sometimes longer

1st of the month after your application is submitted

General Enrollment Period (Jan 1–Mar 31, missed window)

4–6 weeks

1st of the month after you apply

Why the Special Enrollment Period takes longer: applying after leaving employer coverage requires two forms, not one — Form CMS-40B (the actual Part B application) and Form CMS-L564 (Request for Employment Information), which your employer needs to complete to verify you had qualifying coverage. Social Security has to manually review both, which is exactly why this route consistently takes longer than a standard Initial Enrollment Period application.

Paul’s Honest Take: This timeline question comes up constantly with clients who are retiring or leaving a job after 65, and it deserves real attention — not just because of the penalty risk we’ve already covered, but because a slow approval can leave you with an actual gap in coverage if you time it too tightly. My standard advice: start this process at least 2 to 3 months before you need Part B to actually begin, not the week your employer coverage ends. If your former employer is slow to complete their portion of Form CMS-L564, that alone can hold up the entire application — so it’s worth following up with your HR or benefits department directly rather than assuming it’s been submitted.

Practical tips to avoid delays

  • Apply online through SSA.gov whenever possible. It’s consistently the fastest method — mailed or faxed forms are more prone to getting lost or delayed.
  • If you’re on a Special Enrollment Period, submit Form CMS-L564 alongside Form CMS-40B, not separately. They need to arrive together, and one incomplete form can stall the whole application.
  • Expect a short intake lag even with online applications. It can take several business days for an online submission to actually appear on a local Social Security agent’s screen — don’t panic if you call shortly after applying and they say they don’t see it yet.
  • Once approved, you don’t have to wait for your physical card. Your Medicare Beneficiary Identifier typically appears in your online Social Security or Medicare.gov account within a day or two of approval, and you can print a temporary card from there — the physical card generally arrives by mail within about 30 days.

Excess Charges: The Cost Almost Nobody Knows to Ask About

Here’s a detail that surprises even people who’ve been on Medicare for years: not every doctor who accepts Medicare agrees to accept Medicare’s approved amount as full payment.

Providers fall into three categories:

  • Participating providers accept Medicare assignment, meaning they agree to accept the Medicare-approved amount as payment in full. This covers the vast majority of providers — roughly 98% of doctors nationally.
  • Non-participating providers still accept Medicare patients but haven’t agreed to accept the standard rate. They can charge an excess charge of up to 15% above the Medicare-approved amount.
  • Opted-out providers have left the Medicare system entirely and can charge whatever they want under a private contract — Medicare pays nothing at all for care from these providers, except in emergencies.

How excess charges actually work: if the Medicare-approved amount for a service is $300 and you see a non-participating provider, they can legally charge up to an additional $45 (15%) on top, for a total bill of $345 — and that excess amount doesn’t count toward your Part B deductible.

Eight states currently prohibit or limit excess charges entirely: Connecticut, Massachusetts, Minnesota, New York, Ohio, Pennsylvania, Rhode Island, and Vermont. If you live in one of these states, you’re generally shielded from excess charges from providers within your state — though you could still face them if you receive care from a non-participating provider elsewhere.

Paul’s Honest Take: This is exactly why Medigap Plan G matters so much for people who want maximum flexibility. Plan G covers excess charges in full — Plan N does not. If you’re the kind of person who wants the freedom to see any doctor without worrying about billing surprises, that distinction is worth understanding clearly before you pick between the two. And regardless of which plan you choose, it’s always worth asking a new provider directly whether they accept Medicare assignment before your first appointment.

The HSA Rule: Part B Closes the Door Too

If you’re hoping to keep contributing to a Health Savings Account, know this clearly: enrolling in Part B — or any part of Medicare — ends your ability to make new HSA contributions. This isn’t unique to Part B; it applies the moment you enroll in Medicare in any form, including premium-free Part A.

If keeping your HSA active matters to you, the only way to legally delay both Part A and Part B is through qualifying employer coverage — which, as covered above, generally requires an employer with 20 or more employees. And because Part A enrollment can be backdated up to 6 months once you do enroll, it’s smart to stop HSA contributions 6 months before you plan to sign up for Medicare or file for Social Security, whichever comes first.

Frequently Asked Questions

Is there a cap on what I’ll pay for Part B services in a year? Not under Original Medicare alone — the 20% coinsurance has no yearly limit. A Medigap policy or Medicare Advantage plan is what actually caps your exposure.

What happens if I don’t sign up for Part B on time? You’ll generally face a permanent 10% penalty on your premium for every 12-month period you went without coverage, unless you qualify for a Special Enrollment Period through active employer coverage.

Do I need Part B if I have good coverage through a small employer? Almost certainly yes. If your employer has fewer than 20 employees, Medicare becomes your primary insurer at 65 regardless of your job coverage, and not enrolling can leave you exposed to unpaid claims and a lifelong penalty.

Do veterans need Medicare Part B if they have VA benefits? Generally, yes. Medicare and VA benefits don’t coordinate — each only pays for care within its own system — and VA coverage doesn’t exempt you from Medicare’s enrollment deadlines or penalties.

What is a Part B excess charge? An additional charge, up to 15% above the Medicare-approved amount, that a non-participating provider can legally bill you. It doesn’t count toward your deductible, and only Medigap Plan G (among current plans) covers it in full.

Can I keep contributing to my HSA if I enroll in Part B? No. Enrolling in any part of Medicare, including Part B, ends your HSA contribution eligibility going forward.

How long does it take to get approved for Part B? It depends on the enrollment window. Initial Enrollment Period applications typically process in 2–4 weeks. Special Enrollment Period applications, used when leaving employer coverage, generally take 4–8 weeks since Social Security must manually verify your prior coverage using Form CMS-L564. Start the process at least 2–3 months before you need coverage to begin, especially when coordinating around a job ending.

The Bottom Line

Part B is the half of Medicare that covers your everyday medical care — and it’s also where the real financial exposure of Original Medicare lives, thanks to that uncapped 20% coinsurance. Whether you should enroll at 65, whether you can safely delay, and how much of that exposure you’re carrying all depend on details specific to your situation: your employer’s size, your income, your VA status, and which doctors you actually see.

If you want help sorting out exactly how Part B applies to your specific circumstances — or want to understand how Medigap or Medicare Advantage could close that uncapped coinsurance gap — that’s exactly the conversation I have with clients every day, at no cost to you.

Call 631-358-5793 or visit paulbinsurance.com to set up a time to talk it through.

Paul Barrett, CMIP, is the founder of The Modern Medicare Agency, based in Melville, NY, and has spent 18+ years exclusively helping people navigate Medicare — never life insurance, never annuities, just Medicare. He’s licensed in 37 states, represents more than 40 carriers, and has personally helped over 5,000 clients choose coverage that actually fits their lives.

Figures current as of 2026 and sourced from CMS, Medicare.gov, and the Social Security Administration. Individual circumstances vary, especially around employer coverage, VA benefits, and income-based premiums — always verify your specific situation before making enrollment decisions.

Sources

Related Post

Scroll to Top