
Most deferred annuities pay a death benefit to named beneficiaries, typically the account value or a guaranteed minimum, but once the contract has been annuitized, that promise often disappears unless a guarantee was written in. The money goes by contract designation, not the will, and any amount above what the owner put in and never recovered is generally taxable. Start by pulling the contract and beneficiary form and locating your premium and withdrawal records.
TL;DR:
- Beneficiaries will receive the greater of the account value or guaranteed minimum during the accumulation phase, but payments often cease after annuitization unless a joint-and-survivor option is chosen.
- Updating beneficiary designations regularly is crucial, as contract naming overrides wills, and outdated forms can delay or divert payouts into probate.
- Lump-sum distributions provide quick cash but can generate significant tax burdens in a single year, while installment options spread tax obligations over time.
- Qualifying riders can enhance death benefits, such as return of premium or stepped-up death benefits, but they increase the contract’s cost and complexity.
- The IRS does not provide a step-up in basis for inherited annuities, making tax planning essential, especially regarding the 10-year rule for IRAs and the treatment of IRD.
Table of Contents
- What an annuity death benefit actually is and when it applies
- Who can be named beneficiary and how designations actually work
- Payout options beneficiaries can choose after the owner’s death
- How the death benefit amount gets calculated, and what riders add
- U.S. tax rules for beneficiaries: basis, IRD, and distribution timing
- Filing a death benefit claim: documents and timeline
- Weighing an enhanced death benefit against lifetime income
- What two decades of annuity claims have taught this agency
- How Paul B Insurance can help with your annuity review
- Sources
- FAQ
What an annuity death benefit actually is and when it applies
A death benefit is a contract term, a promise the insurer makes when you buy the annuity, not a feature of your estate plan or a guarantee that exists outside the paperwork. Whether a beneficiary collects anything, and how much, depends heavily on where the contract stood when the owner died.
During the accumulation phase, while the owner is still contributing or letting the money grow, most contracts protect that value. The NAIC’s buyer’s guide to fixed deferred annuities describes the standard baseline: beneficiaries typically receive the greater of the account value or the minimum guaranteed surrender value. That is the floor most contracts offer without any extra rider.
Annuitization changes the picture. Once the owner converts the contract into a stream of income payments, the insurer is often paying down a pool of money in exchange for that promise of income. Depending on the payout option chosen at annuitization, there may be nothing left for a beneficiary after the owner’s death.
- Accumulation phase: the contract generally preserves a death benefit equal to account value or a guaranteed minimum.
- After annuitization: payments may stop at death unless the owner elected a period-certain or joint-and-survivor option.
- Contract terms control: the specific language in your annuity, not a general industry rule, determines what happens.
This is why two people who bought what looks like the same type of annuity can leave very different outcomes for their families. The phase of the contract, and the payout election made along the way, matters more than the product label.
Who can be named beneficiary and how designations actually work
Annuity owners can typically name individuals, trusts, charities, or an estate as beneficiary, and each choice carries different processing speed and tax consequences. Naming an individual, especially a spouse, usually moves fastest and offers the most flexible payout choices. Naming a trust or an estate adds legal steps and often changes the tax timeline because the IRS treats non-individual beneficiaries differently under the distribution rules.
Beneficiary designations on an annuity contract generally override whatever a will says. If your will names one person for “all my assets” but your annuity’s beneficiary form still lists an ex-spouse or a sibling from decades ago, the contract usually wins. This single fact catches more families off guard than almost anything else in estate settlement, which is why keeping forms current matters as much as writing a will in the first place.
A contingent beneficiary, the backup if the primary beneficiary has already died, prevents the payout from defaulting to the estate and getting pulled into probate.
- Locate the actual contract and find the current contract number.
- Confirm who is listed as primary beneficiary and whether that designation is still accurate.
- Add or update a contingent beneficiary if one is not already listed.
- Verify the issuing company’s current contact information and claims department.
Running through that checklist every few years, especially after a marriage, divorce, or death in the family, is the single cheapest form of estate planning available.
Payout options beneficiaries can choose after the owner’s death
Once a claim is approved, beneficiaries usually get to choose how the money arrives, and each option trades speed, taxes, and ongoing income differently.
A lump-sum distribution gets cash in hand quickly and settles the matter. The tradeoff is that the entire taxable portion lands in one year, which can push a beneficiary into a higher tax bracket than they would otherwise face. For a large contract, that single-year tax hit can be substantial even though the beneficiary never chose to realize the gain all at once.
Annuitized payments spread the money out as a stream of income instead of a single check. The size and length of those payments depend on actuarial assumptions built into the contract, essentially a bet on how long the payments will run. A period-certain option guarantees payments for a set number of years regardless of anyone’s lifespan, which appeals to beneficiaries who want predictability without tying the payout to a life expectancy calculation.
Joint-and-survivor options matter most for a surviving spouse. Rather than taking a lump sum or a fixed-term payout, a spouse can often continue the contract or convert it into ongoing income that mirrors what the original owner would have received. For a surviving spouse who depended on that income, continuing the contract is frequently the better move financially, since it avoids triggering an immediate large tax bill and keeps the retirement income stream intact.
- Lump sum: fastest access, but the full taxable amount hits in one tax year.
- Annuitized payments: steady income, calculated using mortality assumptions in the contract.
- Period certain: guaranteed payments for a fixed number of years, independent of lifespan.
- Joint and survivor: lets a surviving spouse continue income rather than cashing out.
Qualified annuities, meaning those owned inside an IRA, face an added layer. The IRS’s rules for inherited IRAs generally require most non-spouse beneficiaries to empty the account within ten years of the owner’s death, a constraint that can force a payout schedule the beneficiary would not have chosen otherwise. That rule, often called the 10-year rule, is covered in more detail below.
How the death benefit amount gets calculated, and what riders add
The baseline calculation most contracts use, as described in the NAIC consumer guide, is simple: beneficiaries get the greater of the current account value or a guaranteed minimum surrender value. That floor protects against a scenario where market losses have dragged the account value below what the owner originally put in.
Some contracts go further with riders that cost extra but change the math in the beneficiary’s favor.
- Return of premium: guarantees beneficiaries receive at least what the owner paid in, even if the account value has dropped below that.
- Stepped-up death benefit: locks in the highest account value reached on a contract anniversary, protecting prior gains from a later market downturn.
- Guaranteed minimum accumulation benefit: promises a minimum account value after a set number of years, regardless of market performance.
Say an owner put $100,000 into a variable annuity, and the account value had fallen to $85,000 at the time of death due to market performance. Without a rider, the beneficiary gets $85,000. With a return-of-premium rider in place, the beneficiary gets the full $100,000 instead, since the rider guarantees at least the original premium.
Pro Tip: Ask the issuer for a written statement of the current account value, the guaranteed minimum, and any rider in force before assuming you know what the payout will be.
Riders add cost while the contract is active, so they are a tradeoff the owner makes years before death, not something a beneficiary can add after the fact.
U.S. tax rules for beneficiaries: basis, IRD, and distribution timing
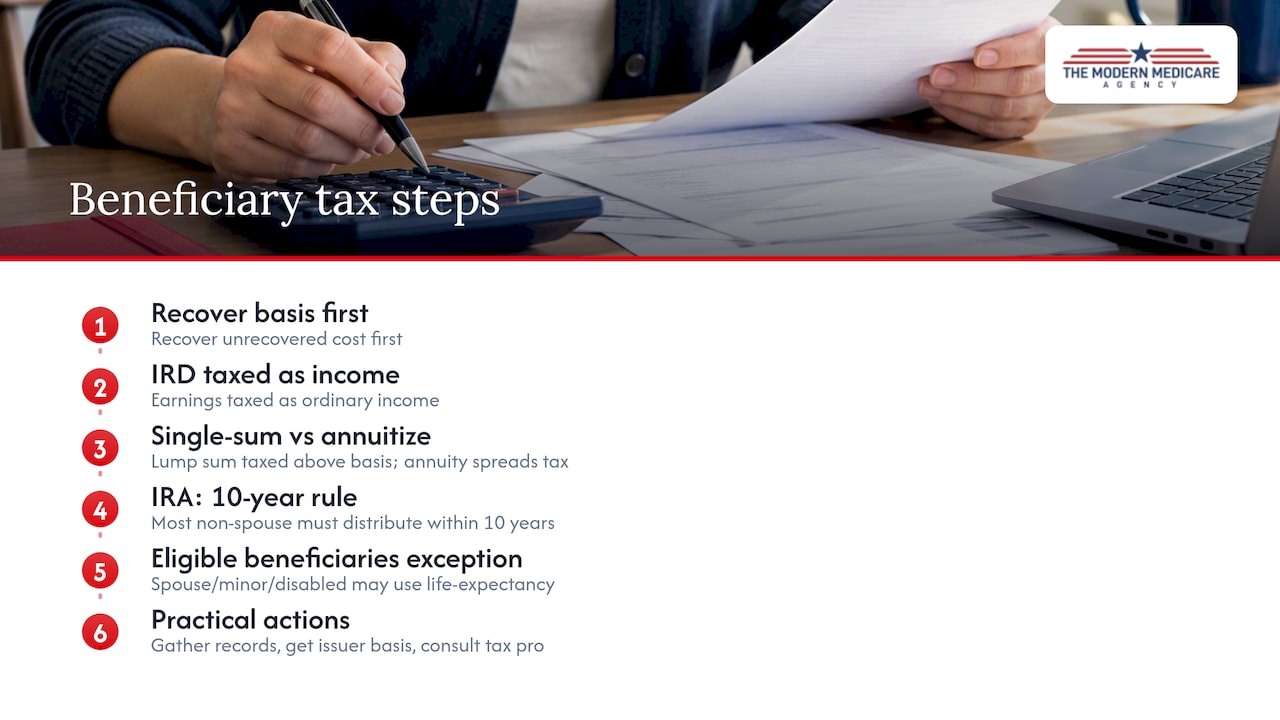
The tax rule beneficiaries need to understand first: you recover the owner’s unrecovered cost, the amount paid in that was never taxed, before anything else is taxable. Earnings above that basis are taxed as ordinary income, a category the IRS calls income in respect of a decedent, or IRD, because the tax liability simply passes to whoever receives the money instead of disappearing at death.
Annuities do not receive a step-up in basis the way many other inherited assets do. That is one of the more consequential, and least understood, differences between an inherited annuity and an inherited brokerage account or home. IRS Publication 575 explains how nonperiodic and periodic payments are taxed and how recovery of investment in the contract works, and the agency’s guidance on revenue rulings tied to Section 72 confirms that amounts which would have been taxable to the original owner remain taxable to the beneficiary, whether paid as a lump sum or spread across periodic payments.
For a single-sum death distribution, Publication 575 states that the payment is taxable only to the extent it exceeds the unrecovered cost in the contract. If the beneficiary instead chooses to annuitize the death benefit into a stream of payments, those payments get taxed under the periodic-payment rules, which spread the taxable and non-taxable portions proportionally across each payment rather than taxing everything in year one.
For qualified annuities, meaning those held inside an IRA, IRS Publication 590-B lays out the 10-year rule: most non-spouse beneficiaries must distribute the entire inherited account by December 31 of the year containing the tenth anniversary of the owner’s death. Certain eligible designated beneficiaries, including a surviving spouse, a minor child of the owner, a disabled or chronically ill individual, or a beneficiary not more than ten years younger than the owner, may qualify for different treatment based on life expectancy rather than the flat ten-year window. The IRS retirement topics page on beneficiaries confirms that a surviving spouse generally has more flexible options than other beneficiary categories, including the ability to treat an inherited IRA as their own in some cases.
The practical sequence matters more than people expect: gather every premium statement and withdrawal record first, ask the issuing company for a breakdown of basis versus earnings, and talk to a tax professional before electing a lump sum on a contract with substantial gains. Electing a payout without that information risks an irreversible decision that creates a larger tax bill than necessary.
Filing a death benefit claim: documents and timeline
Contact the issuing insurance company directly, or go through the agent of record if one is listed, and have the contract number ready before the call. That single number speeds up nearly every step that follows.
- Request the claim form from the insurer and confirm which documents they require.
- Gather a certified copy of the death certificate, since most insurers will not accept a photocopy.
- Have the beneficiary’s identification and proof of relationship to the deceased ready if the insurer asks for it.
- Confirm whether the beneficiary listed is an individual or the estate, since estate-named beneficiaries generally face probate delays that individual beneficiaries avoid entirely.
Insurers vary in how quickly they process claims, but having a current, individually named beneficiary on file, rather than letting the payout default to the estate, is the single biggest factor in avoiding a drawn-out probate process. If the primary beneficiary died before the contract owner and no contingent beneficiary was ever named, the payout typically falls into the estate by default, which is exactly the delay a quick beneficiary-form review could have prevented.
Weighing an enhanced death benefit against lifetime income
Adding a rider that guarantees a larger or more certain death benefit almost always comes at a cost, either a direct fee that reduces account growth or a reduction in the income the contract can otherwise pay the owner during life. That tradeoff, legacy versus lifetime income, sits at the center of nearly every annuity decision involving a beneficiary.
Before adding or keeping an enhanced rider, it helps to ask the issuer a short set of direct questions; for veterans considering benefits, the VA Survivor Benefits & household planning guide can offer useful context.
- What is the waiting period before the enhanced benefit becomes fully effective?
- How much does the rider cost annually, and how is that fee deducted from the account?
- Does adding this rider change the surrender charge schedule or any living benefit already in the contract?
- How do withdrawals during the owner’s lifetime affect the guaranteed death benefit?
Pro Tip: If lifetime income is the bigger concern and you have other assets or life insurance earmarked for heirs, a basic death benefit is often enough; the rider usually matters most when the annuity is meant to double as a legacy tool.
A single retiree with no dependents may not need an enhanced rider at all, since there is no one depending on the payout. A married couple relying on the annuity as a shared retirement asset often benefits more from a joint-and-survivor election than from a death-benefit rider, since it protects the surviving spouse’s income directly. Someone with a limited liquid estate and specific wishes for how money passes to children may find the rider’s added cost worth paying, since it guarantees a floor regardless of market performance.
What two decades of annuity claims have taught this agency
Since 2007, some agencies have worked with Medicare and retirement clients navigating these decisions, and the same two mistakes often appear repeatedly. The first is a beneficiary form that was never updated after a divorce or remarriage, leaving a payout bound for someone the owner never intended. The second is a beneficiary who elects a lump sum without understanding that the taxable portion will be reported as ordinary income in the year received, creating a tax bill no one planned for.
An independent agent’s value in these moments is practical, not dramatic: reviewing the actual contract language, walking a beneficiary through the payout options before they sign anything, and coordinating with a tax professional when the numbers get complicated. Education first, then a referral when the question moves outside insurance and into tax law.
— Paul
How Paul B Insurance can help with your annuity review
Reviewing an annuity contract after a death in the family, or updating beneficiary designations before that day ever comes, is exactly the kind of paperwork that benefits from a second set of eyes. An independent broker with access to multiple carriers reviews the actual contract language rather than guessing at what a product typically does, and refers clients to a tax professional when a decision crosses into tax strategy.
Before reaching out, gather a few things to speed the conversation along:
- The annuity contract number and the issuing company’s name.
- The current beneficiary form, if you have a copy on file.
- Any records of premiums paid and withdrawals taken over the life of the contract.
The agency works on a commission basis paid by carriers when a plan or policy is enrolled through an agent, and the approach stays education-first throughout, with no pressure, providing a clear look at the options. Visit the annuities page to request a contract review or ask about beneficiary updates, and if estate liquidity for final costs is also a concern, the final expense insurance page covers a related option worth a look.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Publication 590‑B, Distributions from Individual Retirement Arrangements (IRAs) (IRS)
- Buyer’s Guide to Fixed Deferred Annuities (NAIC)
FAQ
Do most annuities have a death benefit?
Most deferred annuities include a basic death benefit during the accumulation phase, typically paying the greater of the account value or a guaranteed minimum surrender value, according to the NAIC’s buyer’s guide. Once the contract has been annuitized into income payments, that benefit often ends unless the owner chose a period-certain or joint-and-survivor payout option.
Does everyone get a fixed death benefit amount?
Death benefit amounts depend entirely on the specific contract, its account value, and any riders in force, with no universal fixed amount. Check your contract and beneficiary form directly with the issuing company for the actual guaranteed amount rather than relying on a flat figure.
How much will a $100,000 annuity pay each month?
Monthly payment amounts depend on the payout option chosen, the beneficiary’s age, and the mortality assumptions built into that specific contract, so there is no single figure that applies across annuities. The issuing insurer can provide an illustration showing exact monthly amounts under a lump-sum, period-certain, or life-income election for a given contract.
Can my wife inherit my annuity?
Yes, a spouse named as beneficiary can typically inherit an annuity and often has more flexible options than other beneficiaries, including continuing the contract or converting it to a joint-and-survivor income stream. The IRS’s retirement topics guidance confirms that spousal beneficiaries generally receive different, more favorable treatment than non-spouse beneficiaries under the distribution rules.