Have you ever wondered why some people seem completely at ease with their healthcare while others spend every January regretting their choices? It’s a common fear. Many people worry that a plan which looks great on paper today might leave them stranded without their favorite doctor or hit them with hidden costs in 2026. Focusing on avoiding medicare buyer’s remorse now is the best way to ensure you don’t end up with a plan that simply doesn’t fit your life.
We understand that the sheer volume of options can feel overwhelming. It’s hard to distinguish between the “all-in-one” promises of Medicare Advantage and the long-term flexibility of Medigap when you’re being bombarded with advertisements. You’re looking for clarity, and that’s exactly what we’re here to provide. You deserve to feel certain that your coverage will be there when you need it most.
This guide provides a clear 2026 checklist to help you filter out the noise and protect your access to preferred doctors. You’ll learn how to evaluate 40+ carrier options and identify the specific red flags that lead to future regret. We’ll show you how to keep your costs predictable, moving you from a state of uncertainty to total peace of mind.
Key Takeaways
- Understand how 2026 drug plan restructures and network shifts could impact your wallet and your access to care.
- Learn the critical differences between Medigap and Medicare Advantage so you don’t get locked into a plan that limits your choice of doctors.
- Discover the essential 2026 checklist for avoiding medicare buyer’s remorse by verifying your specific doctors and medication tiers.
- Identify why working with an independent broker who compares 40+ carriers is safer than using a captive agent with limited options.
- Gain the confidence to choose a plan that offers predictable costs and long-term security for your health journey.
What Is Medicare Buyer’s Remorse and Why Does It Happen in 2026?
Imagine the sinking feeling of standing at the pharmacy counter only to realize your life-saving medication isn’t covered. Or perhaps you call your specialist for a check-up and find out they no longer accept your plan. This is Medicare buyer’s remorse. It’s the painful realization that the plan you chose limits your care or costs much more than you expected. In 2026, this feeling is becoming more common as people struggle to keep up with major industry shifts and aggressive marketing.
The emotional toll of “choice overload” is real. Your mailbox is likely overflowing with glossy flyers, and the TV ads never seem to stop. It’s exhausting to filter through the noise. This pressure often leads to a “temporary mistake,” like overpaying for a month or two. However, it can also lead to a “permanent coverage trap.” If you leave a Medigap plan for a Medicare Advantage option and later want to return, you might face health questions that prevent you from getting that flexible coverage back. You deserve a path that leads to certainty, not a dead end.
The Hidden Costs of a Hasty Decision
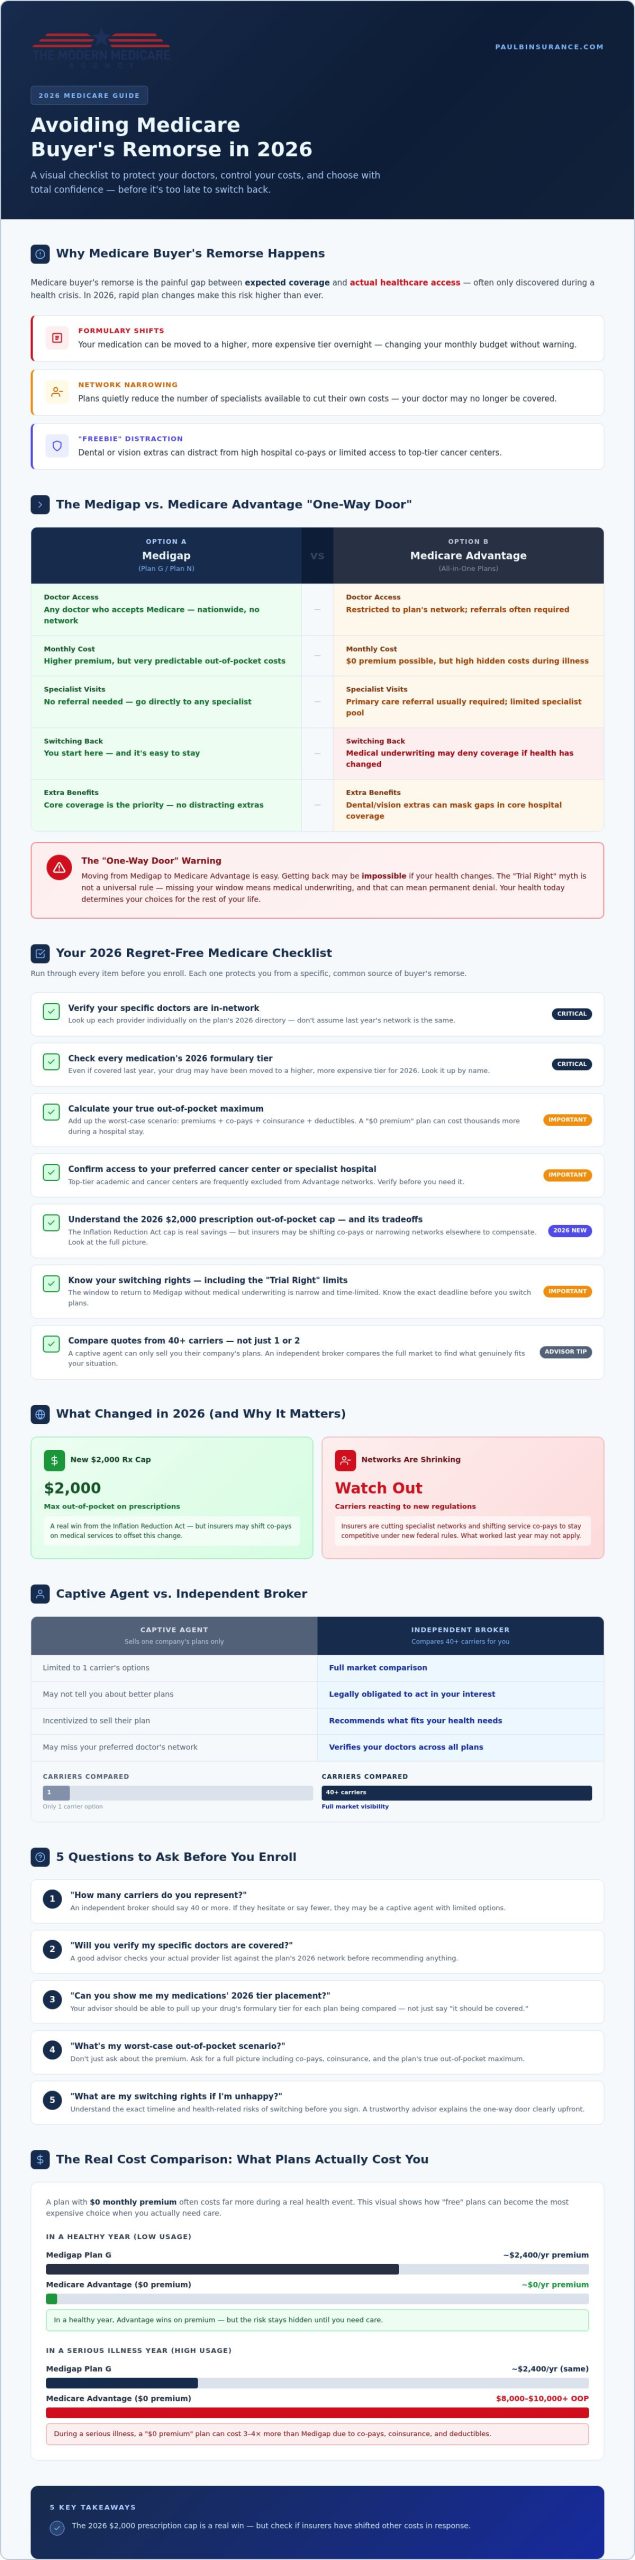
It’s easy to be tempted by plans with no monthly premiums. They look like a bargain on the surface. However, these plans often hide high out-of-pocket costs that only appear during a health crisis. Consider these factors for 2026:
- Formulary Shifts: Your specific medication could be moved to a higher, more expensive tier, changing your monthly budget overnight.
- Network Narrowing: Plans may reduce the number of specialists you can see to keep their own costs down.
- Core Coverage: Don’t let dental or vision “extras” distract you from high hospital co-pays or limited access to top-tier cancer centers.
Avoiding medicare buyer’s remorse requires looking beyond the “freebies” to ensure your doctors and prescriptions are truly protected. We’ve seen many people focus on the small perks while missing the large gaps in their primary medical safety net.
Why the 2026 Landscape is More Complex
New federal regulations, specifically the full implementation of the Inflation Reduction Act, have completely changed the rules of the game this year. While the new $2,000 out-of-pocket cap on prescriptions is a major win for many, insurance companies are reacting to these changes by shifting their doctor networks or adjusting co-pays for other services. Relying on “what worked for my neighbor” is more dangerous than ever because plans are shifting so rapidly to stay competitive. Medicare buyer’s remorse is the gap between expected coverage and actual healthcare access. We are here to guide you through these changes so you can feel confident in your choice for the long term.
The Medigap vs. Medicare Advantage ‘One-Way Door’
Choosing a plan isn’t just a yearly chore. It’s a long-term financial decision. Many people view Medicare as a flexible system where you can swap plans whenever you like. In reality, the choice between Medigap and Medicare Advantage is often a “one-way door.” While walking into an Advantage plan is easy, returning to Medicare Supplement Insurance later can be surprisingly difficult. This is a primary factor in avoiding medicare buyer’s remorse because the decisions you make in 2026 will echo for years to come.
The danger lies in the “Trial Right” myth. You might hear that you can try an Advantage plan for a year and switch back with no questions asked. While this is true in very specific cases, it’s not a universal rule. If you miss your window, most states allow insurance companies to use medical underwriting. This means they can look at your health history and deny you coverage if you’ve developed a chronic illness. Your health today truly dictates your choices for tomorrow.
Understanding Medigap’s Long-Term Stability
Medigap plans, such as Plan G or Plan N, are designed for those who value total freedom. There aren’t any networks to worry about. You can see any doctor in the United States who accepts Medicare. This predictability is why many seniors choose this path as they age. You won’t need a referral to see a specialist, and your out-of-pocket costs remain stable even if your health needs change. If you want to explore these options further, you can view our Medigap service page for a breakdown of 2026 benefits.
The Reality of Medicare Advantage Networks
Medicare Advantage plans often look attractive because of their low monthly premiums. However, they operate through managed networks. In 2026, we’re seeing more specialists and hospital systems leave these networks mid-year, which can leave you searching for new doctors in the middle of treatment. You also have to deal with “Prior Authorization.” This is when the insurance company must approve a procedure before you can receive care. This extra step often leads to delays and frustration when you’re already feeling unwell. Our Medicare Advantage guide can help you understand how to vet these networks effectively.
If you’re feeling unsure about which path is right for your future, it’s helpful to compare 2026 Medigap options with a guide who can explain the long-term impact of each choice.
Your 2026 Checklist for a Regret-Free Medicare Choice
Feeling confident about your coverage starts with a plan. We’ve seen many people rush into a decision because a deadline is looming, only to realize later they missed a critical detail. Avoiding medicare buyer’s remorse is much easier when you have a structured way to filter through the noise. This checklist is designed to help you move from a state of confusion to a place of total certainty.
Before you sign any enrollment forms for 2026, make sure you can check off these four essential items:
- The Doctor Confirmation: Verify that every one of your primary doctors and specialists is participating in the specific 2026 network you are considering.
- The Medication Tier Review: Confirm how your specific prescriptions are classified. A drug that was affordable last year might have moved to a more expensive tier.
- The Total Cost Calculation: Look beyond the monthly premium. Add up your expected co-pays, deductibles, and the maximum out-of-pocket limit to see the true price of the plan.
- The Travel Test: If you plan to spend time in another state or travel frequently, ensure your plan offers the portability you need to see a doctor anywhere in the country.
Doctor and Hospital Verification
Don’t rely solely on the printed or online directories provided by insurance companies. These lists can be outdated the moment they are published. Instead, call your doctor’s billing office directly. Ask them if they are specifically contracted with the 2026 version of the plan you want. You should also check if your preferred hospital is considered a “Tier 1” or “Tier 2” facility. Some plans charge significantly more if you use a Tier 2 hospital, even if it is technically “in-network.” If you have specialists, ask if the plan requires a new referral every time you need an appointment. These small hurdles can become major frustrations later.
The 2026 Medication Audit
The way drug plans are structured has changed significantly this year. Use the 2026 plan finder tool to enter your exact dosages and preferred pharmacy. This is the only way to see an accurate estimate of your annual costs. Pay close attention to “Step Therapy” requirements. This is a common practice where the insurance company requires you to try a less expensive medication before they will cover the one your doctor actually prescribed. For a deeper look at how these rules work, our Medicare Part D guide explains the 2026 changes in simple terms. Taking these steps now ensures you won’t face a “pharmacy counter surprise” next January.
Vetting Your Advisor: Questions to Ask Before You Enroll
The person you choose to guide you through the Medicare process is just as important as the plan you eventually pick. Many people don’t realize that not all advisors have the same goals or tools. If you want to be successful in avoiding medicare buyer’s remorse, you must ensure your advisor is working for you, not for a specific insurance company. A true expert acts as a shield against the high-pressure tactics often found in the 2026 insurance market.
Captive Agents vs. Independent Brokers
A “captive agent” is someone who works for only one insurance company. Because they are restricted, they can only offer you a “one-size-fits-all” approach from their specific carrier. If that carrier’s network changes or their 2026 drug prices spike, the captive agent has no other options to show you. In contrast, an independent broker works with many different companies. This independence allows them to pivot your coverage as your health needs or the market shifts. For a deeper look at why this choice matters, read our Medicare Broker guide to finding a trusted partner.
Before you commit to an enrollment, ask these four specific questions to vet your advisor:
- How many different insurance carriers do you represent? You should look for someone who has access to at least 30 or 40+ carriers to ensure a truly unbiased comparison.
- How do you determine which plan is best for my specific health needs? They should ask for your specific medications and doctor list before making any recommendations.
- Will you help me if I have a billing or claims issue in six months? Many agents disappear after the sale, but you need someone who provides support year-round.
- Are you an independent professional or do you work for a single insurance brand? This helps you understand if their advice is restricted or autonomous.
Looking for Year-Round Support
Medicare is not a “set it and forget it” product. Because plans change their rules and networks every January, you need a partner who is committed to the long haul. A dedicated advisor will reach out to you every October to perform an annual review of your coverage. This ensures that the plan you loved last year still makes sense for the upcoming year. A true advisor should prioritize your peace of mind and long-term security over a quick enrollment. They are there to protect you from the systemic confusion of the healthcare industry. If you want an advocate who compares the entire market for you, contact our team today for a personalized review of your 2026 options.
Finding Certainty: How The Modern Medicare Agency Protects Your Future
Paul Barrett and the team at The Modern Medicare Agency believe that no one should have to face the 2026 healthcare landscape alone. We act as calm, patient guides who take the stress out of a complex and often overwhelming system. Our independent status is our greatest strength. Because we have access to over 40 insurance carriers, we can shop the entire market on your behalf. This ensures that you aren’t stuck with a plan that doesn’t fit just because it was the only one a restricted agent could sell. Our mission is built around simplicity and clarity for every client we serve.
Our roots are in Melville, NY, but our reach extends to over 34 states. This national expertise, combined with a personal touch, allows us to provide high-level guidance with the care of a local professional. We make a “no-pressure” promise to every person who calls us. We believe in education first. Our goal is to provide the facts so you feel empowered to choose the coverage that truly meets your needs. Avoiding medicare buyer’s remorse is about more than just picking a plan; it’s about building a relationship with an expert you can trust to protect your interests.
Our Personalized Comparison Process
We’ve developed a methodical process to help you find clarity in a sea of options. We take your specific list of doctors and your current medications and run them through our analysis tools. This allows us to see exactly how different plans will perform for you in 2026. We take the “alphabet soup” of Medicare and translate it into clear, straightforward terms. You won’t have to worry about industry jargon or hidden rules. We show you the direct benefits and potential risks of each option, helping you move from a state of uncertainty to one of total peace of mind.
Your Next Steps to Peace of Mind
Securing your healthcare future doesn’t have to be a difficult journey. We invite you to book a simple, no-obligation consultation with our team to review your specific situation. The best time to prevent future regret is before the 2026 deadlines arrive. We can help you review Medicare Part D plans or determine if a supplement is the better path for your long-term health. By engaging with an independent expert now, you are taking the most important step toward a secure and predictable healthcare experience. We are here to serve and protect your future.
Take Control of Your 2026 Healthcare Journey
You now have the tools to move from a state of confusion to one of total certainty. Remember that avoiding medicare buyer’s remorse starts with looking beyond the flashy advertisements and focusing on your specific needs. By verifying your doctor networks and auditing your medications for the 2026 plan year, you protect yourself from expensive surprises. This isn’t just about picking a plan for today; it’s about ensuring your coverage remains stable as you age.
You don’t have to handle this complex process alone. Our team provides independent guidance from 40+ carriers and year-round support for all our clients. We are licensed in over 34 states and are dedicated to making this transition simple and clear. We prioritize your peace of mind over high-pressure tactics, acting as your advocate in a shifting market. You deserve a healthcare partner who stays with you long after the enrollment forms are signed.
Get your personalized 2026 Medicare plan comparison today; contact The Modern Medicare Agency.
We are ready to help you find the security and predictable costs you’ve been looking for. Your path to a regret-free Medicare choice starts with one simple conversation. We look forward to helping you protect your health and your future.
Frequently Asked Questions
Can I change my Medicare plan if I regret my choice later?
You can change your plan during specific times like the Annual Enrollment Period or the Medicare Advantage Open Enrollment Period. However, switching from an Advantage plan back to Medigap is often difficult because you may have to pass health checks. This is a major factor in avoiding medicare buyer’s remorse. It’s much safer to pick the right plan the first time than to hope for a smooth transition later.
What is the most common reason for Medicare buyer’s remorse in 2026?
The most common reason for regret is discovering that a doctor or hospital is no longer in the plan’s network. In 2026, many insurance carriers are narrowing their networks to keep costs down. You might also find that your medications have moved to a more expensive tier. These surprises happen when people choose a plan based on a TV ad rather than a personalized review of their specific needs.
How do I know if my doctor will still be in my network in 2026?
You should call your doctor’s office directly to ask if they accept the 2026 version of the plan you want. Online directories can be inaccurate or outdated. Ask the billing department specifically about the plan name and the carrier. This is the only way to be certain that you won’t be hit with out-of-network charges. We recommend doing this for every specialist you see regularly.
Is a $0 premium Medicare Advantage plan always the best deal?
A $0 premium plan isn’t always the best deal because it often comes with higher out-of-pocket costs. You won’t pay a monthly bill, but you might pay more every time you see a doctor or go to the hospital. These costs can add up quickly if you have a chronic condition. It’s important to look at the maximum out-of-pocket limit to understand your true financial risk for the year.
What happens if I choose a plan that doesn’t cover my medications?
If your plan doesn’t cover a medication, you’ll likely have to pay the full retail price. You can work with your doctor to request a “formulary exception” or switch to a similar drug that is covered. In 2026, the $2,000 cap on drug costs provides some protection, but it only applies to medications that are on your plan’s approved list. Checking your prescriptions beforehand is essential for your peace of mind.
Do I need to undergo a medical exam to switch from Advantage to Medigap?
You don’t usually need a physical exam, but you will likely have to answer a series of health questions. This process is called medical underwriting. In 2026, insurance companies can use your health history to charge you more or deny you a Medigap plan entirely. This applies unless you are in your initial enrollment period or have a specific “guaranteed issue” right. It makes your first choice very important.
How much does it cost to work with an independent Medicare broker?
It costs you nothing to work with an independent broker. We’re paid directly by the insurance carriers we represent. This allows The Modern Medicare Agency to offer unbiased advice and compare over 40 different carriers at no cost to you. You receive personalized research, help with the enrollment paperwork, and year-round support. We prioritize your needs over any single company, acting as your personal advocate in a complex system.
What is the 2026 out-of-pocket maximum for prescription drugs?
The out-of-pocket maximum for covered prescription drugs in 2026 is $2,000. This is a result of the Inflation Reduction Act. Once you reach this limit, you won’t pay any more for your medications for the rest of the calendar year. It’s a significant improvement for anyone with high drug costs. Just remember that this only applies to drugs that are on your specific plan’s formulary or approved list.
Article by
Paul Barrett
Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.
He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.
📞 631-358-5793 | paulbinsurance.com