Finding a Medicare Advisor Near You for Enrollment Help

Finding a Medicare Advisor Near You for Enrollment Help

Your ZIP code can help you find a licensed Medicare agent familiar with plans in your area. Finding a Medicare advisor near me can also begin with your state’s State Health Insurance Assistance Program (SHIP), which provides local, one-on-one Medicare counseling at no cost. These are different kinds of help, and understanding the difference can help you choose what suits your needs.

Medicare choices can feel overwhelming when costs, coverage, and provider networks all matter. Learn how agents and brokers work, how their services differ from SHIP counseling, and how to find local enrollment help. You’ll also find practical ways to compare advisors, so you can ask informed questions and move forward with confidence.

Key Takeaways

  • Use your ZIP code to focus your search on licensed Medicare enrollment help familiar with plans in your area.
  • Understand how an agent’s or broker’s plan options and payment arrangement may shape the guidance they provide.
  • Compare independent brokers, captive agents, call centers, and SHIP counselors to find the kind of support that fits your needs.
  • Prepare questions about coverage, costs, medications, and provider networks before reviewing plan recommendations.
  • Learn what information to have ready and what steps can make enrollment assistance more useful.

How can I find the best Medicare Advisor near me?

In 2026, begin with your ZIP code and compare advisors who serve your area. Look at licensing, carrier affiliations, and whether their explanations match your needs.

According to the Centers for Medicare & Medicaid Services (CMS), people turning 65 become eligible for Medicare enrollment. If that applies to you, make a short list of questions about coverage, doctors, prescriptions, and enrollment before contacting an advisor. Using the same questions in each conversation makes it easier to compare the answers you receive.

Review each advisor’s carrier affiliations. Ask whether they represent one insurance company or can compare plans from multiple carriers, and which options they can review for your ZIP code. Affiliations shape the plans an advisor can present, so pay attention to how clearly they explain the choices available to you.

Local knowledge can help you assess whether a plan suits the care you use. Make a list of your doctors, preferred hospitals, and regular prescriptions, then ask how the advisor will account for them. For example, if you see a specialist in Manhattan, ask how the comparison considers that provider and where you usually receive care.

In New York City and Long Island, narrow your search by ZIP code and the communities where you receive care. A borough or town name alone won’t show whether your providers participate in a plan’s network. If you receive care in both Queens and Nassau County, mention both locations so the discussion reflects your routine.

SHIP, your State Health Insurance Assistance Program, is another source of Medicare counseling. It provides local, one-on-one counseling at no cost. Counselors can help you review coverage, compare costs, and understand provider networks. In 2026, you can use SHIP counseling to clarify questions before making a plan decision with an insurance advisor.

Connecting With a Local Medicare Expert

To connect with a local advisor, search by ZIP code and arrange a conversation about your care priorities. Share your doctors, hospitals, prescriptions, and preferred way to receive care. Ask which carriers the advisor represents and how that affects the plans they discuss. A useful conversation explains why each option may fit, rather than offering only a plan name.

Advisor Licensing and Information Risks

Before sharing Medicare details, ask for the advisor’s full name and license information, then verify them through your state insurance department. An unlicensed advisor may not be authorized to discuss insurance plans in your state. Protect your Medicare number and other personal information: share it only when you understand who is requesting it and why.

How Do Medicare Agents or Medicare Insurance Brokers Work?

In 2026, an agent or broker can help you make sense of private Medicare plan choices. The process should connect your priorities to specific plan details, not leave you with a list of names.

A useful planning conversation starts with what matters most to you. Bring your medication list, preferred pharmacy, doctors, and questions about your care. The advisor can use these details to compare coverage and explain trade-offs. If you receive a comparison, look for clear information about benefits, provider access, and prescription coverage, along with an explanation of why each option is included.

The number of plans worth reviewing depends on your location and needs. The process may include reviewing 10 plans if that many need consideration. Rather than focus on the longest list, ask the advisor to explain which differences could affect your decision. For example, a plan with a preferred doctor in its network may matter more to you than a feature you won’t use.

Medicare plan types serve different needs. Medicare Advantage plans provide coverage through private plans, while Medicare Supplement, also called Medigap, helps with certain costs under Original Medicare. Part D plans provide prescription drug coverage. Ask the advisor to distinguish these options in the context of your current coverage. A Medicare Advantage plan guide can help you prepare focused questions.

Ongoing Support and Plan Updates

Plan details can change from year to year, so a recommendation needs to match the plan year you’re considering. Ask what support is available if your prescriptions, doctors, or care priorities change. For 2026, keep the comparison and any plan documents together, so you can refer to the specific coverage details discussed during your review.

Broker, Agent, and SHIP Counselor Roles

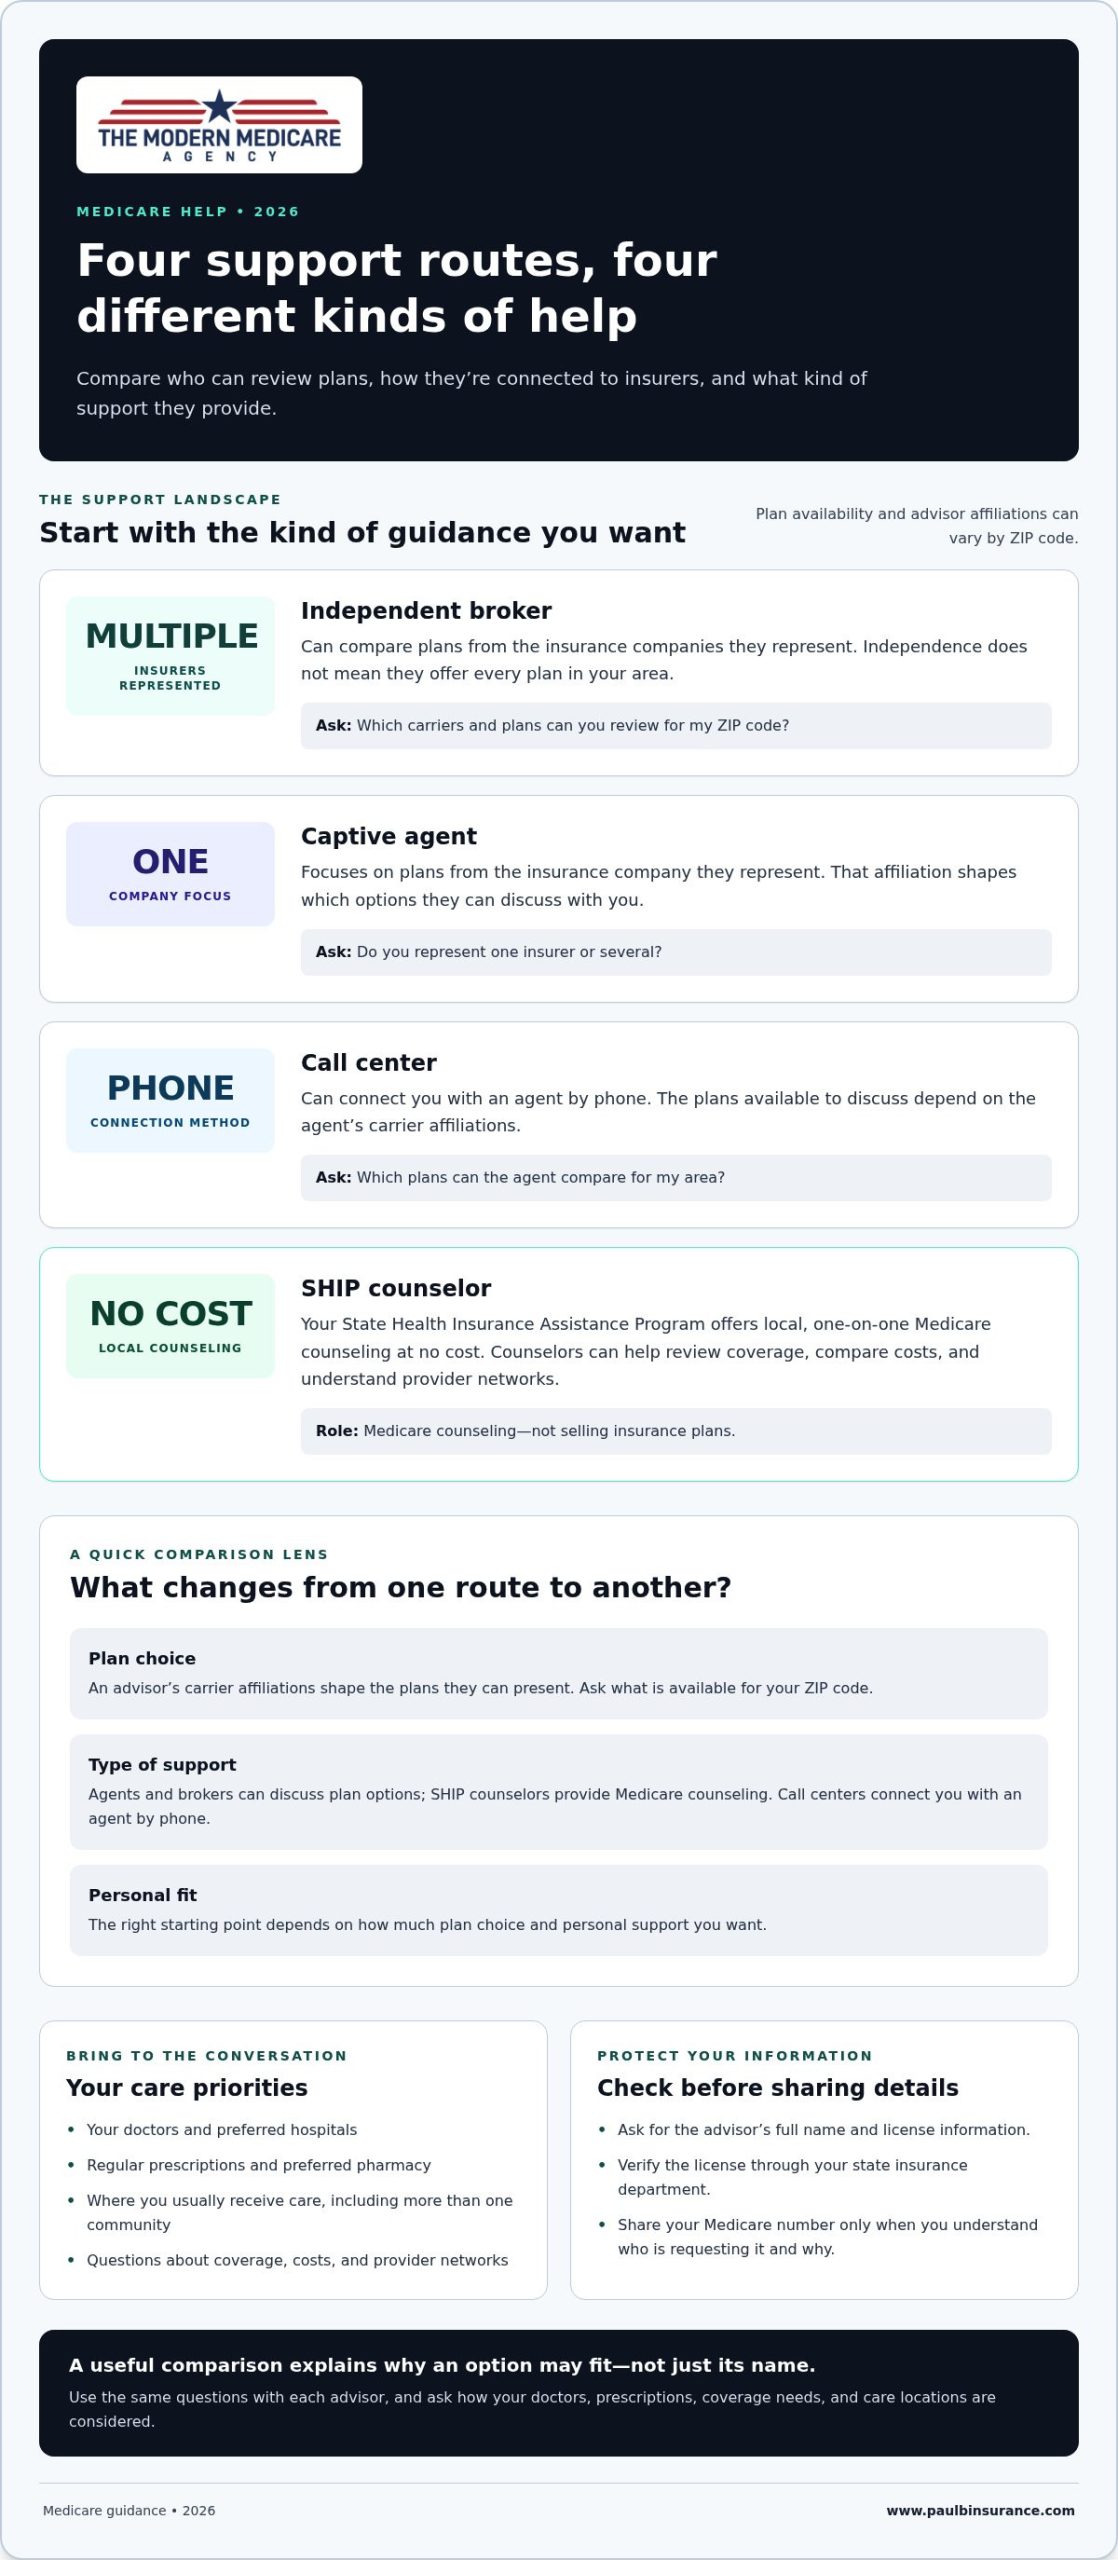
A broker compares plans from insurance companies they represent; an agent may represent one or several insurers. Insurance companies pay brokers when clients enroll. A SHIP counselor provides Medicare counseling rather than selling insurance plans. Choose the kind of help you need, whether that’s plan recommendations, enrollment guidance, or counseling.

Before deciding, ask the advisor to explain how each option matches your priorities and what trade-offs remain. Take time to consider the comparison. A clear discussion should leave you able to explain why a plan may fit, which details matter most, and what questions you still need answered.

Independent brokers versus captive agents and call centers

In 2026, the right place to start depends on how much choice and personal support you want. Independent brokers may compare plans from multiple insurers, while captive agents focus on plans from the company they represent. Call centers can connect you with an agent by phone. Each route can help, but the range of plans and kind of conversation may differ.

Before booking, ask which plans the advisor can compare for your ZIP code, whether they represent one insurer or several, and how they’ll explain differences among the available options. A broker’s independence describes their relationship with insurers; it doesn’t mean they represent every plan in your area. Carrier affiliations still shape which options they can discuss.

Search using your home ZIP code and note the names of agents and agencies that appear. If results are limited, try a nearby city or county, then ask whether the agent serves your community. Location matters because plan choices can vary by area. If you receive care in multiple places, note them before comparing options.

For a city search, enter a specific place name, such as Brooklyn or Hempstead, and compare the results with your ZIP-code search. An agency may serve a wider area than its office location suggests, while a nearby listing may not reflect plans available at your address. Ask how the agent will tailor the conversation to your location and care needs.

Searching by state can broaden your results, especially if your town has few listings. Look for agents licensed in your state and use the state insurance department’s lookup tool to review their license information. Ask for the agent’s full name and license number so you can match the listing. If you live near a state border, verify that the agent is licensed in the state where you need help.

Choose an agent when you want to discuss insurance plans and enrollment options. If you prefer a phone conversation, you can use a call center, but ask which agency or insurer the representative works with. SHIP is a separate option for unbiased Medicare counseling. It can help you understand your questions before you decide whether to speak with an agent.

Keep a simple comparison note for each contact: ZIP codes served, carrier affiliations, license details, and whether the conversation addressed your priorities. In 2026, this record can help you compare support without relying on a polished website or a broad claim about local expertise. If an answer is unclear, ask for a plain explanation before sharing personal information or making a decision.

Medicare enrollment assistance

Enrollment help can clarify which steps belong to you and which involve an advisor. In 2026, separate plan comparisons from enrollment in Original Medicare, so each part of your decision has a clear path.

Before enrolling, ask a Medicare advisor: Which plans can you compare, and which insurers do you represent? How will my doctors, prescriptions, and coverage needs affect your recommendation? Ask who completes the application, what information it requires, and how you’ll receive confirmation.

An advisor can review plan choices and explain how coverage differs. Bring your current insurance details, medication list, preferred doctors, and questions about costs. Ask for a side-by-side explanation of options suited to your needs. Before proceeding, make sure you understand the plan’s provider network, prescription coverage, and any trade-offs that matter to you.

Enrollment assistance depends on which Medicare coverage step you need. The Social Security Administration handles enrollment in Medicare Part A and/or Part B. A licensed insurance agent or broker can help compare private Medicare plan options. Keep these roles distinct, especially if you’re changing existing coverage or enrolling for the first time.

For unbiased counseling, contact your state’s State Health Insurance Assistance Program, or SHIP. SHIP counselors can help review coverage, costs, and provider networks. Every Open Enrollment season, SHIPs help thousands of people understand their options and make informed decisions. This no-cost counseling can be a helpful starting point before you speak with an insurance advisor.

During Open Enrollment, prepare an updated list of doctors, medications, and care priorities before reviewing plan choices. Ask whether each plan still covers the providers and prescriptions you rely on. Changes in your health needs or preferred pharmacy may affect which details deserve closer attention. Keep notes from each conversation so you can compare explanations.

If you live in California, the California Department on Aging can provide a complete list of HICAP offices by phone at 1-800-4334-0222. HICAP is California’s SHIP counseling program. People who need general Medicare information can also call Medicare at 1-800-633-4227. Use the contact that matches your question, then keep any guidance and enrollment records together.

Before submitting an application, review the plan name, coverage start information, and details you provided. Ask the advisor to explain anything unclear, and keep a copy of your submission or confirmation. A careful final review helps you understand what you selected and what to expect next.
Finding a Medicare Advisor Near You for Enrollment Help

Finding licensed Medicare brokers by ZIP code

A ZIP code is a practical starting point, not a complete recommendation. It helps focus your search on brokers who may serve your area and plans relevant to your location. For a 2026 comparison, use your home ZIP code first. If you receive care in another community, note that location too.

Start by searching for Medicare brokers in your ZIP code. Record each broker’s name, agency, contact details, and stated carrier affiliations. Then look up the broker using your state insurance department’s license search. Match the name and license details, and make sure the state information corresponds to where you live.

Next, ask whether the broker compares plans from multiple insurance companies. An independent broker may present options across carriers, while a captive agent may focus on one insurer. The agency name alone doesn’t tell you which plans the individual can discuss. Ask which companies they represent and whether they compare Medicare Advantage, Medicare Supplement, or Part D plans.

ZIP code results can be too broad or too narrow. If your search returns few names, try a nearby city or county, then confirm the broker serves your location. If you split your time between homes, share both ZIP codes and explain where you receive care. This gives the conversation a clear geographic starting point.

Before contacting an agency, prepare a short comparison sheet with your ZIP code, doctors, preferred hospitals, prescriptions, and the type of Medicare help you need. Ask each broker to explain how the plans they can discuss address those priorities. Record which carriers they represent, what they can compare, and what follow-up support they offer.

  • Search: Use your home ZIP code and a nearby city name.
  • Record: Note each broker’s name, agency, and carrier affiliations.
  • Verify: Match the broker’s details through your state insurance department.
  • Compare: Ask which plans and insurance companies they can discuss.

A ZIP code search can also lead to a discussion of Medicare Supplement, or Medigap, plans. Ask how the available options fit with your existing Medicare coverage and healthcare priorities. The broker should explain the comparison clearly, including which details depend on your location.

Once you have a verified broker and a focused list of questions, you can decide whether to schedule a conversation. For background before discussing Medigap, review Medicare Supplement coverage options and note what you want clarified.

The Modern Medicare Agency: Medicare Advantage Plans

The Modern Medicare Agency helps people compare Medicare Advantage, Medicare Supplement (Medigap), and Part D plans from multiple insurance carriers. If you’re weighing Medicare Advantage against other coverage, an advisor can explain the differences and help you consider how each option fits your needs. Recommendations are based on your circumstances.

Bring your questions about doctors, prescriptions, and coverage to a free Medicare consultation by phone or Zoom. The Modern Medicare Agency offers personalized plan comparisons, enrollment assistance, and year-round support. When you’re ready to discuss your options, schedule a free consultation.

Make Your Next Medicare Decision With Confidence

Your next step is to turn what you’ve learned into a clear personal checklist. Write down the care priorities you want a plan to meet, the questions you still have, and what would make you comfortable moving forward. That preparation can make a conversation with an advisor more focused and useful, especially as you consider coverage for 2026.

If you’re finding a Medicare advisor near me, the goal isn’t simply to choose the closest name. Look for guidance that helps you understand your options and make a decision suited to your needs. The Modern Medicare Agency can help you compare Medicare Advantage, Medicare Supplement (Medigap), and Medicare Part D plans.

If you’re ready to talk through your options, contact The Modern Medicare Agency. Take the process one question at a time. You can move forward with greater clarity and confidence.

Frequently Asked Questions

How does enrollment work?

Medicare enrollment begins with identifying which coverage you need and who handles that step. The Social Security Administration handles enrollment in Medicare Part A and/or Part B. After that, you can review private plan options if you want additional coverage. Keep copies of applications and confirmation notices, and note the coverage start information so you know when your selected plan takes effect.

How does the Medicare planning process work?

Medicare planning starts with your current coverage and the care you expect to use in 2026. Gather a list of medications, preferred pharmacies, doctors, and upcoming care needs. Then compare how potential plans address those priorities, including provider access and prescription coverage. A written comparison can help you discuss trade-offs with a spouse or caregiver before making a choice.

How does this service work?

The Modern Medicare Agency’s process begins with a free consultation, by phone or Zoom, to understand your needs. The agency reviews your situation, compares Medicare Advantage, Medigap, and Part D options, then presents the top 2-3 best options. If you choose a plan, enrollment assistance includes paperwork handling. The agency also provides year-round support for claims, billing, and plan changes.

Need help beyond what’s on Medicare.gov?

Yes. Medicare.gov provides official program information, while personal support can help you apply it to your situation. You might need help organizing questions about a prescription, a doctor, or a plan’s coverage details. A broker can discuss available insurance plans, while SHIP provides unbiased Medicare counseling to help you understand your choices.

What’s the benefit of speaking with a local Medicare agent?

A local agent can discuss plan availability and care networks relevant to your location. That matters if you receive care in several nearby communities or rely on a particular hospital system. Bring specific provider and pharmacy names rather than asking only whether a plan is “good.” This keeps the discussion practical and focused on the care you use.

How do I find a licensed Medicare advisor near me?

Start with your ZIP code and collect the advisor’s full name, agency, and license details. Use your state insurance department’s lookup tool to match the person and review their license status. Then ask which insurance companies they represent and whether they can discuss plans for your location. These steps help you focus on a licensed advisor whose plan access suits your needs.

Do Medicare advisors charge fees, and how are they paid?

Medicare brokers are paid by insurance companies when a client enrolls, rather than charging consumers directly for the broker’s plan-selection help. The Modern Medicare Agency offers its initial Medicare consultation free. A plan’s own costs are separate from an advisor’s compensation, so keep the two questions distinct: ask how the advisor is paid, then review the plan’s premiums and other cost details for 2026.

Can Medicare agents recommend all plans in my area or only certain insurers?

Agents can discuss plans offered by the insurance companies they represent, so one agent may not cover every insurer in your area. Independent brokers can compare plans from multiple companies, though their carrier affiliations still shape the choices available. Ask which insurers they represent and which plans they can review for your ZIP code. This gives you a clearer picture of the comparison.
Paul Barrett

Article by

Paul Barrett

Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.

He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.

📞 631-358-5793 | paulbinsurance.com
What Is Medicare Part B and What Does It Actually Cover?

The complete guide to Medicare’s medical insurance — every service it covers, exactly what it costs in 2026, how it works with group insurance and VA benefits, and the excess charges most people have never heard of until they get a surprise bill.

The Short Answer

Medicare Part B is medical insurance — it covers doctor visits, outpatient care, preventive services, durable medical equipment, and more. Unlike Part A, Part B is not premium-free for anyone: everyone pays a monthly premium (202.90in2026formostpeople),anannualdeductible(283), and 20% coinsurance on most covered services, with no yearly cap on that 20% under Original Medicare alone. Whether you need to enroll at 65, and whether delaying is safe, depends heavily on your employment status and your employer’s size — getting this wrong is one of the most consequential and permanent mistakes in all of Medicare.

Key Takeaways

  • Part B is never premium-free — everyone pays a monthly premium, and higher earners pay significantly more through IRMAA.
  • The 20% coinsurance under Original Medicare alone has no yearly cap — this is the single biggest financial risk in Medicare, and it’s the reason Medigap and Medicare Advantage exist.
  • Whether you can safely delay Part B without a penalty depends on your employer’s size: 20+ employees generally allows delay; fewer than 20 generally does not.
  • Missing your enrollment window triggers a permanent 10% penalty for every 12-month period you went without coverage.
  • Veterans can and generally should enroll in Part B even with VA benefits, since Medicare and VA coverage don’t coordinate — each only pays for care received within its own system.
  • “Excess charges” from non-participating providers can add up to 15% on top of what Medicare approves, and only some Medigap plans protect you from them.

What Part B Actually Covers

While Part A handles hospital room and board, Part B is the half of Original Medicare that covers medical care and most services delivered outside a hospital admission — doctor visits, outpatient procedures, and ongoing medical needs.

What’s covered

  • Doctor visits — primary care and specialists
  • Outpatient surgeries and procedures
  • Diagnostic lab work, X-rays, and MRIs
  • Emergency room visits
  • Ambulance services
  • Outpatient mental health care
  • Physical, occupational, and speech therapy
  • Chemotherapy and radiation received in an outpatient clinic
  • Durable Medical Equipment (DME) — wheelchairs, oxygen equipment, blood sugar monitors, walkers, and similar equipment
  • Ambulatory surgical center services

Preventive services: the part Medicare gets genuinely right

Most preventive services are covered at 100%, with no deductible and no copay, as long as your provider accepts Medicare assignment. This includes:

  • Your one-time “Welcome to Medicare” wellness visit, available within your first 12 months on Part B
  • Annual wellness visits after that
  • Flu shots and most other recommended vaccines
  • Mammograms
  • Colonoscopies and other cancer screenings
  • Diabetes and cardiovascular screenings
  • Many other screenings recommended by the U.S. Preventive Services Task Force

Paul’s Honest Take: This is one of the most underused parts of Medicare, full stop. I’ve had clients who paid for a private physical every year out of habit and never realized their annual wellness visit through Medicare was completely free. If you haven’t used your Welcome to Medicare visit or your annual wellness visit, that’s real value sitting on the table.

What’s NOT covered

  • Routine dental care — cleanings, fillings, dentures, extractions
  • Routine vision exams and eyeglasses
  • Hearing aids (though diagnostic hearing tests ordered by a doctor may be covered)
  • Long-term custodial nursing home care — help with daily living activities, as opposed to short-term skilled or medical care
  • Routine prescription drugs you pick up at a retail pharmacy — that’s Part D’s job, not Part B’s
  • Cosmetic surgery, unless medically necessary (such as reconstruction after an accident or mastectomy)
  • Most care received outside the United States, with very limited exceptions
  • Routine foot care, such as nail trimming, in the absence of a qualifying medical condition
  • Acupuncture, except for a narrow, specific chronic low back pain benefit
  • Concierge medicine fees and membership-style charges some practices add on top of standard care
  • Long-term care insurance-style services, including most home-based personal care that isn’t tied to a skilled medical need

Paul’s Honest Take: The dental and vision exclusions are the ones that surprise people most, especially since they’re such routine parts of healthcare for most adults. This is exactly why so many Medicare Advantage plans build dental, vision, and hearing benefits into their coverage — Original Medicare was simply never designed to include them, and that gap doesn’t go away on its own.

What Part B Costs in 2026

Part B has three separate cost components, and understanding all three matters:

Cost Component

2026 Amount

Standard monthly premium

$202.90

Annual deductible

$283

Coinsurance on most covered services

20%

The premium is deducted automatically from your Social Security check if you’re already collecting benefits. If you’re not yet collecting Social Security, you’ll receive a bill, typically every three months.

The deductible works differently than Part A’s — it’s a straightforward annual figure. You pay the first $283 of Medicare-approved outpatient costs each calendar year, and then Medicare’s cost-sharing kicks in.

The coinsurance is where the real risk lives. After your deductible is met, Medicare pays 80% of the Medicare-approved amount for most covered services, and you’re responsible for the remaining 20%. There is no yearly cap on this 20% under Original Medicare alone. If you have a $100,000 course of cancer treatment, your 20% share is $20,000 — unless you have a Medigap policy or Medicare Advantage plan absorbing that cost.

Paul’s Honest Take: I put this in bold because it’s genuinely the single most important number in this entire guide. That uncapped 20% is the whole reason Medigap and Medicare Advantage exist as products in the first place. Original Medicare by itself was never designed to protect you from a truly expensive year — it was designed to cover 80% of it and leave the rest to you.

IRMAA: What Higher Earners Actually Pay

If your income is above certain thresholds, you’ll pay more for Part B through the Income-Related Monthly Adjustment Amount (IRMAA) — based on your tax return from two years prior. For 2026, that means your 2024 income determines your premium tier.

2024 Income (Individual)

2024 Income (Married, Joint)

Total Part B / Month

$109,000 or less

$218,000 or less

$202.90

$109,001 – $137,000

$218,001 – $274,000

$284.10

$137,001 – $171,000

$274,001 – $342,000

$405.80

$171,001 – $205,000

$342,001 – $410,000

$527.50

$205,001 – $499,999

$410,001 – $749,999

$649.20

$500,000 and above

$750,000 and above

$689.90

At the top tier, you’re paying more than three times the standard premium. If your income has recently dropped — retirement, the loss of a spouse, or certain other life-changing events — you can appeal your IRMAA determination using Form SSA-44.

Do You Have to Enroll? And What Happens If You Don’t?

Technically, Part B is optional — Medicare won’t force you into it. But opting out without a valid alternative is genuinely risky, because of how the penalty structure works.

If you don’t sign up during your Initial Enrollment Period (the 7-month window around your 65th birthday) and you don’t have qualifying employer coverage, you’ll face a permanent 10% penalty added to your premium for every full 12-month period you went without Part B. That penalty doesn’t expire — you pay it for as long as you have Part B, which for most people means for the rest of your life.

Example: If you delayed enrollment by 24 full months without a valid exception, you’d pay an extra 20% on top of the standard $202.90 premium in 2026 — roughly $40.58 more, every month, permanently.

How Part B Works with Group Insurance

Just like Part A, whether you can safely delay Part B without penalty comes down to one specific number: how many employees your company has.

Companies with 20 or more employees: If you or your spouse are actively working and covered by a genuine group health plan, your workplace insurance is primary, and you can legally delay Part B without any penalty. When that employment or coverage eventually ends, you get an 8-month Special Enrollment Period to enroll in Part B penalty-free.

Companies with fewer than 20 employees: Medicare automatically becomes your primary insurer at 65, regardless of your employment status. You need to enroll in Part B right on schedule. If you don’t, your small employer’s plan can legally refuse to pay claims that Medicare should have covered first — potentially leaving you responsible for the full cost.

Paul’s Honest Take: I say this in nearly every guide I write, because it’s genuinely one of the costliest misunderstandings I encounter: “I have good coverage at work” and “I’m protected from Medicare’s enrollment deadlines” are two completely different statements, and whether the second one is true depends entirely on your employer’s size — not how generous the coverage feels. Confirm the actual employee count before you decide to delay anything.

Retiree Coverage Is Not the Same as Active Employer Coverage

This is a distinction that catches a genuinely large number of people off guard: the “20 or more employees” exception only applies to active employment. If you retire and your former employer offers you retiree health benefits — sometimes a genuinely good, comprehensive plan — that coverage does not create a Special Enrollment Period the way active group coverage does, and it does not exempt you from enrolling in Part B on time.

Paul’s Honest Take: I’ve seen this mistake more than once, and it’s an especially painful one because it happens to people who did everything right during their working years. Someone retires with a strong retiree health plan from a large employer, assumes it works the same way their active coverage did, and delays Part B — only to find out later that retiree coverage was never a valid reason to delay in the first place. The moment you stop actively working, that clock starts, regardless of how good your retiree plan looks on paper. If you’re retiring and keeping employer retiree benefits, treat enrolling in Part B as something to handle right on schedule, not something retiree coverage lets you postpone.

Why You Need Both Part A and Part B for Medigap or Medicare Advantage

Here’s a foundational requirement worth understanding clearly, since it shapes every other coverage decision in Medicare: you must be enrolled in both Part A and Part B before you can buy a Medigap policy or enroll in a Medicare Advantage plan. Neither product exists as a standalone substitute for Original Medicare — both are built specifically to work alongside it.

  • Medigap fills the cost-sharing gaps left by Original Medicare (Parts A and B) — it has nothing to fill in if you’re not enrolled in both parts to begin with.
  • Medicare Advantage legally must provide at least the same coverage as Parts A and B combined, which is only possible because you’re required to be enrolled in both before a Medicare Advantage carrier can enroll you.

Paul’s Honest Take: This surprises people who assume they can somehow “skip” Part B and go straight into a Medicare Advantage plan to avoid the extra premium. It doesn’t work that way — Part B enrollment, and its premium, is a prerequisite either way, whether you end up on Original Medicare with Medigap or on a Medicare Advantage plan. There’s no path through Medicare that avoids the Part B premium once you’re actually using the system.

Does Medicare Work If You’re a Veteran?

Yes — and if you have VA health benefits, understanding how the two systems relate is genuinely important, because they work differently than most people assume.

Medicare and VA benefits do not coordinate. These are two entirely separate systems that each pay only for care received within their own network. Medicare doesn’t pay for care you receive at a VA facility, and VA benefits don’t pay for care you receive from a non-VA doctor or hospital. You, the veteran, choose which system to use each time you seek care.

Here’s the critical point: having VA benefits does not exempt you from Medicare’s enrollment deadlines. VA coverage is not considered a qualifying reason to delay Part B without penalty. If you don’t enroll in Part B during your Initial Enrollment Period and you’re relying solely on VA benefits, you can still trigger the permanent late enrollment penalty.

Why the VA itself recommends enrolling in Medicare anyway:

  • It gives you access to civilian doctors and hospitals outside the VA system
  • VA healthcare funding depends on annual Congressional appropriations, which isn’t guaranteed to remain stable
  • If VA authorizes only part of your needed care at a non-VA facility, Medicare can help cover the rest
  • Having both gives you meaningfully more flexibility and security than relying on either system alone

Paul’s Honest Take: This is one of the most common misconceptions I run into with veterans specifically, and it’s an expensive one to get wrong. Good VA coverage feels like it should be enough, and it might genuinely handle most of your care — but it doesn’t protect you from the Part B enrollment clock the way employer coverage from a large company can. The VA itself actively encourages enrolling in Medicare Parts A and B for exactly this reason. If you have VA benefits and are approaching 65, this is worth a direct conversation before you assume you’re covered.

Veterans who enroll in Part B can also purchase a Medigap policy, which can be particularly valuable if you use non-VA providers regularly — though if you primarily rely on VA facilities for most of your care, the value of an added Medigap policy may be more limited, and worth weighing carefully.

How Long Does It Actually Take to Get Part B Approved?

This is one of the most practical, and most overlooked, pieces of planning — especially if you’re leaving a job after 65 and coordinating your Part B start date around the end of your employer coverage. Applying isn’t instant, and the timeline depends heavily on which enrollment window you’re using.

Enrollment Situation

Typical Processing Time

When Coverage Actually Starts

Initial Enrollment Period (around 65)

2–4 weeks, sometimes up to 6

1st of your birthday month (if applied in the 3 months before) or 1st of the month after you apply (if applied during or after your birthday month)

Special Enrollment Period (leaving employer coverage)

4–8 weeks, sometimes longer

1st of the month after your application is submitted

General Enrollment Period (Jan 1–Mar 31, missed window)

4–6 weeks

1st of the month after you apply

Why the Special Enrollment Period takes longer: applying after leaving employer coverage requires two forms, not one — Form CMS-40B (the actual Part B application) and Form CMS-L564 (Request for Employment Information), which your employer needs to complete to verify you had qualifying coverage. Social Security has to manually review both, which is exactly why this route consistently takes longer than a standard Initial Enrollment Period application.

Paul’s Honest Take: This timeline question comes up constantly with clients who are retiring or leaving a job after 65, and it deserves real attention — not just because of the penalty risk we’ve already covered, but because a slow approval can leave you with an actual gap in coverage if you time it too tightly. My standard advice: start this process at least 2 to 3 months before you need Part B to actually begin, not the week your employer coverage ends. If your former employer is slow to complete their portion of Form CMS-L564, that alone can hold up the entire application — so it’s worth following up with your HR or benefits department directly rather than assuming it’s been submitted.

Practical tips to avoid delays

  • Apply online through SSA.gov whenever possible. It’s consistently the fastest method — mailed or faxed forms are more prone to getting lost or delayed.
  • If you’re on a Special Enrollment Period, submit Form CMS-L564 alongside Form CMS-40B, not separately. They need to arrive together, and one incomplete form can stall the whole application.
  • Expect a short intake lag even with online applications. It can take several business days for an online submission to actually appear on a local Social Security agent’s screen — don’t panic if you call shortly after applying and they say they don’t see it yet.
  • Once approved, you don’t have to wait for your physical card. Your Medicare Beneficiary Identifier typically appears in your online Social Security or Medicare.gov account within a day or two of approval, and you can print a temporary card from there — the physical card generally arrives by mail within about 30 days.

Excess Charges: The Cost Almost Nobody Knows to Ask About

Here’s a detail that surprises even people who’ve been on Medicare for years: not every doctor who accepts Medicare agrees to accept Medicare’s approved amount as full payment.

Providers fall into three categories:

  • Participating providers accept Medicare assignment, meaning they agree to accept the Medicare-approved amount as payment in full. This covers the vast majority of providers — roughly 98% of doctors nationally.
  • Non-participating providers still accept Medicare patients but haven’t agreed to accept the standard rate. They can charge an excess charge of up to 15% above the Medicare-approved amount.
  • Opted-out providers have left the Medicare system entirely and can charge whatever they want under a private contract — Medicare pays nothing at all for care from these providers, except in emergencies.

How excess charges actually work: if the Medicare-approved amount for a service is $300 and you see a non-participating provider, they can legally charge up to an additional $45 (15%) on top, for a total bill of $345 — and that excess amount doesn’t count toward your Part B deductible.

Eight states currently prohibit or limit excess charges entirely: Connecticut, Massachusetts, Minnesota, New York, Ohio, Pennsylvania, Rhode Island, and Vermont. If you live in one of these states, you’re generally shielded from excess charges from providers within your state — though you could still face them if you receive care from a non-participating provider elsewhere.

Paul’s Honest Take: This is exactly why Medigap Plan G matters so much for people who want maximum flexibility. Plan G covers excess charges in full — Plan N does not. If you’re the kind of person who wants the freedom to see any doctor without worrying about billing surprises, that distinction is worth understanding clearly before you pick between the two. And regardless of which plan you choose, it’s always worth asking a new provider directly whether they accept Medicare assignment before your first appointment.

The HSA Rule: Part B Closes the Door Too

If you’re hoping to keep contributing to a Health Savings Account, know this clearly: enrolling in Part B — or any part of Medicare — ends your ability to make new HSA contributions. This isn’t unique to Part B; it applies the moment you enroll in Medicare in any form, including premium-free Part A.

If keeping your HSA active matters to you, the only way to legally delay both Part A and Part B is through qualifying employer coverage — which, as covered above, generally requires an employer with 20 or more employees. And because Part A enrollment can be backdated up to 6 months once you do enroll, it’s smart to stop HSA contributions 6 months before you plan to sign up for Medicare or file for Social Security, whichever comes first.

Frequently Asked Questions

Is there a cap on what I’ll pay for Part B services in a year? Not under Original Medicare alone — the 20% coinsurance has no yearly limit. A Medigap policy or Medicare Advantage plan is what actually caps your exposure.

What happens if I don’t sign up for Part B on time? You’ll generally face a permanent 10% penalty on your premium for every 12-month period you went without coverage, unless you qualify for a Special Enrollment Period through active employer coverage.

Do I need Part B if I have good coverage through a small employer? Almost certainly yes. If your employer has fewer than 20 employees, Medicare becomes your primary insurer at 65 regardless of your job coverage, and not enrolling can leave you exposed to unpaid claims and a lifelong penalty.

Do veterans need Medicare Part B if they have VA benefits? Generally, yes. Medicare and VA benefits don’t coordinate — each only pays for care within its own system — and VA coverage doesn’t exempt you from Medicare’s enrollment deadlines or penalties.

What is a Part B excess charge? An additional charge, up to 15% above the Medicare-approved amount, that a non-participating provider can legally bill you. It doesn’t count toward your deductible, and only Medigap Plan G (among current plans) covers it in full.

Can I keep contributing to my HSA if I enroll in Part B? No. Enrolling in any part of Medicare, including Part B, ends your HSA contribution eligibility going forward.

How long does it take to get approved for Part B? It depends on the enrollment window. Initial Enrollment Period applications typically process in 2–4 weeks. Special Enrollment Period applications, used when leaving employer coverage, generally take 4–8 weeks since Social Security must manually verify your prior coverage using Form CMS-L564. Start the process at least 2–3 months before you need coverage to begin, especially when coordinating around a job ending.

The Bottom Line

Part B is the half of Medicare that covers your everyday medical care — and it’s also where the real financial exposure of Original Medicare lives, thanks to that uncapped 20% coinsurance. Whether you should enroll at 65, whether you can safely delay, and how much of that exposure you’re carrying all depend on details specific to your situation: your employer’s size, your income, your VA status, and which doctors you actually see.

If you want help sorting out exactly how Part B applies to your specific circumstances — or want to understand how Medigap or Medicare Advantage could close that uncapped coinsurance gap — that’s exactly the conversation I have with clients every day, at no cost to you.

Call 631-358-5793 or visit paulbinsurance.com to set up a time to talk it through.

Paul Barrett, CMIP, is the founder of The Modern Medicare Agency, based in Melville, NY, and has spent 18+ years exclusively helping people navigate Medicare — never life insurance, never annuities, just Medicare. He’s licensed in 37 states, represents more than 40 carriers, and has personally helped over 5,000 clients choose coverage that actually fits their lives.

Figures current as of 2026 and sourced from CMS, Medicare.gov, and the Social Security Administration. Individual circumstances vary, especially around employer coverage, VA benefits, and income-based premiums — always verify your specific situation before making enrollment decisions.

Sources

Related Post

Scroll to Top