
Employer coverage can change when you need to enroll in Medicare Part B. If you or your spouse has coverage through current employment, your enrollment timing may differ, and delaying Part B without understanding the rules can lead to a penalty that lasts as long as you have Part B. The Initial Enrollment Period lasts seven months around your 65th birthday, so working with a trusted medicare advisor in Port Jefferson NY from The Modern Medicare Agency can help you understand which timing rules may apply to your situation.
It’s understandable to feel unsure about whether to keep employer coverage, enroll now, or wait. This guide explains how employer coverage affects Part B timing, which Initial, Special, and General Enrollment Periods may apply, and what to consider when choosing Medicare coverage. You’ll also learn how professional enrollment support can bring the steps into focus, so you can make your next decision with more clarity and confidence.
Key Takeaways
- Match your enrollment timing to your work and coverage situation so you can understand which Medicare period applies.
- The General Enrollment Period runs from January 1 through March 31, according to the Centers for Medicare & Medicaid Services.
- Review how Medicare coverage options differ before choosing what may fit your health care and prescription needs.
- Local enrollment guidance can help make plan choices and next steps easier to understand.
- The Modern Medicare Agency can help you compare Medicare Advantage, Medigap, and Part D plans when you’re ready to consider coverage options.
Employer coverage and delaying Part B
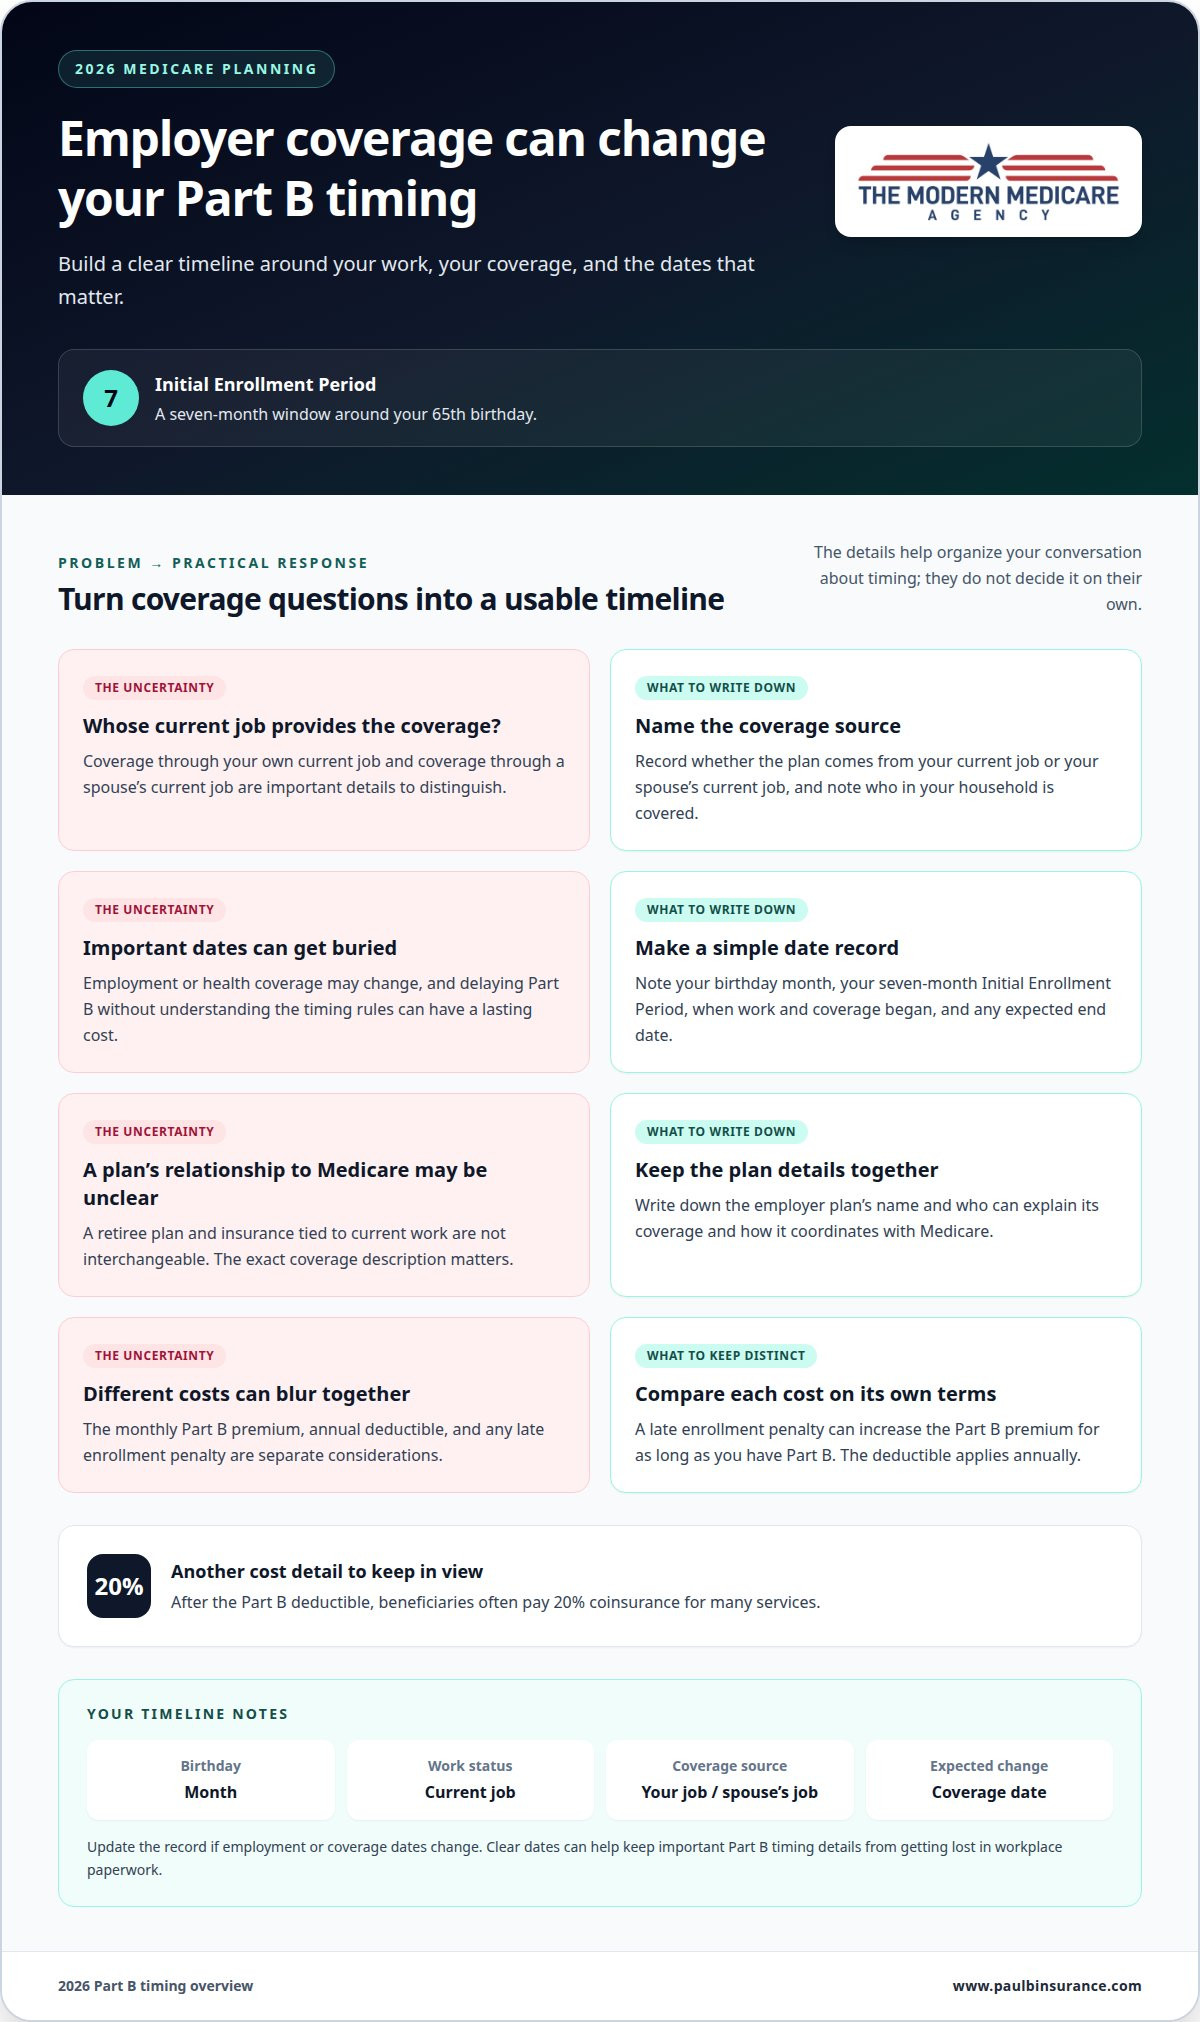
Still working at 65, or covered through a spouse’s job? Employer insurance can make Medicare timing feel less straightforward. The key is to understand your current coverage and the dates it may change before deciding when to enroll in Part B. The Medicare Initial Enrollment Period lasts seven months around your 65th birthday. That window gives you a starting point for organizing the decision.
Delaying Part B can have lasting consequences. A late enrollment penalty can increase your Part B premium for as long as you have Part B. That makes it important to understand timing before employer coverage ends or changes. These figures show why the decision deserves careful attention, but they do not determine your enrollment timing.
Start with a simple coverage timeline. Record your birthday month, your Initial Enrollment Period, and any known employment or coverage changes. Then gather the details about your current plan:
- Whether the insurance comes from your own current job or a spouse’s current job.
- When the employment and health coverage began, and any expected end date.
- Which people in your household are covered by the employer plan.
- Who can explain the plan’s coverage and how it coordinates with Medicare.
These details help organize the conversation about Part B timing. For example, someone approaching 65 while still working should note the employer plan’s name and the expected date of retirement. A spouse covered through that job should record the same dates. Clear dates make it easier to identify what needs attention before coverage changes. Avoid treating a retiree plan and insurance tied to current work as interchangeable; write down exactly how your coverage is described.
Consider the financial effect as well as the calendar. The Part B premium is monthly, while the deductible applies annually. A late enrollment penalty can affect the premium for as long as Part B remains in place. These are separate details, so keep them separate when weighing timing. After organizing the employer coverage question, consider plan choices as a distinct step. You can review Medicare plan options once the Part B timeline is clearer.
Before making a decision, note your birthday month, work status, coverage source, and expected coverage-change date. These details provide a practical starting point for discussing enrollment timing. If employment or coverage dates change, update the timeline. A clear record helps keep important Part B dates from getting lost among workplace insurance paperwork.
After the Part B deductible, beneficiaries often pay 20% coinsurance for many services.
Local insurance agency services
In Port Jefferson, local insurance guidance can help turn Medicare questions into clear next steps. Start by identifying the support you need, then consider an advisor’s service area, licensing, and compensation.
Advisor and Broker Availability
Port Jefferson residents can look for Medicare guidance from insurance agencies and brokers serving Suffolk County. Availability may include in-person or remote conversations, depending on the advisor. The right fit depends on whether you need help understanding enrollment timing, comparing coverage, or both. Port Jefferson’s ZIP code is 11777, a useful detail when discussing local plan options.
Do Medicare advisors in Port Jefferson charge fees or earn commissions? Compensation arrangements can differ, including commission-based arrangements. The Modern Medicare Agency offers a free Medicare consultation by phone or Zoom, so you can discuss your situation and understand your options before deciding how to proceed.
When comparing advisors, focus on how they explain choices, answer questions, and support the decision process. An independent broker may discuss options from multiple insurance carriers, while a representative tied to one company may have a narrower selection. The key is understanding the scope of the guidance and which plans the advisor can discuss. For example, ask how an enrollment conversation will address your doctors, prescriptions, and preferred care arrangements.
Finding a Licensed Advisor
To find a licensed Medicare advisor near Port Jefferson, begin with the advisor’s name and New York insurance license details. Use official state licensing records to review license information. Then ask how the advisor handles Medicare plan discussions and what enrollment support is available. Clear answers help you understand the advisor’s role before sharing personal information or making a decision.
Which Medicare advisors and brokers serve Port Jefferson, NY? The area is served by insurance agencies and brokers who work with residents of Suffolk County. Rather than relying on a name alone, consider whether the advisor can explain plan differences in plain language and address your specific enrollment questions. A local office can be convenient, while remote support may also suit someone who prefers phone or online conversations.
Use a short checklist when assessing the fit:
- Confirm the advisor’s name and New York license details.
- Describe your enrollment question and note whether the explanation is clear.
- Ask which coverage choices the advisor can discuss.
- Clarify how the advisor is compensated and whether you pay a separate fee.
- Agree on the next step, such as reviewing your needs or discussing plan options.
These steps help you compare the service itself, not just an office address. A helpful conversation should leave you understanding what the advisor can do and what decision comes next.
Initial, Special, and General Enrollment Periods
Medicare enrollment timing depends on your age, existing coverage, and circumstances. In 2026, identifying the right enrollment period helps you plan the next step. The Initial Enrollment Period centers on turning 65. A Special Enrollment Period may apply when circumstances or coverage change. The General Enrollment Period provides another defined time to enroll.
Initial Enrollment Period
The Initial Enrollment Period lasts seven months around your 65th birthday. Use that window to organize your Medicare enrollment decisions and understand which parts you may need. Mark your birthday month, then map the months around it on a calendar. For example, someone turning 65 in October should use October as the reference point when reviewing the seven-month window. This period is a useful starting place, even if current work coverage affects the decision.
Keep the decision focused. Write down whether you already receive Medicare, whether you expect to keep employer coverage, and when that coverage may change. These details connect your birthday timeline with the coverage choices you need to consider. A clear record also helps distinguish an initial enrollment question from a later change in circumstances.
Special Enrollment Period
A Special Enrollment Period may matter when a change in your circumstances affects Medicare enrollment. Include employment and employer coverage in that discussion. Rather than assuming every job or insurance change creates the same enrollment opportunity, note what changed and when. Then use those facts to identify whether a special enrollment window may fit your situation.
For example, record the date employment ends, the date employer coverage ends, and whether the coverage belongs to you or a spouse. Keep notices showing the coverage dates. This information helps clarify your timeline and the question to resolve. If your job continues but your insurance changes, record that too. The specific circumstances matter.
General Enrollment Period
The Medicare General Enrollment Period runs from January 1 through March 31, according to the Centers for Medicare & Medicaid Services. It is a key period for people who need to enroll in Medicare and do not have another applicable enrollment opportunity. If you enroll during this period, Medicare Parts A and B become effective July 1. That date is important for planning care and coverage needs.
Use a calendar to track the enrollment window and the July 1 effective date. Make a list of the Medicare parts you need, then organize the information related to your current coverage. Do not confuse the period when you submit an enrollment with the date coverage begins. Those dates serve different purposes.
To sort out your timeline, follow these steps:
- Write down your 65th birthday month and Initial Enrollment Period.
- Record any employment or coverage changes and their dates.
- Identify whether the General Enrollment Period or a Special Enrollment Period may apply.
- Note the July 1 effective date if enrolling during the General Enrollment Period.
This simple timeline turns dates into a practical enrollment plan. Keep it with your coverage documents so each Medicare decision connects to the right period.
Medicare enrollment options in Port Jefferson
In 2026, Port Jefferson residents can compare Original Medicare with Medicare Advantage and prescription drug coverage. Suffolk County has 27 Medicare Advantage plans and 12 standalone Medicare Part D plans available. These figures offer a local starting point, but the plan details matter more than the total count. Compare coverage against your doctors, prescriptions, and preferred way to receive care.
Which Medicare Part D prescription drug plans serve Port Jefferson? Suffolk County has 12 standalone Medicare Part D plans available. A plan’s premiums, covered medicines, pharmacy network, and rules for filling prescriptions help distinguish one option from another. Review your current prescriptions against each plan’s coverage information before enrolling.
Original Medicare does not include an out-of-pocket maximum. Medicare Advantage plans have different coverage structures, with 12 PPO plans and 15 HMO plans available in Suffolk County. These plan types differ in how they organize provider access. Ask how each option handles your doctors, referrals, and out-of-network care. If you take regular medication, consider how prescription coverage fits into the overall choice.
What should you ask a Medicare advisor before enrolling? Ask which plans they can compare, how your doctors and prescriptions fit, and what costs or coverage limits to consider. Also ask how plans handle referrals, pharmacies, and care outside your usual area. Clear answers help you weigh coverage details instead of choosing based only on a plan’s name.
Use this discussion checklist to keep the comparison focused:
- List your doctors, preferred hospitals, and regular prescriptions.
- Ask whether those providers and medicines are covered by each option.
- Discuss monthly premiums, deductibles, copayments, and other cost-sharing.
- Ask how PPO and HMO networks differ for your care.
- Review whether the coverage still fits if your health needs change.
How can you check an advisor’s Medicare credentials and avoid sales scams? Ask for the advisor’s name and New York insurance license details, then use New York’s official license lookup to review them. Do not share personal information or make an enrollment decision under pressure. Take time to read plan materials and ask for clear explanations of unfamiliar terms.
Plan details can change, so review your coverage annually during the Medicare Open Enrollment Period. For example, a prescription covered last year could call for a fresh comparison this year. Keep your medication list and provider preferences together, then revisit them during your annual review. This routine makes a Port Jefferson plan comparison more personal and practical.
Port Jefferson residents can compare the 12 standalone Medicare Part D plans available in Suffolk County, focusing on premiums, covered medicines, pharmacy networks, and prescription-filling rules.
Port Jefferson office
Port Jefferson is in Suffolk County, and its ZIP code is 11777. For Medicare enrollment planning, separate questions about official enrollment from questions about comparing coverage. That distinction helps you decide what information to bring and which conversation you need. A local address can make the process feel more manageable, especially when you have dates or documents to discuss.
The Social Security office listed nearest to Port Jefferson is at 75 Oak Street in Patchogue, NY 11772. It is 12.68 miles away. Its listed phone number is (866) 771-1991, and its hours are Monday through Friday, 9:00 AM to 4:00 PM. These details give Port Jefferson residents a nearby office reference for planning.
Before a conversation, organize the information related to your enrollment question. Write down your birthday month, current work status, and any expected change to employer coverage. Keep relevant notices and correspondence together. If your question concerns when to enroll, dates matter. If it concerns choosing coverage, list your doctors, prescriptions, and care preferences separately.
- Keep your Medicare and employer coverage papers in one folder.
- Write down the dates when work or insurance may change.
- Bring a list of questions, grouped by enrollment and plan choice.
- Note the Patchogue office address and its listed weekday hours.
Use the Patchogue listing as a practical reference, not a substitute for understanding your decision. An office visit may address a different task than comparing plan choices. For example, a question about an enrollment timeline differs from asking how plan networks or prescription coverage compare. Separating these needs helps you use your time well and keep each discussion focused.
Preparing locally can also help if you’re supporting a spouse or family member. Write down whose coverage is changing and the relevant dates. Keep each person’s documents separate, especially when both have employer insurance. A clear folder and short question list can make a phone or in-person conversation easier to follow.
For a coverage discussion, start with the specific choice you need to make and the details that affect it. If you’re ready to explore how Medicare coverage options work, review Medicare Advantage plan information as part of your next step. Keep enrollment timing and plan selection as separate questions, so each gets the attention it deserves.
The Modern Medicare Agency
The Modern Medicare Agency helps you compare Medicare coverage options and understand your next steps. If you’ve sorted out your enrollment timing but feel unsure about plan choices, its independent brokers provide personalized guidance. They help eligible individuals compare Medicare Advantage, Medigap, and Part D plans from over 40 carriers, with recommendations based on individual needs.
The Modern Medicare Agency can help when you’re weighing plan differences, reviewing prescription coverage, or deciding what to ask before enrolling. The agency also provides year-round support for claims, billing, and plan changes, so you can return with questions as your needs change. Its role is to help you understand available insurance options, not replace Medicare’s enrollment process.
For personal guidance with your Medicare choices, book a free consultation with The Modern Medicare Agency by phone or Zoom.
Take Your Next Medicare Step With Confidence
Your Medicare decision should fit the care you value and the coverage you need. Before enrolling, bring your questions together and focus on the choices that matter most. A medicare advisor in Port Jefferson, NY can help make plan details easier to understand and support an informed decision.
The Modern Medicare Agency helps people compare Medicare Advantage Plans, Medicare Supplement (Medigap) Plans, and Medicare Part D Plans. Whether you’re considering coverage for the first time or reviewing your options, a free consultation can help you identify what to explore next. You remain in control of the decision, with guidance to make the choices clearer.
When you’re ready to talk through your Medicare questions, contact The Modern Medicare Agency. Take the next step at your own pace and move forward with greater clarity.
Frequently Asked Questions
Need Help With Medicare Enrollment in Port Jefferson, New York?
Yes. A Medicare advisor in Port Jefferson, NY can help you understand plan choices and enrollment steps. The Modern Medicare Agency provides personalized assistance comparing Medicare Advantage, Medigap, and Part D options. Before your free consultation, write down your main concern, such as a prescription, preferred doctor, or upcoming retirement. That gives the discussion a clear starting point and keeps it focused on what matters to you.
What Medicare advising services are available in Port Jefferson?
Medicare advising can include guidance comparing Medicare Advantage, Medicare Supplement (Medigap), and Part D plans. The Modern Medicare Agency also provides enrollment assistance and year-round support. For example, if your prescription needs change, you can discuss how that affects your coverage choices. A conversation can also help you organize questions about doctors, pharmacies, and plan details before deciding which option fits your needs.
Which Medicare Advantage plans are available in Port Jefferson, NY?
Medicare Advantage options in Port Jefferson include plans with different provider networks and coverage details. The right choices depend on factors such as your preferred doctors, hospitals, prescriptions, and how you receive care. Plan names and benefits can vary, so focus on the details that affect your routine. For instance, if you regularly see a particular specialist, include that provider in the comparison.
When are Medicare enrollment periods, and what are the deadlines?
Your enrollment window depends on your age and coverage circumstances. The Initial Enrollment Period is centered on your 65th birthday, while a Special Enrollment Period may apply after certain coverage changes. The General Enrollment Period runs from January 1 through March 31, and enrollment during it takes effect July 1. Keep a calendar of birthday, employment, and coverage dates to help identify which deadline may fit.
Article by
Paul Barrett
Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.
He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.
📞 631-358-5793 | paulbinsurance.com