
- Employer Medicare Support
Your employees have Medicare questions. You shouldn't have to answer them.
Give your HR team a dedicated Medicare resource for enrollment, compliance, and penalty prevention — with plain-English education and one-on-one licensed advisor support for every employee.
- No cost to organization
- Licensed advisors
- Compliance-minded
20+
employee threshold that changes payer rules
6 months
lead time to prepare employees turning 65
One resource
for HR, employees, and retirement transitions
Why this matters
Medicare transitions create real risk for HR teams — and real consequences for employees.
The answer is not more work for HR. It is a clear process and a qualified Medicare resource available before the deadline.
Missed enrollment deadlines
The 7-month Initial Enrollment Period and the 8-month Part B Special Enrollment Period are easy to misread. A late Part B penalty is generally 10% of the standard premium for each full year of delay.
COBRA and SEP confusion
COBRA can continue health coverage, but it does not extend the Part B Special Enrollment Period. The clock starts when active-employment coverage ends.
MSP compliance exposure
Employer size determines whether the group plan or Medicare pays first. A wrong payer determination can create conditional-payment recovery years later.
Questions outside HR's scope
Employees need individual help comparing doctors, prescriptions, networks, travel, and budgets. HR should not have to become a licensed Medicare advisor.
A clear process. Personal guidance. Less pressure on HR.
20 or more employees
Group plan pays first
Medicare pays second for active employees. They may generally delay Part B without penalty while active coverage continues.
Fewer than 20 employees
Medicare pays first
Employees usually need Medicare at 65. The group plan pays secondary, so delaying Part B can leave claims exposed.
01
Identify employees approaching 65
Start outreach at least six months before the Initial Enrollment Period opens.
02
Offer one-on-one advisor consultations
Each employee reviews their employer size, doctors, prescriptions, health needs, and budget.
03
Support the transition
Stay connected through retirement, COBRA changes, enrollment, and the first questions after coverage begins.
Less risk. Less interruption. More confidence.
- Written guidance on employer size, payer order, and SEP timing
- A direct answer to employee Medicare questions
- Support for creditable coverage and retirement communications
- No added payroll or benefits administration workload
A person who knows their situation.
- Plain-English education before an enrollment window closes
- Plan comparisons based on doctors and prescriptions
- Help avoiding Part B and Part D penalties
- Ongoing support after enrollment — not a one-time handoff
How Medicare Support Can Make Life Easier for HR and Employees
Paul explains how HR can support Medicare-eligible employees, connect them with individual guidance, and access ongoing help. Employees can also use the existing on-demand, plain-English Medicare education session before their one-on-one review.
- Support employees approaching Medicare
- Provide guidance through eligibility and enrollment
- Reduce pressure on internal HR teams
Who this supports · HR Medicare support in practice
Supporting HR Teams Across Different Workplaces
Medicare questions arise in every industry. These are examples of workplaces the program can support, not representations of current clients.
- Manufacturing
- Healthcare organisations
- Professional services
- Education
- Municipalities and public organisations
- Professional services
- Professional services
- Professional services
HR Medicare Resource Center
The answers HR professionals need.
Group Health Plan and Medicare Coordination Rules
MSP Compliance
Medicare Secondary Payer (MSP) Compliance for Employers
Avoiding Medicare Late-Enrollment Penalties and Compliance Risk
COBRA and Medicare: The Timing Mistake That Costs Employees for Life
Real employer results. No cost to the company.
Two employers — one in skilled trades, one in auto retail — used ongoing Medicare education and one-on-one advisor support to help employees transition confidently while improving the group’s bottom line.
Tamco Mechanical
A 3-year partnership helping skilled tradespeople retire into Medicare without the stress.
employees educated & transitioned
The situation
Rather than a one-time project, we worked as an ongoing extension of Tamco’s HR team. As each employee approaches 65, we handle the full education and research process individually — what Medicare covers, when to enroll, why timing matters, and what their real options look like given their health needs and work status.
What we did
Rather than a one-time project, we worked as an ongoing extension of Tamco’s HR team. As each employee approaches 65, we handle the full education and research process individually — what Medicare covers, when to enroll, why timing matters, and what their real options look like given their health needs and work status.
The results
Rather than a one-time project, we worked as an ongoing extension of Tamco’s HR team. As each employee approaches 65, we handle the full education and research process individually — what Medicare covers, when to enroll, why timing matters, and what their real options look like given their health needs and work status.
Atlantic Hyundai
group premium reduction
The situation
Long-tenured employees had stayed on the company medical plan well past 65 — some out of habit, some because nobody had ever laid out what Medicare would actually look like for them. Those employees were paying group-plan premiums that, for most people over 65, run higher than Medicare plus a supplement or Advantage plan.
What we did
The results
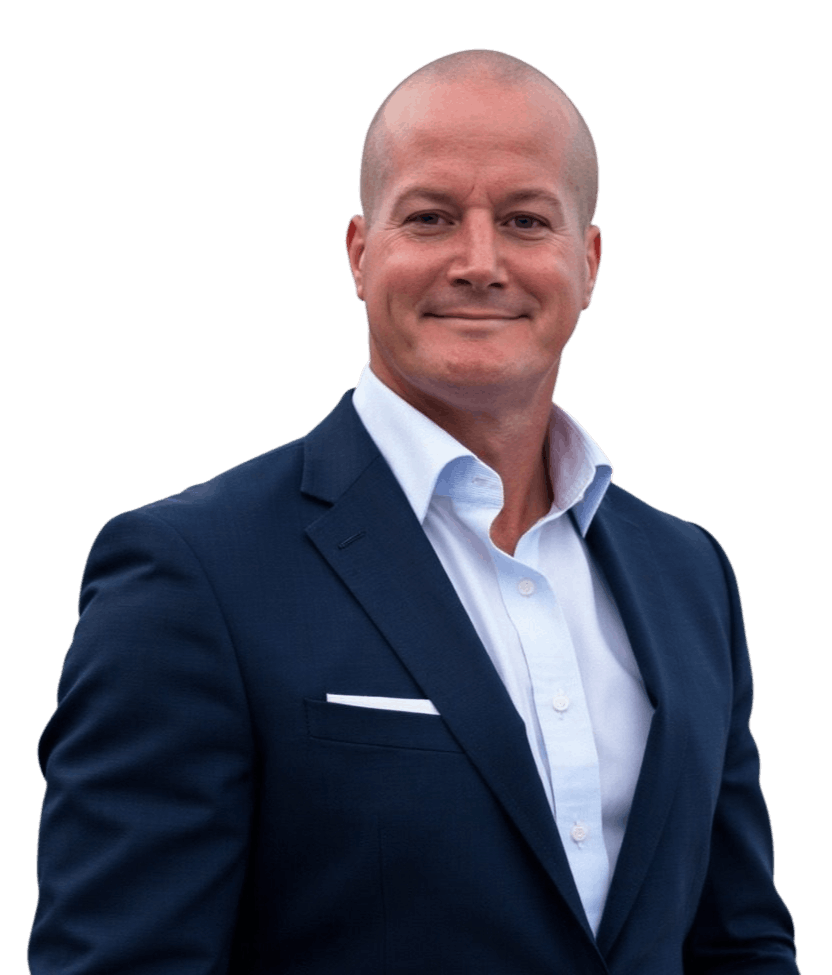
A named resource, not a call center
Meet the advisor behind the program.
Paul Barrett is the founder of The Modern Medicare Agency and a licensed independent Medicare advisor. His job is to make the complicated transition understandable for the employee — while giving HR a reliable person to call when a Medicare question lands in the inbox.
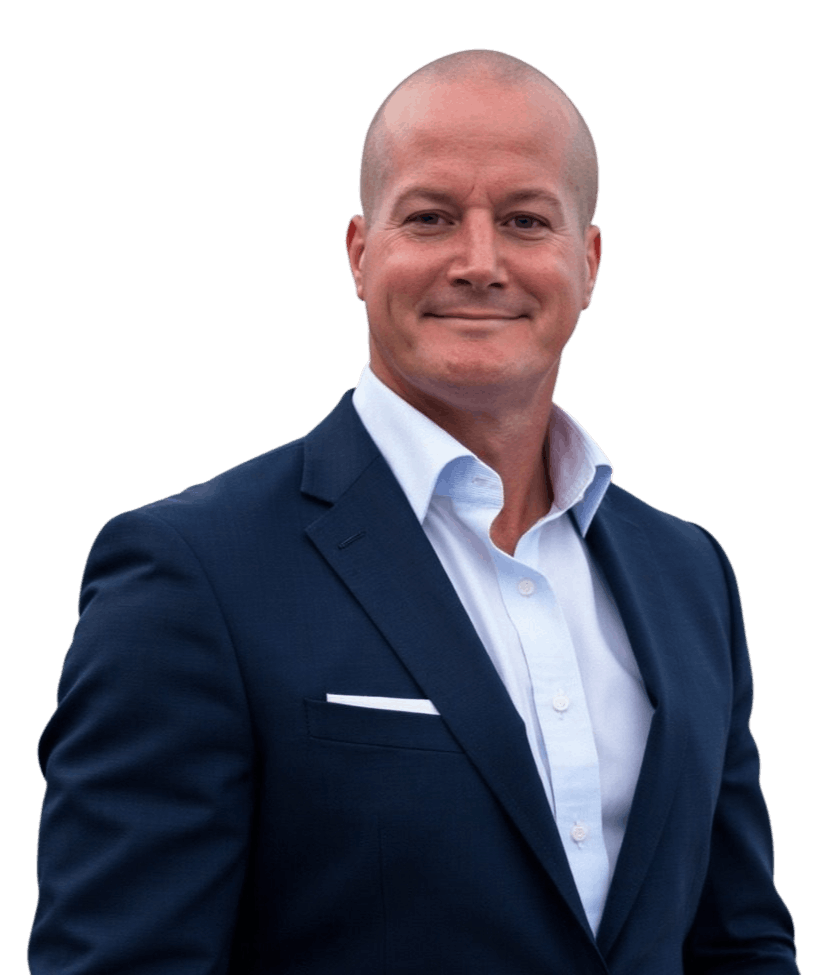
- Reviewed by
Paul Barrett
Founder, The Modern Medicare Agency · 18+ years of Medicare experience
Licensed independent broker · Content reviewed for accuracy in 2026
- Free On-Demand Webinar
Give employees a Medicare education session on demand
Share a plain-English Medicare walkthrough before employees sit down for their one-on-one review. It covers the major decisions without turning HR int
- 30 minutes
- 1,000+ attendees
- Watch instantly
- People also ask
Frequently Asked Questions About Employer Medicare Support
The education and one-on-one Medicare consultations are provided at no cost to the organization or employee. Paul Barrett is compensated by Medicare plan carriers when an employee chooses a plan through him, with no additional fee to the employee or employer and no obligation to enroll.
Organizations with 20 or more Medicare-eligible employees often see the clearest operational value, but smaller employers also benefit because Medicare is primary for many employees at that size. We start with a conversation about headcount, plan design, and goals.
HR can provide factual information about the group plan, employer size, creditable coverage, and deadlines. Specific Medicare plan recommendations should come from a licensed Medicare advisor who can review the employee’s doctors, prescriptions, and budget.
No. Employer Medicare support complements your existing broker, carrier, and TPA relationships. Paul focuses on the individual Medicare transition and employee education while your benefits team continues to manage the group plan.
Begin six months before employees turn 65 and at least 90 days before planned retirement. That gives employees time to understand primary payer rules, stop HSA contributions when needed, and enroll without a coverage gap.
Make Medicare a benefit your organization can stand behind.
Start with one conversation. We’ll map the right support model for your workforce, with no cost and no obligation.