Last Tuesday, a Massapequa neighbor named Joan discovered her friend could no longer see her longtime cardiologist at St. Joseph Hospital because of a sudden network shift. While Joan felt for her friend, she didn’t share that same stress because her own coverage hasn’t changed. We know that living in Nassau County in 2026 feels more expensive than ever, especially with the latest shifts in healthcare regulations. It’s easy to feel overwhelmed by the new $2,100 out of pocket cap for prescriptions and the 2026 Part B deductible increase to $283. This Medicare supplement guide to plan G in Massapequa NY is here to simplify the noise and put you back in control of your healthcare.
At The Modern Medicare Agency, we promise to help you understand these specific 2026 costs and benefits so you can choose your doctors with total financial confidence. You deserve to know exactly what you’ll pay each month without the fear of a surprise bill landing in your mailbox. We’ll walk you through the current local premiums, explain how to protect your access to specialists at St. Joseph, and show you why Plan G remains the gold standard for predictable care in our community.
Key Takeaways
-
Discover why Plan G remains the gold standard for Massapequa seniors in 2026, offering you the total freedom to keep your trusted doctors without any restrictive network traps.
-
Learn how to eliminate the stress of unpredictable medical bills with 100% coverage for hospital and outpatient coinsurance after you meet your annual deductible.
-
Our Medicare supplement guide to plan G in Massapequa NY explains how New York’s unique “Community Rating” laws protect your budget and offer long-term financial peace of mind.
-
Understand the critical differences between predictable Medigap premiums and the growing out-of-pocket costs found in many local 2026 Medicare Advantage plans.
-
Follow our simple, step-by-step enrollment process to secure your benefits with total confidence and ensure you never face a late enrollment penalty.
Table of Contents
-
Understanding Medicare Supplement Plan G in Massapequa for 2026
-
What Plan G Covers (and Why It Is Nassau County’s Top Choice)
-
Plan G vs. Medicare Advantage in Massapequa: Making the Right Choice
Understanding Medicare Supplement Plan G in Massapequa for 2026
Welcome to the 2026 Medicare landscape . If you feel a bit overwhelmed by the stacks of mail and constant phone calls, you aren’t alone. We believe clarity is the best medicine for insurance stress. Our goal is to replace that confusion with the quiet confidence that comes from knowing you’re protected. For Massapequa residents turning 65 or looking to switch coverage this year, Plan G stands out as the most comprehensive Medigap option available to new enrollees. We created this Medicare supplement guide to plan G in Massapequa NY to help you understand why this specific plan is the top choice for our neighbors in Nassau County.
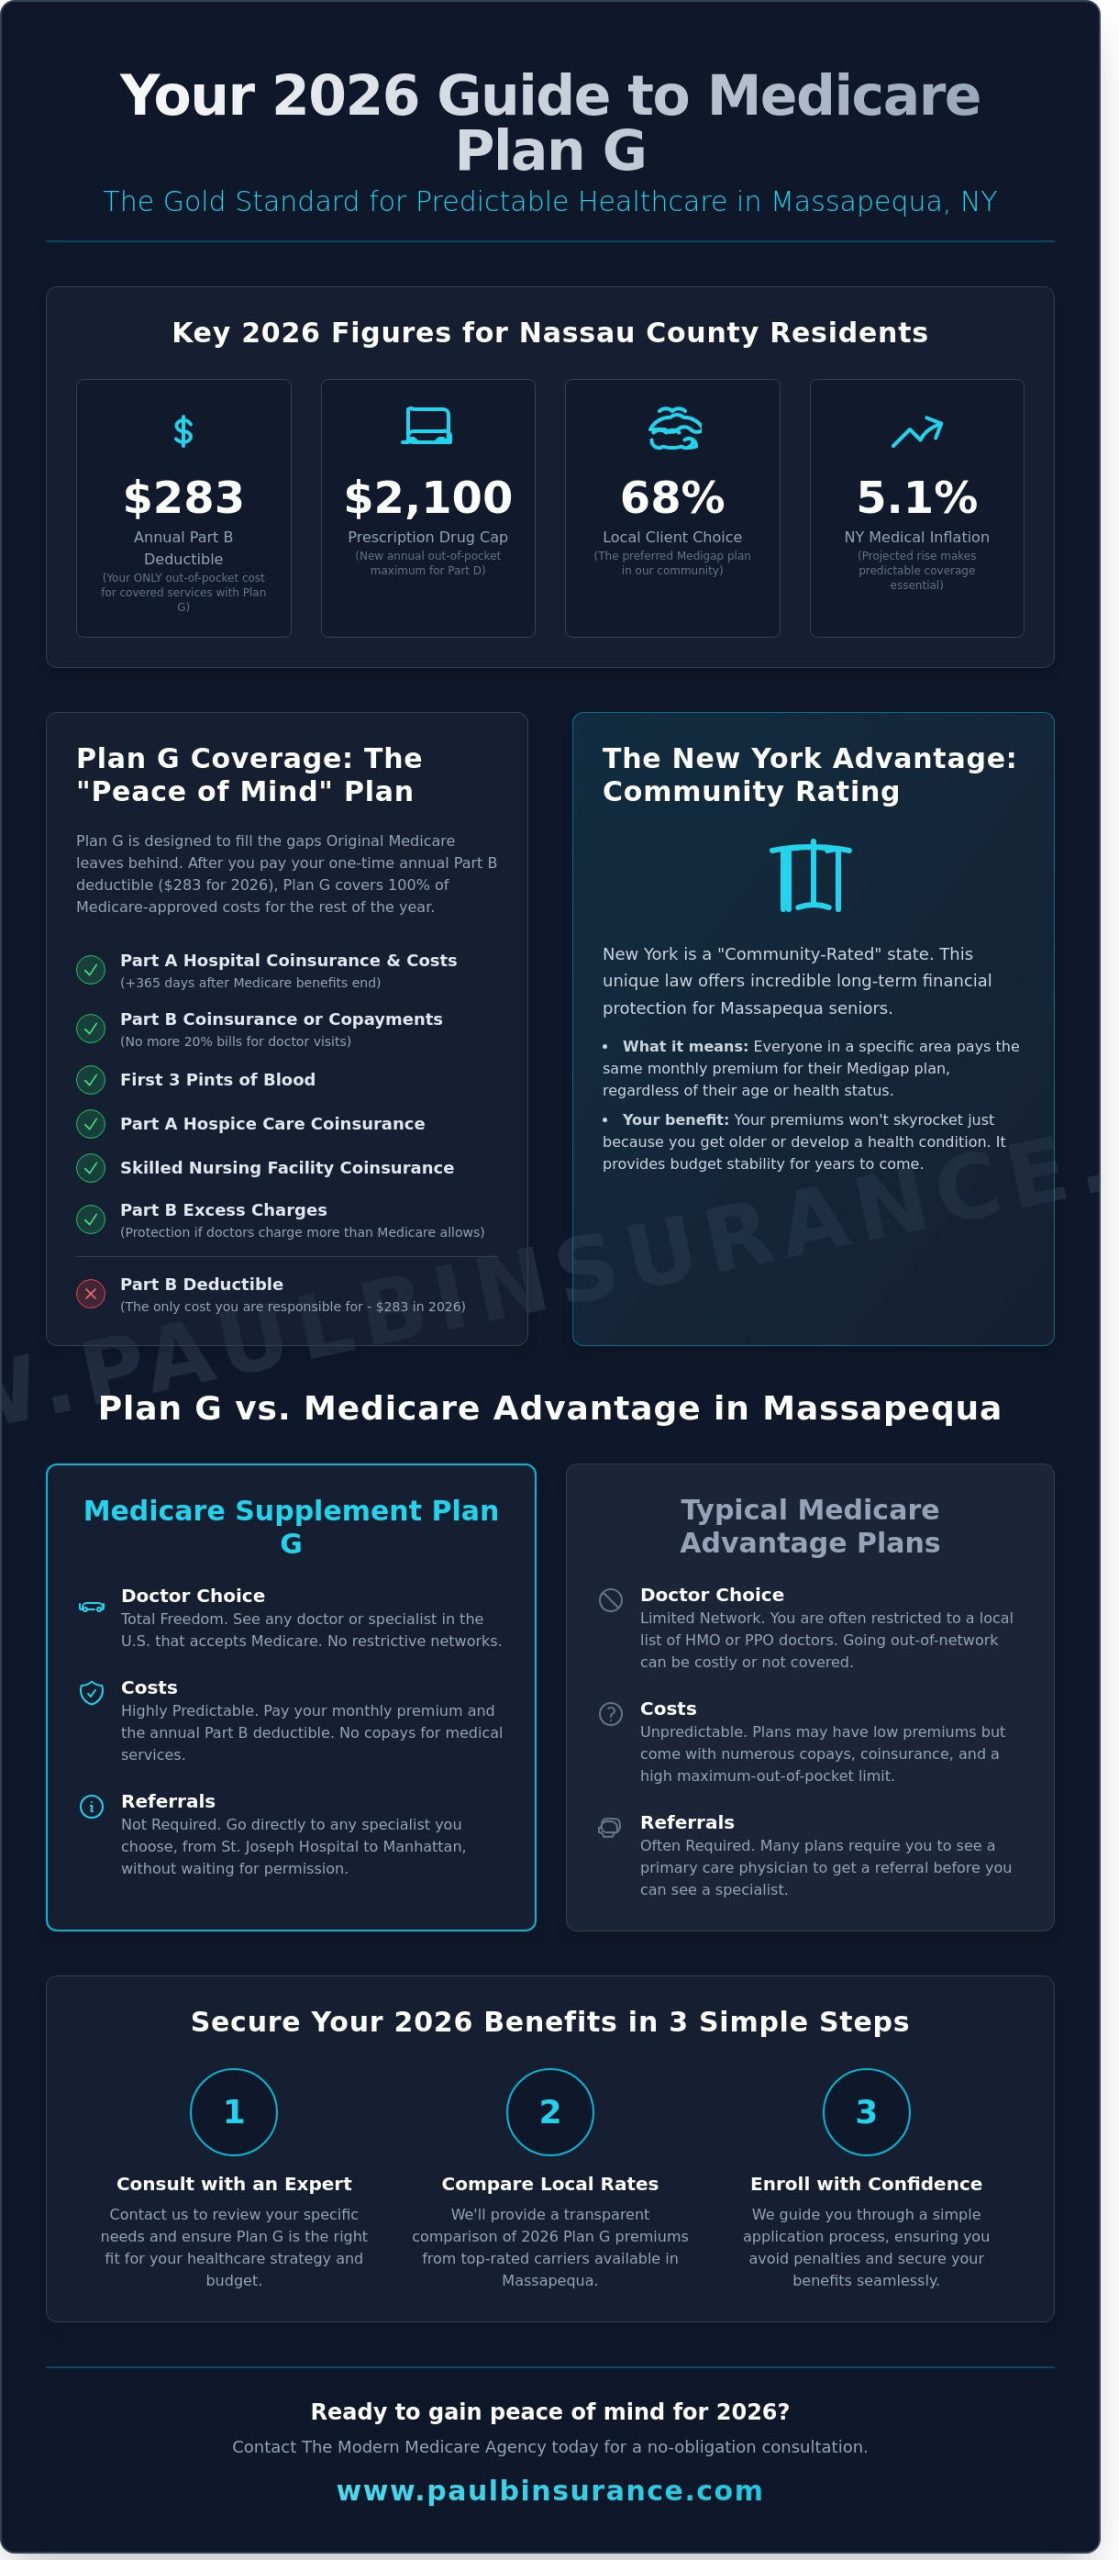
Living in a high cost area like Long Island means healthcare expenses can climb quickly. In 2026, medical inflation in New York is projected to rise by another 5.1 percent, making "inflation-proof" coverage more important than ever. Plan G offers a level of predictability that other plans simply can’t match. Once you pay your annual Part B deductible, you won’t see another medical bill for covered services for the rest of the year. We call it the "peace of mind" plan because it removes the guesswork from your monthly budget. You know exactly what your costs are, no matter how many times you need to see a doctor or specialist.
Massapequa residents choose Plan G because it offers total freedom. You aren’t locked into a network or restricted by a zip code. If a doctor accepts Medicare, they accept your Plan G coverage. Whether you are visiting a local specialist on Sunrise Highway or seeing a world-renowned surgeon in Manhattan, your coverage follows you. This Medicare supplement guide to plan G in Massapequa NY highlights that this freedom is the primary reason why 68 percent of our local clients choose Plan G over other standardized options.
The Role of Medigap in Your 2026 Healthcare Strategy
Original Medicare is a great foundation, but it has significant "holes" that can lead to high out of pocket costs. It generally only covers 80 percent of your Part B expenses, leaving you responsible for the remaining 20 percent. Understanding Medigap Plans is essential because these policies are specifically designed to fill those financial gaps. We help you look at your 2026 strategy as a way to protect your hard-earned savings from a single major illness. If you want to learn more about how these different letters work, feel free to visit our Medigap overview page for a deeper dive. We simplify the jargon so you know exactly how it works before you sign anything.
Massapequa-Specific Benefits of Plan G
One of the biggest frustrations we hear from Nassau County seniors is the "referral maze" found in many HMO plans. If you have a trusted cardiologist near St. Joseph Hospital or use the local Catholic Health facilities, you don’t want to wait weeks for a primary care doctor to give you "permission" to see them. With Plan G, you bypass that entire process. You can make an appointment directly with any specialist who accepts Medicare. Plan G is the plan that covers everything except the Part B deductible. For 2026, the Part B deductible is estimated at $265, which is a small price to pay for the ability to access the best healthcare New York has to offer without any additional co-pays or hidden fees.
What Plan G Covers (and Why It Is Nassau County’s Top Choice)
Plan G has become the most popular choice for our neighbors here in Nassau County for one simple reason: it offers the most predictable path to peace of mind. When you look at a Medicare supplement guide to plan G in Massapequa NY, the first thing you will notice is how it eliminates the "what ifs" of medical billing. We believe you should spend your retirement enjoying the Massapequa Preserve or a quiet morning at a local diner, not worrying about an unexpected hospital bill. This plan is designed to step in exactly where Original Medicare leaves off.
The coverage is remarkably thorough. Plan G pays 100% of your Part A hospital coinsurance and all hospital costs for up to 365 days after your Medicare benefits are exhausted. It also handles 100% of your Part B coinsurance or copayments. This means if you have a procedure at a local facility like St. Joseph Hospital, you won’t be responsible for that 20% bill that Medicare usually leaves behind. We also focus heavily on skilled nursing facility care. Plan G covers the coinsurance for these stays, which is vital if you need recovery time at a local Nassau rehab center after a surgery or illness. Other benefits include:
-
Full coverage for the first three pints of blood needed for a medical procedure.
-
100% coverage for Part A hospice care coinsurance or copayments.
-
Protection against Part B excess charges, which can happen if a provider charges more than the Medicare-approved amount.
The Only Out-of-Pocket Cost: The 2026 Part B Deductible
In 2026, the annual Part B deductible is $283. This is the only amount you pay out of your own pocket before your Plan G coverage starts paying for doctor visits, lab work, and outpatient services. We find that paying this single amount once a year is much simpler than dealing with the unpredictable copays found in other plans. It allows for a very clean, manageable budget. You pay your monthly premium, pay the first $283 of your medical bills, and then you’re done for the year. To see how this fits into the broader picture of your options, you can check the official Medicare comparison guide to see how Plan G stacks up against other standardized plans.
Plan G vs. Plan N: The Massapequa Comparison
While Plan G is the "gold standard," we often get questions about Plan N. The main difference involves small, recurring copays. With Plan N, you might pay up to $20 for an office visit or $50 for an emergency room trip. For some people, the slightly lower monthly premium of Plan N is attractive. However, Plan G remains the top pick for those who want zero surprises. If you visit your specialist in Massapequa frequently, those $20 charges can add up quickly over twelve months. We help you look at your specific health history to decide if those small premium savings are actually worth the extra paperwork and local copays. If you’re feeling a bit stuck on which path to take, we can help you compare these costs side-by-side to find the right fit for your lifestyle. Our goal is to make sure you feel confident in your choice, knowing exactly what to expect when you walk into your doctor’s office.
Plan G vs. Medicare Advantage in Massapequa: Making the Right Choice
We see the confusion every day in our office. You are likely bombarded with mailers and TV commercials, each promising something better than the last. Choosing between Plan G and Medicare Advantage isn’t just about picking a plan; it’s about deciding how you want to access healthcare in Nassau County. This Medicare supplement guide to plan G in Massapequa NY is designed to help you see past the flashy marketing and understand the long term impact on your wallet and your health.
The biggest difference comes down to a simple trade-off. We often tell our neighbors that Plan G protects your savings, while Medicare Advantage protects your monthly budget. If you choose an Advantage plan, you might enjoy a $0 monthly premium, but you take on the risk of unpredictable copays. If you face a health challenge in 2026, those $40 or $50 specialist visits and $300 hospital daily copays add up fast. Plan G requires a monthly premium, but it removes the fear of the unknown. When you look at this Forbes Advisor guide to Plan G, you’ll see it covers nearly every gap left by Original Medicare, leaving you with almost no out of pocket costs.
-
Predictable Costs: With Plan G, you pay your premium and your small annual deductible. That is it.
-
Freedom of Movement: You don’t need a referral to see a specialist in Manhattan, Florida, or right here in Massapequa.
-
No Financial Surprises: You won’t be caught off guard by a massive bill after an emergency room visit.
Evaluating Local Doctor Networks
We often warn clients about the "Network Trap." Many local specialists in Massapequa or nearby Bethpage might not participate in every Advantage network. If your trusted primary care doctor on Front Street or your cardiologist near Sunrise Highway leaves the network, you might be forced to find a new doctor or pay high out of network rates. Plan G doesn’t have networks. You can see any doctor who accepts Medicare. This eliminates the stress of "Prior Authorizations," which are common in Nassau County Advantage plans. For a deeper look at how these networks function, you can read our Medicare Advantage Guide to compare the two side by side.
Financial Predictability in 2026
In 2026, the Maximum Out-of-Pocket (MOOP) limit for many Medicare Advantage plans in our area has climbed toward $9,350 for in-network services. If you are managing a chronic condition like diabetes or heart disease, you could hit that limit sooner than you think. Plan G offers a different level of security. With Plan G, your only medical bill is usually your monthly premium, plus the small Part B annual deductible. This certainty is why we recommend Plan G for seniors who want to know exactly what their healthcare will cost for the entire year. We believe that true peace of mind comes from knowing that a health crisis won’t become a financial crisis. We are here to help you move from confusion to confidence by showing you the math behind both options.
Cost of Plan G in Massapequa: 2026 Rates and Trends
Pricing for Medicare supplements in Nassau County often feels like a moving target. We know the stress that comes with opening a rate increase letter in the mail. In 2026, Massapequa residents are seeing a shift in how carriers price their products. Because Massapequa is located in Region 3, premiums are typically higher than what you might find in upstate New York, but the protection you receive is far superior. We help you look past the monthly premium to see the true value of your coverage.
Our team analyzes the data from over 40 carriers licensed in New York to ensure you aren’t overpaying for the 11758 zip code. While the benefits of every Plan G are identical by law, the prices vary wildly. Some companies have managed to keep their 2026 increases under 4%, while others have jumped by double digits. This Medicare supplement guide to plan G in Massapequa NY is designed to help you spot those trends before they impact your bank account.
The 2026 Part D Synergy
A major reason Plan G is the top choice for Massapequa seniors this year is the massive change to prescription drug coverage. As of January 1, 2026, the new $2,100 out of pocket cap for prescriptions is fully active. This change works in perfect harmony with Plan G. Since Plan G covers 100% of your Medicare Part B gaps after a small deductible, and your drugs are now capped at $2,100, your total financial exposure for the year is lower than it has ever been. We call this the "safety bubble" strategy. You can learn more about how these drug costs work in our Medicare Part D guide.
Why NY Rates Are Different
New York is a "Community Rated" state. This is a massive win for you. In most other states, your price goes up simply because you had a birthday. In Massapequa, a 65 year old and an 85 year old pay the exact same premium for the same plan with the same company. This creates long term stability for your retirement budget. You don’t have to worry about being priced out of your plan as you age. We also benefit from "Continuous Enrollment," which means:
-
You can switch your Medigap plan at any time during the year.
-
There is no medical underwriting, so your health history doesn’t matter.
-
You are never locked into a plan that has become too expensive.
-
"Pre-existing conditions" cannot be used to deny you coverage.
Even with these protections, carriers still adjust their base rates annually. For 2026, we are seeing some carriers offer "household discounts" as high as 12% if two people in the same home have a policy. These small details are where we find your biggest savings. We focus on the math so you can focus on enjoying your retirement. We simplify the jargon so you know exactly how it works and where every dollar is going. If you feel overwhelmed by the options, remember that you have an advocate in your corner. We are here to move you from confusion to confidence.
Schedule a Call With Paul to compare 2026 Plan G rates in Massapequa today.
How to Enroll and Secure Your 2026 Benefits
We know that looking at health insurance often feels like staring into a thick Long Island fog. You want clarity, but the more you look, the more confusing the "Medicare maze" becomes. As we move through 2026, the rules for Medigap in Nassau County remain stable, but your personal path to enrollment requires a steady hand. We are here to help you move from a state of total confusion to complete confidence. This Medicare supplement guide to plan G in Massapequa NY is designed to make your transition into 2026 as smooth as possible.
Step 1: Confirm your Medicare Part A and B effective dates. Before we can look at Plan G, we need to verify your enrollment in Original Medicare. You’ll find these dates on your red, white, and blue card. In 2026, the Part B deductible has adjusted to approximately $283, and knowing your start date ensures we time your supplement application perfectly to avoid any gaps in coverage.
Step 2: Review your current doctors and medications with us. While Plan G allows you to see any provider in the country who accepts Medicare, we still take the time to double-check your local Massapequa specialists. We want to ensure your transition is seamless and that your specific prescriptions are factored into your total 2026 budget strategy.
Step 3: Compare the top-rated Plan G carriers in Nassau County. Not all insurance companies are the same, even if the benefits are identical. We analyze the 5-year rate increase history for the 12 major carriers currently serving the 11758 zip code. We look for companies with a track record of stability so you aren’t hit with a massive premium hike in 2027.
Step 4: Apply with a "never rushed" expert. When you’re ready, we handle all the heavy lifting. We fill out the paperwork and track the application through the underwriting process. We act as your personal concierge, ensuring you never have to sit on hold with a giant insurance company.
Our Simple 5-Step Process
We’ve spent years refining how we help our neighbors in Massapequa. Our process is built on one core idea: an independent broker is your advocate, while a captive agent is just a salesperson for one company. Because we are independent, we can shop the entire market for you. When you follow this Medicare supplement guide to plan G in Massapequa NY, you avoid the common pitfalls that lead to late enrollment penalties. Your first "Coffee with Paul" is a relaxed, no-pressure phone call or meeting where we listen to your needs first and talk second. We simplify the jargon so you know exactly how your 2026 benefits will work from day one.
Don’t Forget Your Smile: Dental and Vision
One detail that surprises many seniors is that Plan G does not cover routine dental or vision care. It will cover medical issues, like a cataract surgery or an emergency tooth extraction at the hospital, but it won’t pay for your biannual cleanings or new glasses. We don’t want you to be caught off guard by these out-of-pocket costs. We can help you bridge this gap by exploring our Dental Insurance Plans. These plans are designed to complement your Medigap coverage and keep your healthcare costs predictable. You don’t have to do this alone; we are here to protect your health and your wallet.
Your Path to a Confident 2026 Coverage Choice
Navigating the 2026 Medicare landscape doesn’t have to feel like a stressful maze. We’ve shown you why Plan G remains the gold standard for Nassau County seniors who want predictable costs and zero surprises at the doctor’s office. By covering every gap except the annual Part B deductible, this plan provides a level of security that Medicare Advantage simply cannot match. This Medicare supplement guide to plan G in Massapequa NY highlights that while benefits are standardized, the monthly premiums from 40 different carriers vary significantly. You shouldn’t have to guess which company offers the best value for your fixed income.
We’ve spent over 15 years helping our neighbors right here in Nassau County move from confusion to total confidence. Our team simplifies the jargon and handles the paperwork so you can avoid late enrollment penalties and costly coverage gaps. You deserve a plan that works for you, not the insurance company. Let’s ensure your health is protected for the year ahead. Schedule a Call With Paul to Find Your Perfect 2026 Plan and get the unbiased guidance you deserve. We’re ready to help you find peace of mind today.
Frequently Asked Questions
Is Plan G the same as Medicare Part G?
No, there is no such thing as Medicare Part G; Plan G is a private Medicare Supplement insurance policy. We find that many seniors feel overwhelmed by the alphabet soup of insurance, but the distinction is simple. Parts refer to the government program like Part A and Part B, while Plans are the supplemental options we use to bridge the financial gaps. In 2026, Plan G remains the most popular choice for Massapequa residents because it offers the most comprehensive coverage available.
What is the average cost of a Medicare Supplement Plan G in Massapequa for 2026?
The average monthly premium for Plan G in Massapequa for 2026 ranges from $372 to $560. Because New York is a community-rated state, your price isn’t based on your age or health history. We help you compare the 12 different insurance carriers offering coverage in the 11758 zip code to ensure you don’t overpay. Since the benefits are standardized by law, our goal is to find you the lowest price for the exact same coverage.
Can I switch from Medicare Advantage to Plan G during the 2026 Open Enrollment?
Yes, you can switch from Medicare Advantage to Plan G during the Annual Enrollment Period that runs from October 15 to December 7, 2026. New York state laws are very protective, allowing you to move between plans at any time of year without a medical exam. This unique "continuous open enrollment" means we can help you move from a restrictive network to the freedom of Plan G whenever you feel ready to make that change.
Do I need a separate Part D plan if I choose Plan G?
You must enroll in a separate Part D prescription drug plan because Plan G does not include medication coverage. If you go without creditable drug coverage for 63 days or more, Medicare will charge you a permanent late enrollment penalty. We use this Medicare supplement guide to plan G in Massapequa NY to help you identify a 2026 drug plan that covers your specific medications at the lowest possible pharmacy co-pay.
Does Plan G cover dental and vision for Nassau County residents?
No, standard Plan G does not include coverage for routine dental cleanings, eye exams, or glasses. While 85 percent of Medicare Advantage plans include these extras, Medigap focuses entirely on your major medical and hospital bills. We often recommend a separate, standalone dental and vision policy for our clients. This approach allows you to keep your trusted local Massapequa dentists while still enjoying the superior medical protection that a supplement provides.
Will my doctor at St. Joseph Hospital accept Plan G?
Your doctors at St. Joseph Hospital will accept Plan G as long as they participate in original Medicare. Currently, over 98 percent of physicians in the United States accept Medicare patients, which means you aren’t trapped in a limited HMO network. This gives you the confidence to see any specialist on Long Island or across the country without a referral. We want you to feel empowered knowing your healthcare choices are entirely in your hands.
What happens if I move out of Massapequa or New York state?
Your Plan G coverage is fully portable and stays with you even if you move out of Massapequa or leave New York. Since these plans are standardized by the federal government, your benefits remain identical regardless of your new zip code. You simply notify your insurance carrier of your new address. They will adjust your monthly premium based on the local rates in your new home state for the 2026 calendar year.
Is there a high-deductible version of Plan G available in 2026?
Yes, there is a High-Deductible Plan G available for 2026 with a set calendar year deductible of $2,950. This version offers much lower monthly premiums, often starting around $91 per month for Nassau County residents. It’s an excellent option if you want to protect yourself against catastrophic costs while keeping your monthly fixed expenses low. This Medicare supplement guide to plan G in Massapequa NY helps you determine if the lower premium is worth the higher initial out-of-pocket cost.
Article by
Paul Barrett
Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.
He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.
📞 631-358-5793 | paulbinsurance.com