
Last October, a client named Mary discovered that her long-time primary care doctor was leaving her plan network just as her monthly medication costs were set to rise. Like many of us, she felt a wave of anxiety while staring at a mountain of conflicting insurance mailers. It’s a common struggle, and it’s why having a reliable medicare annual election period checklist is so vital. You deserve to know that your healthcare remains secure without having to decode complex industry jargon or high-pressure advertisements.
I understand how overwhelming this season feels, especially with the 2026 standard Part B premium rising to $202.90 and significant shifts in how prescriptions are billed. I’m here to replace that confusion with a clear, step-by-step path to certainty. I’ll show you exactly how to audit your current coverage, verify your 2026 drug costs under the new $2,100 out-of-pocket cap, and ensure your preferred doctors are still by your side. By the time you reach the December 7th deadline, you’ll have the peace of mind that comes from knowing you didn’t miss a better option for your health or your wallet.
Key Takeaways
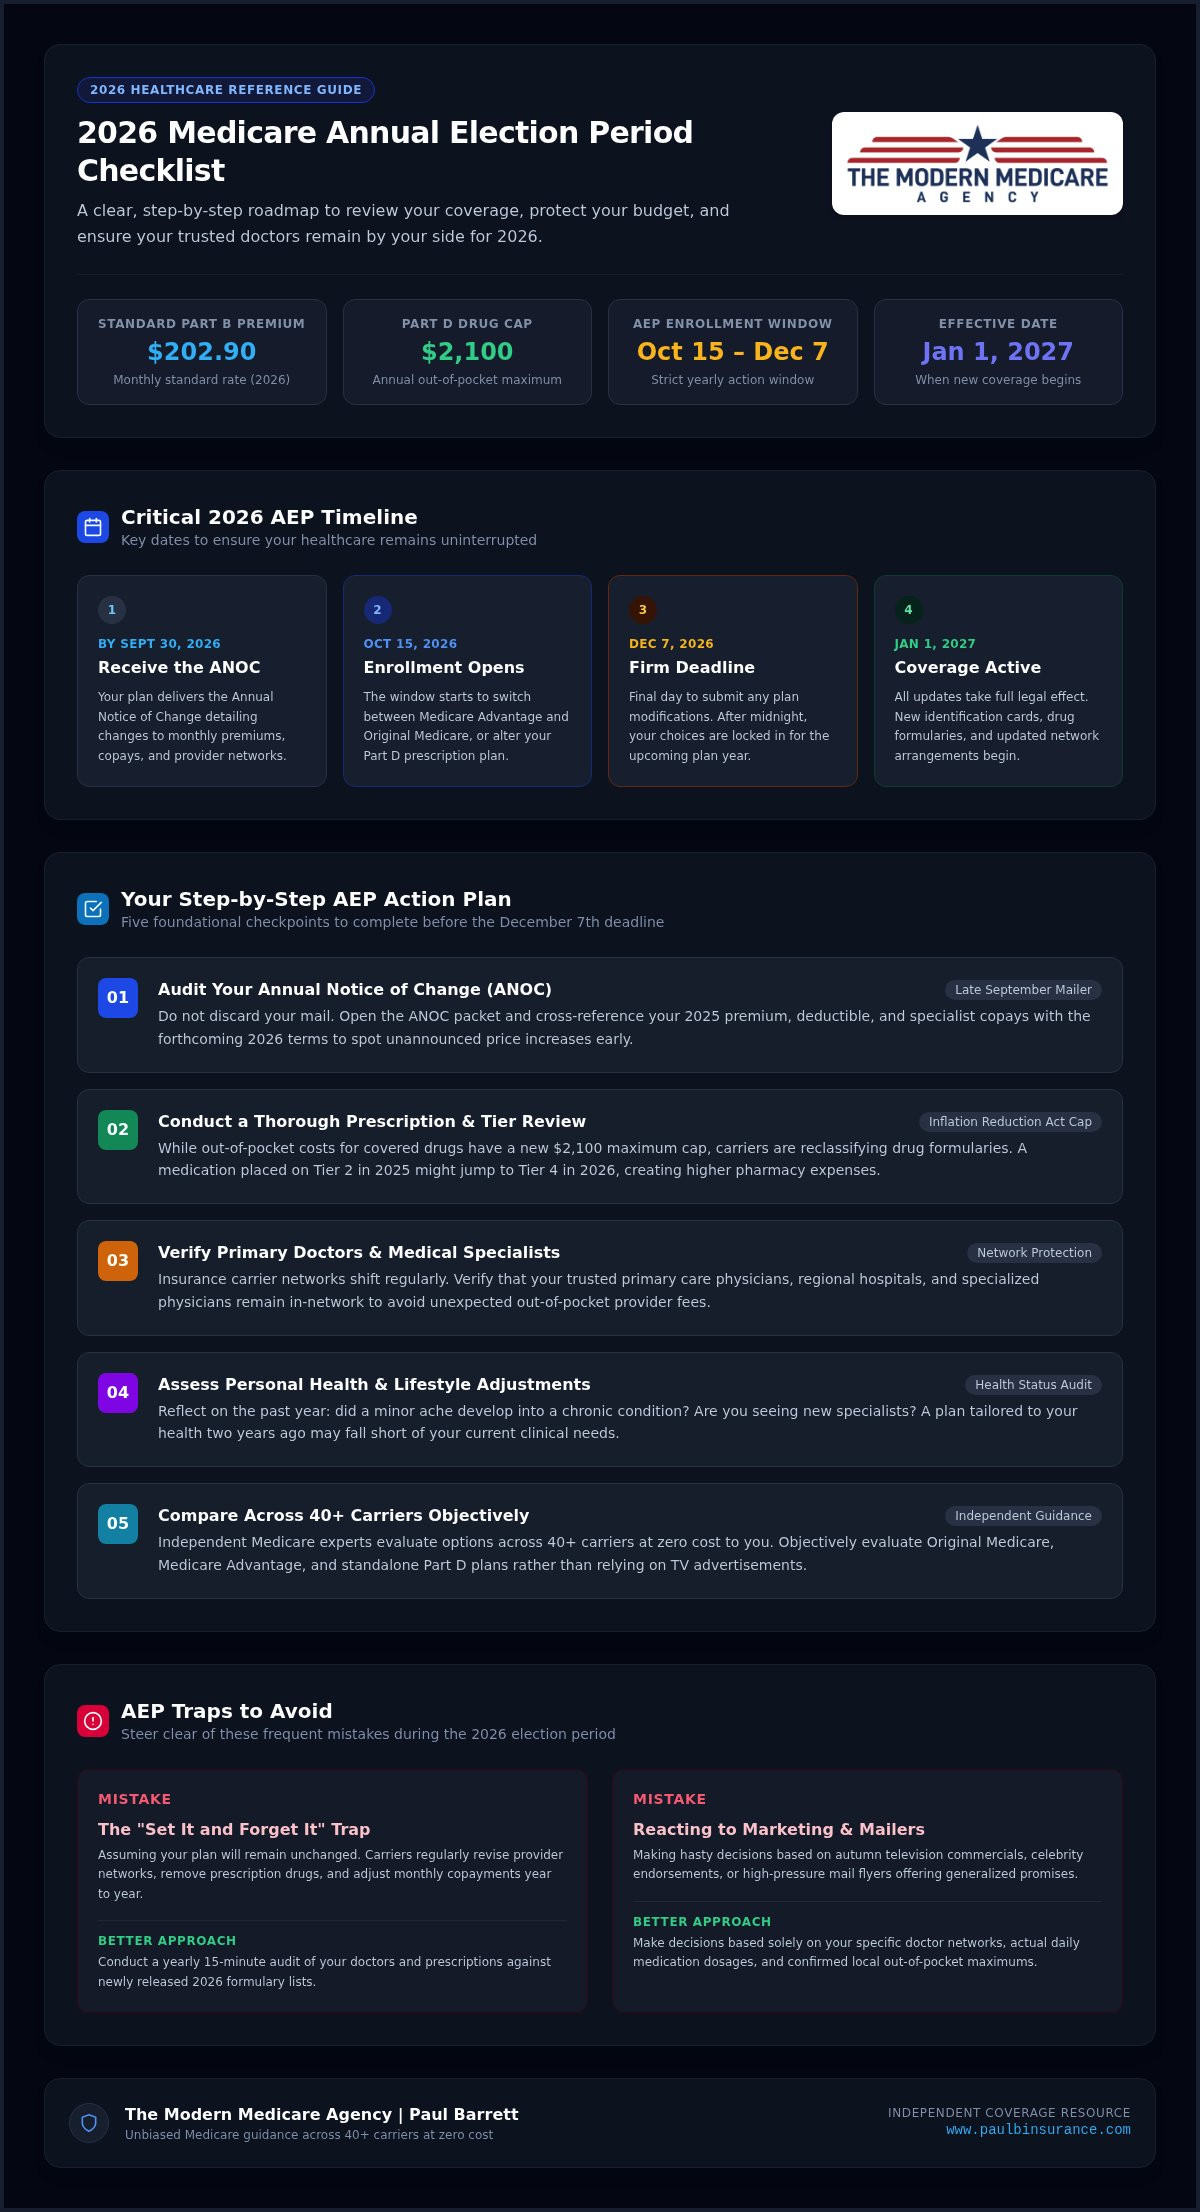
- Mark your calendar for the October 15th to December 7th enrollment window to ensure your 2026 coverage is locked in and ready for the new year.
- Use our 2026 medicare annual election period checklist to review your Annual Notice of Change and identify hidden shifts in premiums or drug tiers.
- Verify that your preferred doctors and medications are still covered to avoid the “set it and forget it” trap that leads to higher out-of-pocket costs.
- Confirm how the new 2026 Part D out-of-pocket maximum affects your specific prescriptions to ensure your healthcare remains truly affordable.
- Discover how an independent expert provides unbiased comparisons across 40+ carriers at zero cost, focusing entirely on your unique needs.
Navigating the 2026 Medicare Annual Election Period (AEP)
The Medicare Annual Election Period is your yearly opportunity to take back control of your healthcare. While your initial enrollment period was your entry point into the Medicare program overview, AEP is different. It’s a structured window from October 15th to December 7th, 2026, where you can switch plans to better fit your current life. Whether you want to move from Original Medicare to a Medicare Advantage plan or simply want to find a more affordable drug plan, this is your time to act. Changes you make during this window will go into effect on January 1, 2027.
During this period, keeping your coverage organized is vital. Working with experts like The Modern Medicare Agency helps ensure you navigate these updates smoothly. We have seen significant shifts in how prescription drugs are covered, and staying on the same plan just because it’s familiar could be a costly mistake. My goal is to help you move from a place of uncertainty to a state of total confidence. We’ll do that by looking at the facts and ignoring the flashy advertisements.
Why This Year Requires a Closer Look
Recent healthcare updates mark a major milestone in prescription drug cost protections. Thanks to the Inflation Reduction Act, the annual out-of-pocket maximum for covered drugs is capped at $2,000 for the year. This is a huge win for your wallet, but it has also caused insurance carriers to restructure their Medicare Part D plans. You might find that your current plan has changed its drug list or how it groups different medications for the upcoming year.
By September 30th, you should have received your Annual Notice of Change (ANOC). This letter is the first item on your medicare annual election period checklist. It tells you exactly how your premiums, copays, and doctor networks will change for the upcoming year. Because carrier networks shift frequently, checking this document ensures you don’t lose access to the doctors you trust. If your favorite specialist is no longer in-network, AEP is your chance to find a plan that still includes them.
The Emotional Journey of AEP
It’s hard to ignore the flood of TV commercials and mailers that arrive every autumn. Most of this marketing noise is designed to create a sense of urgency. I want to help you tune that out. Transitioning from confusion to clarity starts with a structured plan. Instead of reacting to a celebrity endorsement, you can follow a logical process that puts your needs first. This medicare annual election period checklist simplifies the complex. It turns a month of potential stress into a few simple tasks that protect both your health and your retirement savings.
Step 1: Your Personal Coverage Audit for 2026
The first step in your medicare annual election period checklist is to open the mail you’ve been avoiding. By late September, your current plan sent you an Annual Notice of Change (ANOC). Think of this as a summary of how your relationship with your insurance company is changing for the next year. It’s not just a formality. It’s a detailed comparison of your 2025 benefits against what’s coming in 2026. Look specifically for the table that lists your monthly premium, your deductible, and your copays for office visits. If you see a price hike, don’t panic. You have options.
Beyond the paperwork, take a moment to reflect on your physical health. Have you started seeing a new specialist? Did a minor ache turn into a chronic condition that requires more frequent visits? Your needs are rarely static. A plan that was perfect when you signed up might be falling short now. Checking the Medicare plan enrollment rules ensures you understand how to move to a plan that aligns with your current reality.
The Medication Review
Prescription drug coverage is undergoing its biggest transformation in years. While the $2,100 out-of-pocket cap is a great safety net, insurance carriers are adjusting their formularies to compensate. A drug that was on “Tier 2” in 2025 might jump to “Tier 4” in 2026, significantly increasing your monthly bill at the pharmacy counter. I recommend writing down every medication and dosage you currently take. You can then use our guide on Medicare Part D Explained to see if your current plan still offers the best value. It’s often helpful to have an independent eye look at these lists to spot potential savings you might miss on your own.
Checking Your Doctor List
Provider networks are the most common reason people choose to switch plans. Doctors and hospital systems frequently negotiate new contracts, and sometimes they decide to leave a network entirely. Checking your provider network is a critical item on your medicare annual election period checklist because networks change every year. Don’t rely on the directory you received three years ago. You should verify that your “must-have” specialists are still participating for the upcoming year. Sometimes plans have “ghost networks” where a doctor is listed but isn’t actually taking that insurance anymore. A quick call to the doctor’s office is the safest way to confirm. If you find your doctor is out, you can explore other Medicare Advantage Plans 2026 that still include your preferred providers. If you feel stuck, our team at The Modern Medicare Agency can run a quick comparison to find a match that keeps your care team intact.
The Essential 2026 Medicare AEP Checklist
Now that you’ve audited your current health needs, it’s time to put that knowledge into action. A successful medicare annual election period checklist isn’t just about checking boxes. It’s about ensuring your 2027 coverage reflects the reality of your life today. With the 2026 Part D out-of-pocket maximum set at $2,100, you have a stronger safety net than ever before. However, this cap only works for you if your specific medications are on the plan’s list of covered drugs. When evaluating Medicare coverage options, I always recommend comparing your current plan against at least three 2026 alternatives. This “rule of three” often reveals better pricing or broader doctor networks you might have otherwise missed.
Don’t overlook the smaller details that impact your daily life. Is your favorite local pharmacy still considered “preferred” in your 2026 plan? If they’ve moved to a “standard” status, your copays could double overnight. Scheduling a quick review with an independent advisor can help you catch these hidden traps. We look at the fine print so you don’t have to. Our goal is to protect your budget and your peace of mind.
Maximizing Your 2026 Benefits
Many 2026 plans offer “extra” benefits like flex cards for over-the-counter (OTC) items or gym memberships. While these are great perks, they shouldn’t be the only reason you pick a plan. It’s vital to weigh a low monthly premium against a high maximum out-of-pocket (MOOP) limit. If you have a major health event in 2026, a $0 premium plan with a high MOOP could end up being more expensive than a plan with a modest premium. If your plan’s dental coverage feels thin, you can always look into standalone Dental Insurance Plans to bridge the gap. This ensures you get the care you need without sacrificing your choice of dentist.
The Medigap Exception
It’s a common misunderstanding that AEP is the time to change your Medicare Supplement insurance. In reality, AEP is primarily for switching between Medicare Advantage and Part D plans. If you are looking for a Simple Guide to Medigap, you’ll find that these plans don’t have an annual open enrollment window in most states. You can technically apply to switch your Medigap plan at any time, but you might have to answer health questions. However, if you’re currently on an Advantage plan and want to return to Original Medicare with a Supplement, AEP is your window to make that move for January 1st. It’s a big decision, and I’m here to help you navigate that transition safely.
Avoiding Common Mistakes During AEP
One of the biggest risks during the autumn enrollment season is falling into the “Set It and Forget It” trap. You might feel that because your plan worked well in 2025, it’s safe to let it renew automatically for 2026. This passive approach can cost you thousands of dollars. Insurance companies change their terms every single year, and your medicare annual election period checklist is your shield against these unexpected costs. If you miss the December 7, 2026, deadline, you’re usually locked into your current plan for the entire next year, even if your favorite doctor has left the network or your pharmacy costs have doubled.
Another common pitfall is assuming your spouse’s plan is the best fit for you. Healthcare is deeply personal. Your spouse might prioritize a specific dental benefit, while you might need coverage for a specialized medication or a specific cardiologist. Don’t let marketing noise or celebrity endorsements sway you. Those ads are designed to sell a product, not to provide a comprehensive review of your specific health needs. You deserve a plan tailored to you, not a generic solution from a television commercial.
The Danger of Incomplete Comparisons
Many people make the mistake of looking only at the monthly premium. While a $0 premium plan sounds attractive, you must look at the total cost of care. This includes checking how “Prior Authorization” rules have shifted for 2026. Some plans have added new requirements that mean you’ll need insurance company approval before starting certain treatments or seeing specific specialists. You also need to review the formulary carefully. A formulary is the list of covered drugs your plan agrees to pay for. If your medication drops to a lower tier or off the list entirely, your out-of-pocket costs will spike regardless of the premium price.
The “Captured Agent” vs. Independent Broker
When you call a 1-800 number from a glossy mailer, you’re often speaking to a “captured” agent. These representatives work for one insurance company and can only sell that company’s products. They can’t tell you if a competitor has a better network or lower drug costs because they simply don’t have access to those plans. An independent broker, like our team at The Modern Medicare Agency, represents 40+ carriers. We can show you these options side-by-side to ensure you’re getting the best possible value for 2026. You can learn more about this in our guide on Finding a Trusted Medicare Broker. We work for you, not the insurance company, and our goal is your peace of mind. Schedule your zero-cost 2026 plan review today to make sure you aren’t leaving money on the table.
Finding Peace of Mind: How Paul Barrett and The Modern Medicare Agency Help
Completing your medicare annual election period checklist is a major accomplishment, but you don’t have to carry that weight alone. I know that the flood of information in 2026 can feel like a heavy burden. My role as an independent broker is to lift that pressure off your shoulders. Unlike “captured” agents who only show you what a single company offers, we look at the entire market. We represent over 40 health insurance carriers, which means we aren’t here to push a specific brand. We’re here to find the one plan that fits your life, your medications, and your budget for the coming year.
You might wonder how we provide this level of detailed, personalized service at zero cost to you. It’s a fair question. Our compensation comes directly from the insurance carriers. Because of this, you never pay a fee for our advice or comparisons. Whether you choose a Medicare Advantage plan, a Medigap policy, or a standalone Part D plan, you get the same price you would if you went directly to the company. The difference is that you have a dedicated expert in your corner who knows your history and your health goals.
Your Journey to Certainty
Our Melville-based team follows a methodical process to move you from a state of distress to one of absolute certainty. We start by listening to your concerns about rising 2026 premiums or shifts in your doctor’s network. Then, we use our specialized tools to compare every available option in your area side-by-side. We handle the paperwork and the technical details, making the transition as smooth as possible. We want you to feel protected and empowered. Let’s review your 2026 options together so you can start the new year with a clear, affordable plan.
Licensed Support Across the Country
While our roots are in Melville, we are licensed in over 34 states. This allows us to bring localized expertise to clients across the country. Our support doesn’t end when the medicare annual election period checklist is finished on December 7th. If you face a coverage issue or a billing question in the middle of 2026, we are your first call. We act as your advocate to resolve problems with the insurance companies directly. You aren’t just getting a plan; you’re getting a partner who cares about your health and financial security. Schedule your 2026 AEP Review with Paul Barrett today to secure the coverage you deserve.
Take Control of Your 2026 Healthcare Journey
The transition into 2026 brings significant changes to how your medications are covered and how your doctors are networked. By using this medicare annual election period checklist, you’ve already taken the first step toward protecting your health and your retirement savings. Remember that the December 7th deadline is your final opportunity to ensure your plan aligns with the new $2,100 out-of-pocket drug cap and your specific provider needs. You don’t have to face these complex decisions alone or settle for limited options from a single insurance carrier.
At The Modern Medicare Agency, we offer independent, unbiased advice across more than 40 carriers to give you the full picture. Whether you live in New York or one of the 34 other states where we’re licensed, our goal is to move you from a state of uncertainty to one of total confidence. We invite you to Get your personalized 2026 Medicare AEP Checklist and Review today with Paul Barrett at no cost to you. You deserve the peace of mind that comes from knowing your coverage is built specifically for your life. Let’s make 2026 your most secure year yet.
Frequently Asked Questions
When exactly is the Medicare Annual Election Period for 2026?
The Medicare Annual Election Period for 2026 begins on October 15th and ends on December 7th. This is the designated window where you can add, drop, or switch your Medicare Advantage and Part D plans. Any changes you make during this time will become effective on January 1, 2027. It’s the most critical time of year to use a medicare annual election period checklist to ensure your coverage remains affordable.
Can I switch from Medicare Advantage back to Original Medicare during AEP?
Yes, you can switch from a Medicare Advantage plan back to Original Medicare during the AEP window. If you make this choice, you’ll also have the option to enroll in a standalone Part D prescription drug plan. It’s a significant move that requires careful thought about how you’ll cover the gaps in Original Medicare, such as the 20% coinsurance for Part B services. We can help you weigh these options side-by-side.
What happens if I miss the December 7th deadline for 2026?
If you miss the December 7th deadline, your current 2026 plan will typically lock in for the entirety of 2027. You generally won’t be able to make changes until the next AEP unless you qualify for a Special Enrollment Period. However, if you’re already on a Medicare Advantage plan, you can use the Open Enrollment Period from January 1st to March 31st to make a one-time switch or return to Original Medicare.
Does it cost anything to work with a Medicare broker like Paul Barrett?
It costs you absolutely nothing to work with our team at The Modern Medicare Agency. As independent brokers, our compensation is paid directly by the insurance carriers. You’ll pay the exact same premium for your plan whether you enroll through us or directly with the company. The advantage of working with us is receiving unbiased guidance across 40+ carriers and having a dedicated advocate to help you through the year.
Will my current Medicare Advantage plan automatically renew for 2026?
Most Medicare Advantage plans will automatically renew for the following year as long as the carrier continues to offer that specific plan in your area. While this sounds convenient, it’s often a trap. Plans frequently change their doctor networks and drug lists. Even if your plan renews, your costs or access to care might look very different in 2027. That’s why a proactive review is so important every single autumn.
How do the 2026 Part D changes affect my prescription drug costs?
The biggest change for 2026 is the $2,100 annual out-of-pocket maximum on covered prescription drugs. Once you reach this limit, you’ll have a $0 copay for your covered medications for the rest of the year. This provides incredible financial security if you take high-cost maintenance drugs. However, because of this cap, many plans are changing which drugs they cover and how much you pay before reaching that limit.
Can I change my Medigap (Medicare Supplement) plan during the AEP?
AEP is primarily for Medicare Advantage and Part D plans, not Medigap. You can technically apply to change your Medigap plan at any time during the year. However, in most states, you’ll have to answer health questions and go through medical underwriting. This means a new carrier could deny you or charge more based on your health history. It’s a complex process that we can help you navigate safely.
What should I look for in my Annual Notice of Change (ANOC) letter?
You should look for changes in your monthly premium, your annual deductible, and your maximum out-of-pocket limit. Pay close attention to the “formulary” section to see if your medications have changed tiers or been removed. Also, check for any shifts in the provider network. If your doctor is no longer listed, you’ll need to use your medicare annual election period checklist to find a new plan that includes your healthcare team.
Article by
Paul Barrett
Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.
He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.
📞 631-358-5793 | paulbinsurance.com