Medicare Coverage for Preventive Care in 2026: What’s Included?

Medicare Coverage for Preventive Care in 2026: What’s Included?

What if a preventive visit is covered but leads to a bill? In 2026, Medicare coverage for preventative care depends on the service, your eligibility, how often you’ve received it, and whether the appointment includes diagnostic care. Knowing what’s planned can help you understand the possible costs before you go.

If you’re unsure which services Medicare covers, or whether Original Medicare and Medicare Advantage follow the same rules, you’re not alone. Coverage can depend on details that are easy to miss, such as why a test is being done or when you last had it.

This guide explains common types of preventive care Medicare may cover, how eligibility and timing affect coverage, and why follow-up tests or treatment may be billed differently. You’ll also find practical steps for reviewing Medicare and plan information before an appointment.

Key Takeaways

  • Preventive care can help prevent illness or identify health risks early, but eligibility and timing rules matter in 2026.
  • Medicare may cover qualifying wellness visits, screenings, counseling services, and vaccines.
  • A preventive service may still lead to costs if follow-up care is billed as diagnostic or the service doesn’t meet coverage rules.
  • Use Medicare.gov to check a service’s current eligibility and frequency rules before your appointment.
  • Original Medicare and Medicare Advantage cover eligible preventive services, but provider participation and plan procedures can affect how you access care.

What Does Medicare Coverage for Preventive Care Mean in 2026?

To understand whether a preventive service may be covered, start with two questions: Do you meet the eligibility rules, and are you due for the service? Preventive care includes services intended to help prevent illness or identify health risks early, such as certain screenings and wellness visits. In 2026, Medicare’s rules for each service determine whether it qualifies for preventive coverage.

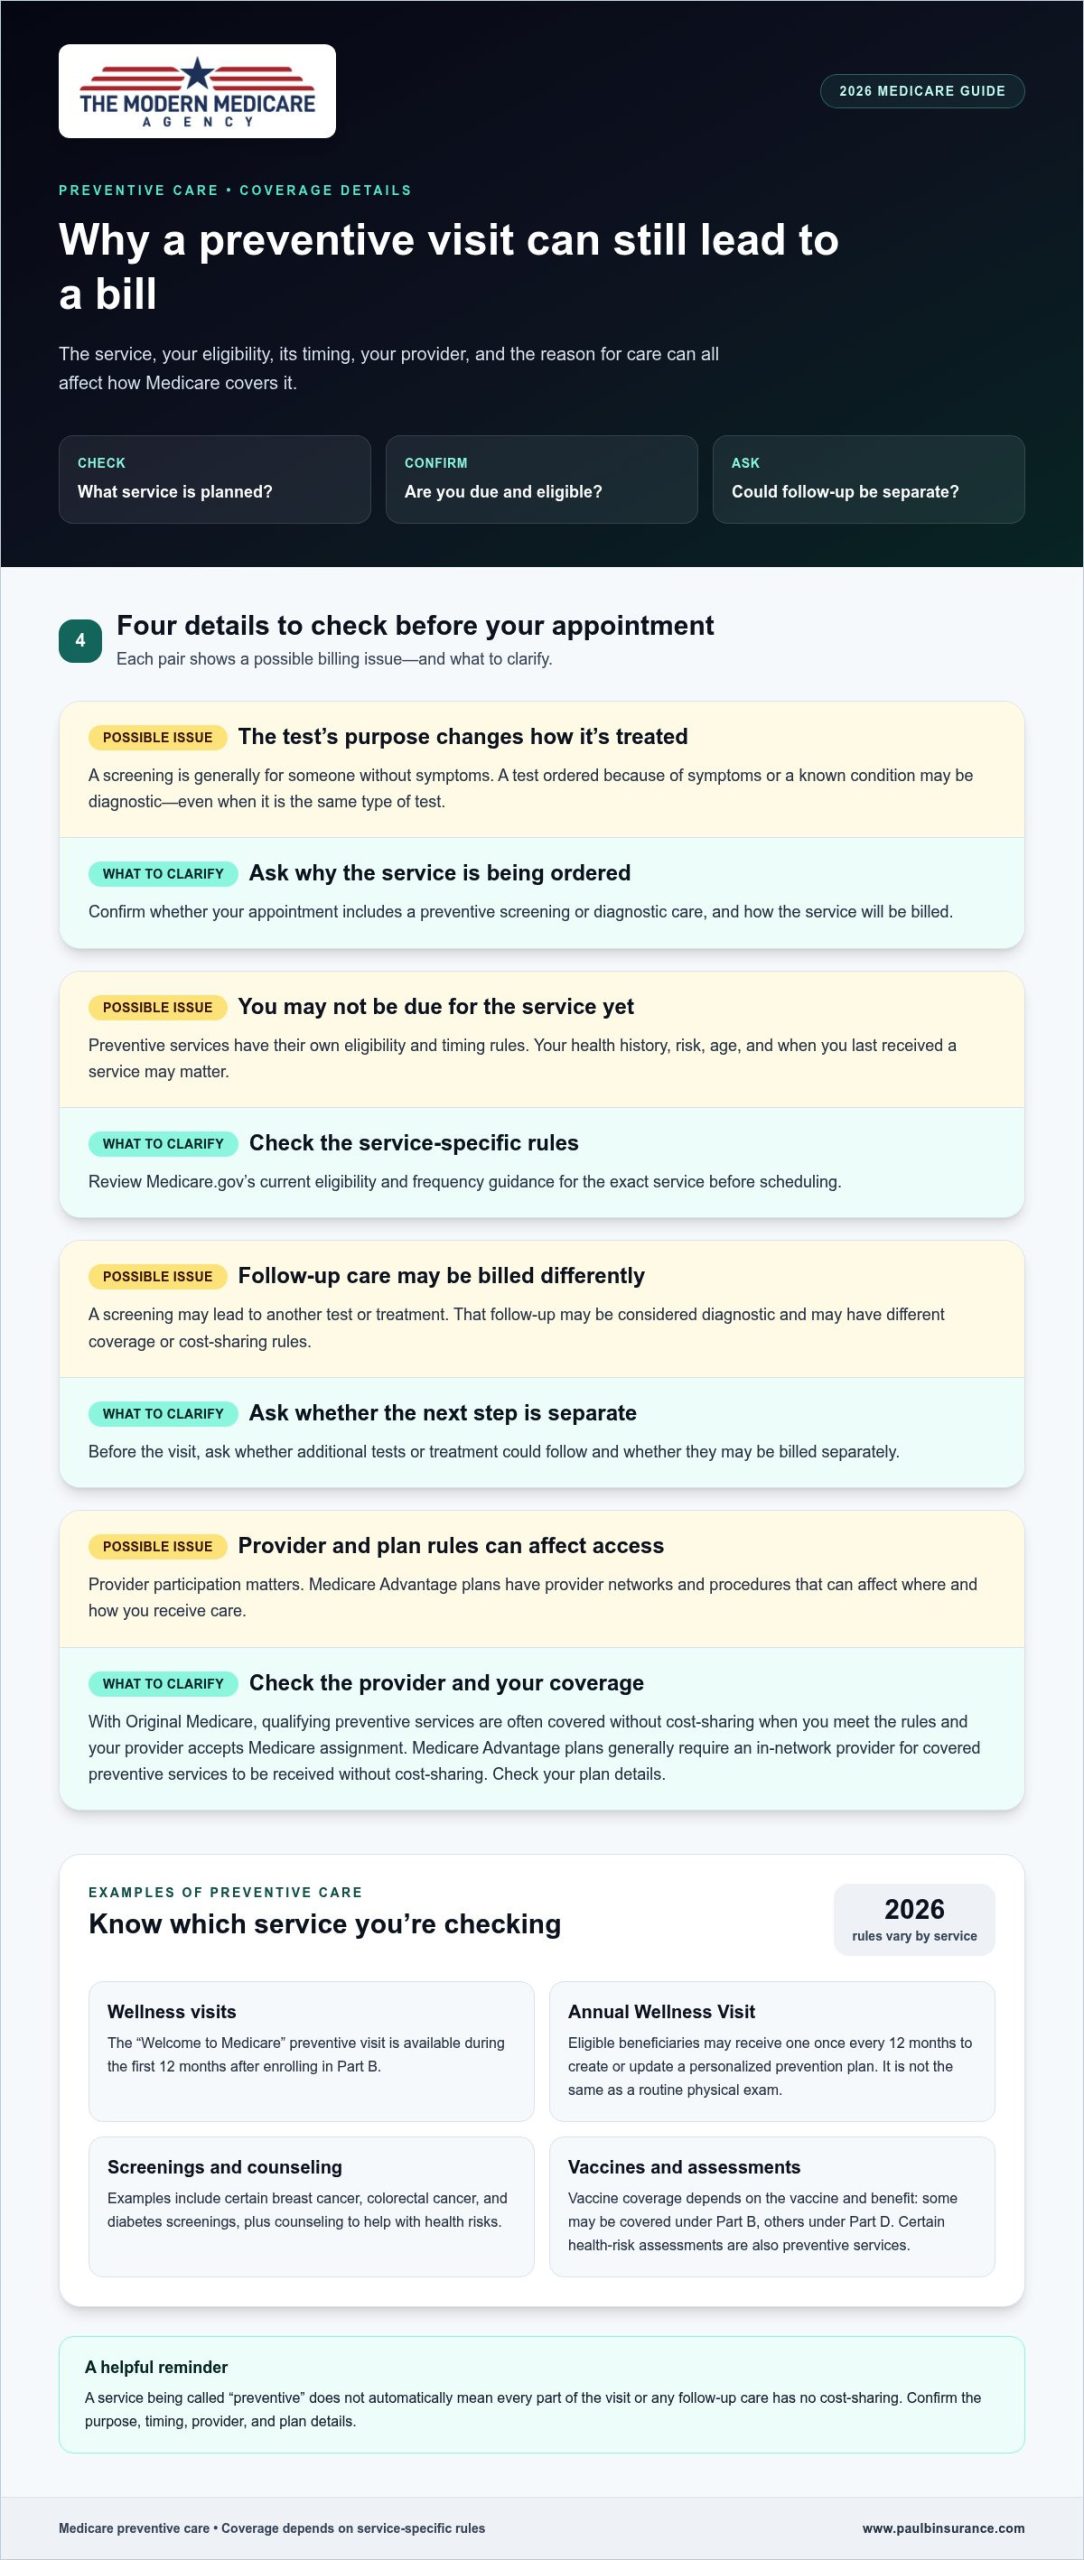
“Covered” doesn’t always mean every part of an appointment is free. Medicare may cover an eligible preventive service under specific conditions, while another service during the same visit or care that follows may be billed differently. The details of medicare coverage for preventative care depend on the service, your circumstances, and how the care is provided and billed.

How preventive care differs from diagnostic care

A screening is generally intended for someone without symptoms, to look for a health concern early. When a test is ordered because of symptoms or a known condition, it may instead be considered diagnostic. The same type of test can have a different purpose depending on why it’s ordered.

A screening can also lead to a separate diagnostic service. For example, if a screening finds something that needs closer examination, the next test or treatment may have different coverage and cost-sharing rules. Before your appointment, ask what service is planned and whether follow-up care could be billed separately.

Original Medicare and Medicare Advantage at a glance

Original Medicare includes Part A, which generally covers inpatient hospital care, and Part B, which covers doctor visits and many outpatient services, including preventive care. The Medicare program also includes other parts, but Parts A and B are the starting point for understanding these services.

Medicare Advantage plans cover Medicare-covered Part A and Part B services. Their provider networks and procedures can affect where and how you access care. Check your plan information alongside Medicare’s service-specific guidance to understand which providers you can use and what steps may apply.

Look beyond the word “preventive.” Confirm the service’s purpose, whether you meet its eligibility and timing rules, and whether follow-up care could be treated separately. These details give you a clearer basis for discussing coverage and possible costs before the appointment.

Which Preventive Services Can Medicare Cover?

Medicare’s preventive benefits include several kinds of care, but each service has its own coverage rules. In 2026, eligibility may depend on factors such as your health history, risk, age, and when you last received the service. Start with the Preventive services covered by Part B page to review the current list and service details.

Medicare preventive coverage varies by service, including who qualifies and how often the service may be covered. Use the examples below to identify common categories, then check Medicare.gov for the specific rules that apply to you.

Wellness visits, screenings, and counseling

Medicare offers a “Welcome to Medicare” preventive visit during the first 12 months after you enroll in Part B. After that, eligible beneficiaries may receive an Annual Wellness Visit once every 12 months to create or update a personalized prevention plan. This visit is not the same as a routine physical exam, so don’t assume it includes a full head-to-toe examination.

Other examples include certain screenings for breast cancer, colorectal cancer, and diabetes, as well as counseling to help with health risks. Each service has its own eligibility and timing rules. A screening for someone without symptoms may be treated differently from a test ordered to investigate a concern. Before scheduling, confirm which service is planned and whether you meet its criteria.

Vaccines and other preventive services

Vaccine coverage depends on the vaccine and which Medicare benefit applies. Some vaccines may be covered under Part B, while others may fall under Part D, the prescription drug benefit. That distinction can affect where and how you receive a vaccine. Check current Medicare.gov vaccine guidance and your plan details rather than assuming every vaccine follows the same rules.

Medicare’s preventive benefits also include services such as certain health-risk assessments. The service, eligibility requirements, and covered timing can vary. A listed preventive benefit doesn’t automatically mean related visits, tests, or follow-up care will have no cost-sharing.

To understand how medicare coverage for preventative care may work with your plan, compare Medicare’s service rules with your plan’s provider network and coverage details. This can help you prepare questions about access and possible costs. You can also review Medicare plan options as part of understanding how your coverage fits your needs.

When Might Medicare Preventive Care Still Lead to a Bill?

Preventive care isn’t automatically free in every circumstance. In 2026, the service, your eligibility, how recently you received it, the provider, and the reason for care can all affect what you owe. Original Medicare often covers qualifying preventive services without cost-sharing when you meet the rules and your provider accepts Medicare assignment. Medicare Advantage plans generally require you to use in-network providers for covered preventive services to receive them without cost-sharing. Other situations may involve costs.

How a service is billed can affect whether you owe money, even when the appointment begins with preventive care.

Preventive screening: A routine screening for someone without symptoms may qualify for preventive coverage if you meet the eligibility and timing rules.

Diagnostic follow-up: If a screening result needs further investigation, the next test or treatment may be billed as diagnostic care, with different cost-sharing rules.

Unrelated additional care: A separate concern addressed during the same appointment may be billed as another service rather than as part of the preventive screening.

Preventive screening versus diagnostic follow-up

The same test can serve different purposes. A test used to screen someone without symptoms may be preventive. If you have symptoms, a prior abnormal finding, or a concern that needs evaluation, the test may be diagnostic instead. The Medicare Rights Center’s list of Medicare-covered preventive services offers more context on how preventive and diagnostic care can differ.

If a screening could lead to another test or procedure, ask the provider how that follow-up is expected to be billed. When possible, check with your plan about applicable coverage and cost-sharing before the service. Coverage for a screening doesn’t guarantee that every next step will have the same terms.

How Original Medicare and Medicare Advantage may differ

Original Medicare and Medicare Advantage administer coverage differently. With Original Medicare, coverage depends on Medicare’s rules and provider participation. Medicare Advantage plans cover Medicare-covered Part A and Part B services, but their networks and procedures can affect where and how you receive care. Getting care from a provider outside your plan’s network may change your costs or access, depending on the plan’s terms.

For a broader look at how plan networks and rules work, explore this Medicare Advantage guide. Understanding your plan can help you ask clearer questions before an appointment and make sense of how medicare coverage for preventative care applies to you.
Medicare Coverage for Preventive Care in 2026: What’s Included?

How to Check Preventive-Care Coverage Before an Appointment

A little preparation can help you understand how a service may be covered and reduce the chance of surprises. In 2026, review current Medicare guidance and your plan information. Eligibility, timing, and provider rules can vary by service and coverage type.

A simple checklist for your next visit

  • Name the exact service. Find out whether the appointment is for a preventive screening, a wellness visit, or a test to investigate a symptom or known concern.
  • Check Medicare’s current rules. Look up the service on Medicare.gov and review its eligibility criteria and how often it may be covered. Consider whether your health history or the date of your last service affects eligibility.
  • Confirm provider participation. With Original Medicare, check whether the provider accepts Medicare assignment. With Medicare Advantage, review your plan’s network and any procedures that apply to the service.
  • Ask about next steps. Find out whether additional tests, treatment, or other care could be billed separately if the screening identifies a concern.

These steps can help you understand how medicare coverage for preventative care may apply before you arrive. Keep notes about what you checked and any information the provider or plan gives you.

What to do if a bill seems unexpected

Compare the bill with the provider’s explanation of the services provided. If you have Original Medicare, review your Medicare Summary Notice, which shows claims Medicare processed and the amount you may owe. If you have Medicare Advantage, check the statement from your plan. The service description and billing classification can help explain a charge.

If something doesn’t make sense, ask the provider to explain what was billed and whether it was classified as preventive or diagnostic care. For questions about how a claim was processed, use the official Medicare or plan contact information shown on your notice or member documents.

If you’d like broader context on how plan networks and coverage work, read this Medicare Advantage plan overview. You can also discuss how your Medicare plan fits your needs as you consider access to preventive care.

Make Medicare Preventive Coverage Easier to Understand

In 2026, start with four details: the service, your eligibility, when you last received it, and whether follow-up care may be billed separately. These details can help you prepare for an appointment and ask clearer questions about possible costs. Medicare.gov is the place to confirm official service rules. Your plan information can explain how your specific coverage works, but it doesn’t replace Medicare’s rules.

When a plan conversation may help

If you’re unsure whether a provider is in your plan’s network or how your plan handles a service, reviewing your plan details can clarify how you access care and what procedures may apply. The Modern Medicare Agency is an independent brokerage that helps eligible individuals compare Medicare Advantage, Medigap, and Part D options from multiple carriers, with guidance tailored to their needs.

If you have Original Medicare and are exploring supplemental coverage, the Medigap guide offers more context. A plan conversation can help you understand coverage choices, while official Medicare resources remain the source for service eligibility and coverage rules.

A calm next step for 2026

Before your next appointment, make a short list of the preventive services you’re considering and the questions you want answered. Note when you last received each service, whether the provider participates in your coverage, and what could happen if a screening leads to more care. Having those details together can make it easier to discuss coverage without feeling rushed.

Understanding medicare coverage for preventative care doesn’t require you to sort through every detail alone. Use Medicare.gov to confirm official service rules, then review your plan documents or contact your plan with questions about its network, procedures, or a specific claim. The Modern Medicare Agency helps people compare Medicare plan options and understand how they fit their needs. If personal guidance would help, request help reviewing your Medicare plan options.

Take the Next Step With More Confidence

In 2026, understanding medicare coverage for preventative care starts with checking the service, your eligibility, and when you’re due for it. A preventive screening and diagnostic follow-up may be treated differently, and your plan’s provider network or procedures can affect how you access care.

Use Medicare’s official resources to confirm service rules, then review your plan details if you have questions about providers or coverage. The Modern Medicare Agency is an independent brokerage that helps people compare Medicare options from more than 40 carriers, with personalized guidance and year-round support across more than 34 states. The agency can help you understand plan options, while Medicare remains the source for official service rules.

For help reviewing your options, explore personalized Medicare plan guidance. The Modern Medicare Agency can help you compare Medicare Advantage, Medigap, and Part D options. Reach out to discuss which plan options fit your needs.

Frequently Asked Questions

Does Medicare cover preventive care at no cost?

Some qualifying preventive services may have no deductible or coinsurance, but coverage isn’t automatically free in every situation. With Original Medicare, many preventive services have no cost-sharing when you meet the service’s eligibility and timing rules and your provider accepts Medicare assignment. Medicare Advantage members generally need to use in-network providers for covered preventive services to avoid cost-sharing. Diagnostic follow-up or other care may be billed separately.

What preventive services does Medicare cover in 2026?

Medicare may cover wellness visits, screenings, counseling, and certain vaccines in 2026. Examples include the Welcome to Medicare visit, the Annual Wellness Visit, and eligible screenings for breast or colorectal cancer and diabetes. A standardized physical activity and nutrition assessment may also be part of an Annual Wellness Visit every six months. Eligibility and frequency vary by service, so check current Medicare.gov guidance for the specific benefit.

Is a Medicare wellness visit the same as a physical?

No. The Annual Wellness Visit helps you create or update a personalized prevention plan, but it isn’t a traditional physical exam. It focuses on your health history, risk factors, and preventive-care needs. If you want a routine physical, clarify that with your provider before the appointment, since it may be billed differently from a covered wellness visit. The Welcome to Medicare visit is a separate initial preventive appointment.

Can Medicare charge me for a preventive screening?

Yes, you may owe costs in some circumstances. The service might not meet Medicare’s eligibility or frequency rules, the provider may not accept Medicare assignment, or the screening may lead to diagnostic testing or treatment. The service’s purpose matters too: a test prompted by symptoms or a previous finding may be billed as diagnostic rather than preventive. Ask how planned follow-up care will be billed.

Does Medicare Advantage cover preventive care?

Yes. Medicare Advantage plans cover services covered under Medicare Parts A and B, including eligible preventive services. However, the plan’s network and procedures can affect how you access care. Check your plan documents or member resources to confirm provider participation and any plan-specific requirements for the service. If you receive care outside the network or need follow-up services, coverage and costs may differ under your plan’s terms.

Are vaccines covered by Medicare preventive benefits?

Some vaccines are covered by Medicare, but the applicable benefit depends on the vaccine. Coverage may fall under Part B or Part D, Medicare’s prescription drug benefit, and the rules can differ. Don’t assume that every vaccine is covered in the same way or at the same location. Check current Medicare guidance and your plan details for the vaccine you’re considering, including where it may be covered.

What should I do if Medicare denies a preventive-care claim?

Review your Medicare Summary Notice or, if you have Medicare Advantage, your plan’s statement to see the reason for the denial and the service description. Ask the provider to explain how the service was billed and whether it was classified as preventive or diagnostic. Then contact Medicare or your plan through the official channel shown on your notice. If you disagree, follow the appeal instructions included with the denial.
Paul Barrett

Article by

Paul Barrett

Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.

He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.

📞 631-358-5793 | paulbinsurance.com
What Is Medicare Part B and What Does It Actually Cover?

The complete guide to Medicare’s medical insurance — every service it covers, exactly what it costs in 2026, how it works with group insurance and VA benefits, and the excess charges most people have never heard of until they get a surprise bill.

The Short Answer

Medicare Part B is medical insurance — it covers doctor visits, outpatient care, preventive services, durable medical equipment, and more. Unlike Part A, Part B is not premium-free for anyone: everyone pays a monthly premium (202.90in2026formostpeople),anannualdeductible(283), and 20% coinsurance on most covered services, with no yearly cap on that 20% under Original Medicare alone. Whether you need to enroll at 65, and whether delaying is safe, depends heavily on your employment status and your employer’s size — getting this wrong is one of the most consequential and permanent mistakes in all of Medicare.

Key Takeaways

  • Part B is never premium-free — everyone pays a monthly premium, and higher earners pay significantly more through IRMAA.
  • The 20% coinsurance under Original Medicare alone has no yearly cap — this is the single biggest financial risk in Medicare, and it’s the reason Medigap and Medicare Advantage exist.
  • Whether you can safely delay Part B without a penalty depends on your employer’s size: 20+ employees generally allows delay; fewer than 20 generally does not.
  • Missing your enrollment window triggers a permanent 10% penalty for every 12-month period you went without coverage.
  • Veterans can and generally should enroll in Part B even with VA benefits, since Medicare and VA coverage don’t coordinate — each only pays for care received within its own system.
  • “Excess charges” from non-participating providers can add up to 15% on top of what Medicare approves, and only some Medigap plans protect you from them.

What Part B Actually Covers

While Part A handles hospital room and board, Part B is the half of Original Medicare that covers medical care and most services delivered outside a hospital admission — doctor visits, outpatient procedures, and ongoing medical needs.

What’s covered

  • Doctor visits — primary care and specialists
  • Outpatient surgeries and procedures
  • Diagnostic lab work, X-rays, and MRIs
  • Emergency room visits
  • Ambulance services
  • Outpatient mental health care
  • Physical, occupational, and speech therapy
  • Chemotherapy and radiation received in an outpatient clinic
  • Durable Medical Equipment (DME) — wheelchairs, oxygen equipment, blood sugar monitors, walkers, and similar equipment
  • Ambulatory surgical center services

Preventive services: the part Medicare gets genuinely right

Most preventive services are covered at 100%, with no deductible and no copay, as long as your provider accepts Medicare assignment. This includes:

  • Your one-time “Welcome to Medicare” wellness visit, available within your first 12 months on Part B
  • Annual wellness visits after that
  • Flu shots and most other recommended vaccines
  • Mammograms
  • Colonoscopies and other cancer screenings
  • Diabetes and cardiovascular screenings
  • Many other screenings recommended by the U.S. Preventive Services Task Force

Paul’s Honest Take: This is one of the most underused parts of Medicare, full stop. I’ve had clients who paid for a private physical every year out of habit and never realized their annual wellness visit through Medicare was completely free. If you haven’t used your Welcome to Medicare visit or your annual wellness visit, that’s real value sitting on the table.

What’s NOT covered

  • Routine dental care — cleanings, fillings, dentures, extractions
  • Routine vision exams and eyeglasses
  • Hearing aids (though diagnostic hearing tests ordered by a doctor may be covered)
  • Long-term custodial nursing home care — help with daily living activities, as opposed to short-term skilled or medical care
  • Routine prescription drugs you pick up at a retail pharmacy — that’s Part D’s job, not Part B’s
  • Cosmetic surgery, unless medically necessary (such as reconstruction after an accident or mastectomy)
  • Most care received outside the United States, with very limited exceptions
  • Routine foot care, such as nail trimming, in the absence of a qualifying medical condition
  • Acupuncture, except for a narrow, specific chronic low back pain benefit
  • Concierge medicine fees and membership-style charges some practices add on top of standard care
  • Long-term care insurance-style services, including most home-based personal care that isn’t tied to a skilled medical need

Paul’s Honest Take: The dental and vision exclusions are the ones that surprise people most, especially since they’re such routine parts of healthcare for most adults. This is exactly why so many Medicare Advantage plans build dental, vision, and hearing benefits into their coverage — Original Medicare was simply never designed to include them, and that gap doesn’t go away on its own.

What Part B Costs in 2026

Part B has three separate cost components, and understanding all three matters:

Cost Component

2026 Amount

Standard monthly premium

$202.90

Annual deductible

$283

Coinsurance on most covered services

20%

The premium is deducted automatically from your Social Security check if you’re already collecting benefits. If you’re not yet collecting Social Security, you’ll receive a bill, typically every three months.

The deductible works differently than Part A’s — it’s a straightforward annual figure. You pay the first $283 of Medicare-approved outpatient costs each calendar year, and then Medicare’s cost-sharing kicks in.

The coinsurance is where the real risk lives. After your deductible is met, Medicare pays 80% of the Medicare-approved amount for most covered services, and you’re responsible for the remaining 20%. There is no yearly cap on this 20% under Original Medicare alone. If you have a $100,000 course of cancer treatment, your 20% share is $20,000 — unless you have a Medigap policy or Medicare Advantage plan absorbing that cost.

Paul’s Honest Take: I put this in bold because it’s genuinely the single most important number in this entire guide. That uncapped 20% is the whole reason Medigap and Medicare Advantage exist as products in the first place. Original Medicare by itself was never designed to protect you from a truly expensive year — it was designed to cover 80% of it and leave the rest to you.

IRMAA: What Higher Earners Actually Pay

If your income is above certain thresholds, you’ll pay more for Part B through the Income-Related Monthly Adjustment Amount (IRMAA) — based on your tax return from two years prior. For 2026, that means your 2024 income determines your premium tier.

2024 Income (Individual)

2024 Income (Married, Joint)

Total Part B / Month

$109,000 or less

$218,000 or less

$202.90

$109,001 – $137,000

$218,001 – $274,000

$284.10

$137,001 – $171,000

$274,001 – $342,000

$405.80

$171,001 – $205,000

$342,001 – $410,000

$527.50

$205,001 – $499,999

$410,001 – $749,999

$649.20

$500,000 and above

$750,000 and above

$689.90

At the top tier, you’re paying more than three times the standard premium. If your income has recently dropped — retirement, the loss of a spouse, or certain other life-changing events — you can appeal your IRMAA determination using Form SSA-44.

Do You Have to Enroll? And What Happens If You Don’t?

Technically, Part B is optional — Medicare won’t force you into it. But opting out without a valid alternative is genuinely risky, because of how the penalty structure works.

If you don’t sign up during your Initial Enrollment Period (the 7-month window around your 65th birthday) and you don’t have qualifying employer coverage, you’ll face a permanent 10% penalty added to your premium for every full 12-month period you went without Part B. That penalty doesn’t expire — you pay it for as long as you have Part B, which for most people means for the rest of your life.

Example: If you delayed enrollment by 24 full months without a valid exception, you’d pay an extra 20% on top of the standard $202.90 premium in 2026 — roughly $40.58 more, every month, permanently.

How Part B Works with Group Insurance

Just like Part A, whether you can safely delay Part B without penalty comes down to one specific number: how many employees your company has.

Companies with 20 or more employees: If you or your spouse are actively working and covered by a genuine group health plan, your workplace insurance is primary, and you can legally delay Part B without any penalty. When that employment or coverage eventually ends, you get an 8-month Special Enrollment Period to enroll in Part B penalty-free.

Companies with fewer than 20 employees: Medicare automatically becomes your primary insurer at 65, regardless of your employment status. You need to enroll in Part B right on schedule. If you don’t, your small employer’s plan can legally refuse to pay claims that Medicare should have covered first — potentially leaving you responsible for the full cost.

Paul’s Honest Take: I say this in nearly every guide I write, because it’s genuinely one of the costliest misunderstandings I encounter: “I have good coverage at work” and “I’m protected from Medicare’s enrollment deadlines” are two completely different statements, and whether the second one is true depends entirely on your employer’s size — not how generous the coverage feels. Confirm the actual employee count before you decide to delay anything.

Retiree Coverage Is Not the Same as Active Employer Coverage

This is a distinction that catches a genuinely large number of people off guard: the “20 or more employees” exception only applies to active employment. If you retire and your former employer offers you retiree health benefits — sometimes a genuinely good, comprehensive plan — that coverage does not create a Special Enrollment Period the way active group coverage does, and it does not exempt you from enrolling in Part B on time.

Paul’s Honest Take: I’ve seen this mistake more than once, and it’s an especially painful one because it happens to people who did everything right during their working years. Someone retires with a strong retiree health plan from a large employer, assumes it works the same way their active coverage did, and delays Part B — only to find out later that retiree coverage was never a valid reason to delay in the first place. The moment you stop actively working, that clock starts, regardless of how good your retiree plan looks on paper. If you’re retiring and keeping employer retiree benefits, treat enrolling in Part B as something to handle right on schedule, not something retiree coverage lets you postpone.

Why You Need Both Part A and Part B for Medigap or Medicare Advantage

Here’s a foundational requirement worth understanding clearly, since it shapes every other coverage decision in Medicare: you must be enrolled in both Part A and Part B before you can buy a Medigap policy or enroll in a Medicare Advantage plan. Neither product exists as a standalone substitute for Original Medicare — both are built specifically to work alongside it.

  • Medigap fills the cost-sharing gaps left by Original Medicare (Parts A and B) — it has nothing to fill in if you’re not enrolled in both parts to begin with.
  • Medicare Advantage legally must provide at least the same coverage as Parts A and B combined, which is only possible because you’re required to be enrolled in both before a Medicare Advantage carrier can enroll you.

Paul’s Honest Take: This surprises people who assume they can somehow “skip” Part B and go straight into a Medicare Advantage plan to avoid the extra premium. It doesn’t work that way — Part B enrollment, and its premium, is a prerequisite either way, whether you end up on Original Medicare with Medigap or on a Medicare Advantage plan. There’s no path through Medicare that avoids the Part B premium once you’re actually using the system.

Does Medicare Work If You’re a Veteran?

Yes — and if you have VA health benefits, understanding how the two systems relate is genuinely important, because they work differently than most people assume.

Medicare and VA benefits do not coordinate. These are two entirely separate systems that each pay only for care received within their own network. Medicare doesn’t pay for care you receive at a VA facility, and VA benefits don’t pay for care you receive from a non-VA doctor or hospital. You, the veteran, choose which system to use each time you seek care.

Here’s the critical point: having VA benefits does not exempt you from Medicare’s enrollment deadlines. VA coverage is not considered a qualifying reason to delay Part B without penalty. If you don’t enroll in Part B during your Initial Enrollment Period and you’re relying solely on VA benefits, you can still trigger the permanent late enrollment penalty.

Why the VA itself recommends enrolling in Medicare anyway:

  • It gives you access to civilian doctors and hospitals outside the VA system
  • VA healthcare funding depends on annual Congressional appropriations, which isn’t guaranteed to remain stable
  • If VA authorizes only part of your needed care at a non-VA facility, Medicare can help cover the rest
  • Having both gives you meaningfully more flexibility and security than relying on either system alone

Paul’s Honest Take: This is one of the most common misconceptions I run into with veterans specifically, and it’s an expensive one to get wrong. Good VA coverage feels like it should be enough, and it might genuinely handle most of your care — but it doesn’t protect you from the Part B enrollment clock the way employer coverage from a large company can. The VA itself actively encourages enrolling in Medicare Parts A and B for exactly this reason. If you have VA benefits and are approaching 65, this is worth a direct conversation before you assume you’re covered.

Veterans who enroll in Part B can also purchase a Medigap policy, which can be particularly valuable if you use non-VA providers regularly — though if you primarily rely on VA facilities for most of your care, the value of an added Medigap policy may be more limited, and worth weighing carefully.

How Long Does It Actually Take to Get Part B Approved?

This is one of the most practical, and most overlooked, pieces of planning — especially if you’re leaving a job after 65 and coordinating your Part B start date around the end of your employer coverage. Applying isn’t instant, and the timeline depends heavily on which enrollment window you’re using.

Enrollment Situation

Typical Processing Time

When Coverage Actually Starts

Initial Enrollment Period (around 65)

2–4 weeks, sometimes up to 6

1st of your birthday month (if applied in the 3 months before) or 1st of the month after you apply (if applied during or after your birthday month)

Special Enrollment Period (leaving employer coverage)

4–8 weeks, sometimes longer

1st of the month after your application is submitted

General Enrollment Period (Jan 1–Mar 31, missed window)

4–6 weeks

1st of the month after you apply

Why the Special Enrollment Period takes longer: applying after leaving employer coverage requires two forms, not one — Form CMS-40B (the actual Part B application) and Form CMS-L564 (Request for Employment Information), which your employer needs to complete to verify you had qualifying coverage. Social Security has to manually review both, which is exactly why this route consistently takes longer than a standard Initial Enrollment Period application.

Paul’s Honest Take: This timeline question comes up constantly with clients who are retiring or leaving a job after 65, and it deserves real attention — not just because of the penalty risk we’ve already covered, but because a slow approval can leave you with an actual gap in coverage if you time it too tightly. My standard advice: start this process at least 2 to 3 months before you need Part B to actually begin, not the week your employer coverage ends. If your former employer is slow to complete their portion of Form CMS-L564, that alone can hold up the entire application — so it’s worth following up with your HR or benefits department directly rather than assuming it’s been submitted.

Practical tips to avoid delays

  • Apply online through SSA.gov whenever possible. It’s consistently the fastest method — mailed or faxed forms are more prone to getting lost or delayed.
  • If you’re on a Special Enrollment Period, submit Form CMS-L564 alongside Form CMS-40B, not separately. They need to arrive together, and one incomplete form can stall the whole application.
  • Expect a short intake lag even with online applications. It can take several business days for an online submission to actually appear on a local Social Security agent’s screen — don’t panic if you call shortly after applying and they say they don’t see it yet.
  • Once approved, you don’t have to wait for your physical card. Your Medicare Beneficiary Identifier typically appears in your online Social Security or Medicare.gov account within a day or two of approval, and you can print a temporary card from there — the physical card generally arrives by mail within about 30 days.

Excess Charges: The Cost Almost Nobody Knows to Ask About

Here’s a detail that surprises even people who’ve been on Medicare for years: not every doctor who accepts Medicare agrees to accept Medicare’s approved amount as full payment.

Providers fall into three categories:

  • Participating providers accept Medicare assignment, meaning they agree to accept the Medicare-approved amount as payment in full. This covers the vast majority of providers — roughly 98% of doctors nationally.
  • Non-participating providers still accept Medicare patients but haven’t agreed to accept the standard rate. They can charge an excess charge of up to 15% above the Medicare-approved amount.
  • Opted-out providers have left the Medicare system entirely and can charge whatever they want under a private contract — Medicare pays nothing at all for care from these providers, except in emergencies.

How excess charges actually work: if the Medicare-approved amount for a service is $300 and you see a non-participating provider, they can legally charge up to an additional $45 (15%) on top, for a total bill of $345 — and that excess amount doesn’t count toward your Part B deductible.

Eight states currently prohibit or limit excess charges entirely: Connecticut, Massachusetts, Minnesota, New York, Ohio, Pennsylvania, Rhode Island, and Vermont. If you live in one of these states, you’re generally shielded from excess charges from providers within your state — though you could still face them if you receive care from a non-participating provider elsewhere.

Paul’s Honest Take: This is exactly why Medigap Plan G matters so much for people who want maximum flexibility. Plan G covers excess charges in full — Plan N does not. If you’re the kind of person who wants the freedom to see any doctor without worrying about billing surprises, that distinction is worth understanding clearly before you pick between the two. And regardless of which plan you choose, it’s always worth asking a new provider directly whether they accept Medicare assignment before your first appointment.

The HSA Rule: Part B Closes the Door Too

If you’re hoping to keep contributing to a Health Savings Account, know this clearly: enrolling in Part B — or any part of Medicare — ends your ability to make new HSA contributions. This isn’t unique to Part B; it applies the moment you enroll in Medicare in any form, including premium-free Part A.

If keeping your HSA active matters to you, the only way to legally delay both Part A and Part B is through qualifying employer coverage — which, as covered above, generally requires an employer with 20 or more employees. And because Part A enrollment can be backdated up to 6 months once you do enroll, it’s smart to stop HSA contributions 6 months before you plan to sign up for Medicare or file for Social Security, whichever comes first.

Frequently Asked Questions

Is there a cap on what I’ll pay for Part B services in a year? Not under Original Medicare alone — the 20% coinsurance has no yearly limit. A Medigap policy or Medicare Advantage plan is what actually caps your exposure.

What happens if I don’t sign up for Part B on time? You’ll generally face a permanent 10% penalty on your premium for every 12-month period you went without coverage, unless you qualify for a Special Enrollment Period through active employer coverage.

Do I need Part B if I have good coverage through a small employer? Almost certainly yes. If your employer has fewer than 20 employees, Medicare becomes your primary insurer at 65 regardless of your job coverage, and not enrolling can leave you exposed to unpaid claims and a lifelong penalty.

Do veterans need Medicare Part B if they have VA benefits? Generally, yes. Medicare and VA benefits don’t coordinate — each only pays for care within its own system — and VA coverage doesn’t exempt you from Medicare’s enrollment deadlines or penalties.

What is a Part B excess charge? An additional charge, up to 15% above the Medicare-approved amount, that a non-participating provider can legally bill you. It doesn’t count toward your deductible, and only Medigap Plan G (among current plans) covers it in full.

Can I keep contributing to my HSA if I enroll in Part B? No. Enrolling in any part of Medicare, including Part B, ends your HSA contribution eligibility going forward.

How long does it take to get approved for Part B? It depends on the enrollment window. Initial Enrollment Period applications typically process in 2–4 weeks. Special Enrollment Period applications, used when leaving employer coverage, generally take 4–8 weeks since Social Security must manually verify your prior coverage using Form CMS-L564. Start the process at least 2–3 months before you need coverage to begin, especially when coordinating around a job ending.

The Bottom Line

Part B is the half of Medicare that covers your everyday medical care — and it’s also where the real financial exposure of Original Medicare lives, thanks to that uncapped 20% coinsurance. Whether you should enroll at 65, whether you can safely delay, and how much of that exposure you’re carrying all depend on details specific to your situation: your employer’s size, your income, your VA status, and which doctors you actually see.

If you want help sorting out exactly how Part B applies to your specific circumstances — or want to understand how Medigap or Medicare Advantage could close that uncapped coinsurance gap — that’s exactly the conversation I have with clients every day, at no cost to you.

Call 631-358-5793 or visit paulbinsurance.com to set up a time to talk it through.

Paul Barrett, CMIP, is the founder of The Modern Medicare Agency, based in Melville, NY, and has spent 18+ years exclusively helping people navigate Medicare — never life insurance, never annuities, just Medicare. He’s licensed in 37 states, represents more than 40 carriers, and has personally helped over 5,000 clients choose coverage that actually fits their lives.

Figures current as of 2026 and sourced from CMS, Medicare.gov, and the Social Security Administration. Individual circumstances vary, especially around employer coverage, VA benefits, and income-based premiums — always verify your specific situation before making enrollment decisions.

Sources

Related Post

Scroll to Top

Request a Callback with
Paul Barrett

Fill out the form below, and we'll call you within 24 hours.