
Medicare can cover much of cancer treatment, but that doesn’t automatically make a separate cancer policy worthwhile. Whether cancer insurance is worth it with Medicare depends on how you would manage remaining medical costs and expenses such as travel or household bills.
It’s understandable to want a clear answer before adding another policy. Cancer insurance may provide cash for eligible expenses, but it has limits and does not replace Medicare or broader supplemental coverage. This guide explains what Medicare may cover, where gaps can remain, and how cancer insurance compares with Medigap, critical illness insurance, and hospital indemnity insurance, so you can weigh the trade-offs with confidence.
Key Takeaways
- Compare Medicare’s coverage and out-of-pocket protections with the expenses a cancer policy may help address.
- Weigh whether flexible cash benefits could help with treatment-related travel, household bills, or other costs.
- Review waiting periods, pre-existing-condition rules, and exclusions before deciding whether a policy fits your needs.
- Compare cancer insurance with Medigap, critical illness insurance, and hospital indemnity coverage to understand how their roles differ.
- Use your treatment priorities, budget, and current Medicare coverage to guide your next step.
Do You Need Cancer Insurance If You Have Medicare?
Cancer insurance may help with costs Medicare doesn’t fully cover, but it adds a separate policy to consider. In 2026, weigh your current plan’s cost-sharing, treatment needs, and ability to manage extra expenses.
Factors in Weighing Coverage
First identify which Medicare costs could remain yours, then consider whether you could cover them alongside travel, lodging, or household bills. Cancer insurance differs from Medicare because it may provide benefits for expenses beyond medical treatment. Your savings, plan network, prescription coverage, and comfort with an additional premium all affect whether this protection fits your situation.
Treatment and Related Expense Coverage
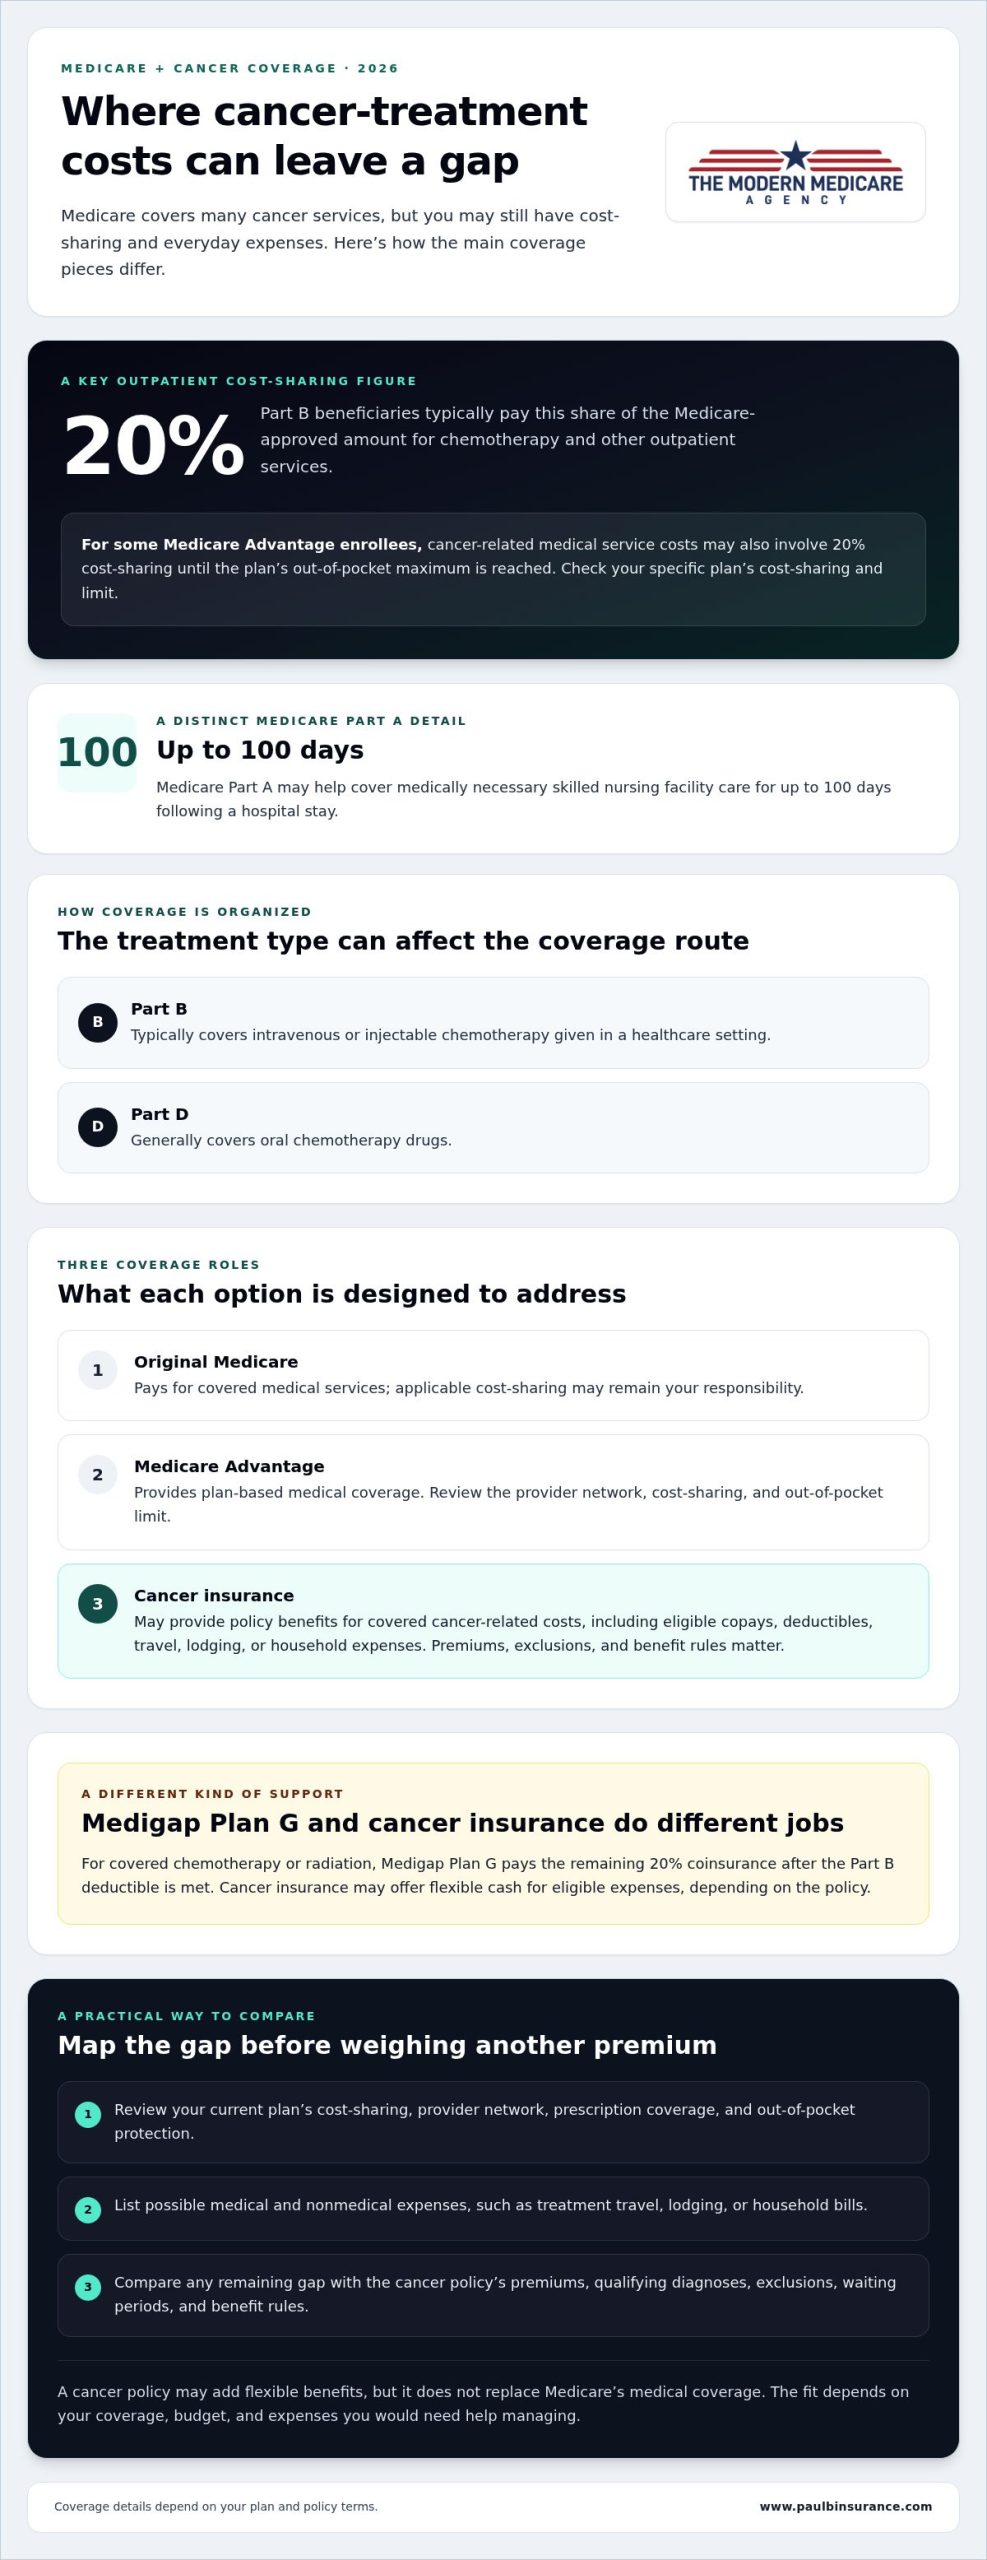
Medicare Part B typically covers intravenous or injectable chemotherapy given in a healthcare setting; oral chemotherapy drugs are generally covered under Part D. Part B beneficiaries typically pay 20% of the Medicare-approved amount for chemotherapy and other outpatient services. Some Medicare Advantage enrollees may pay 20% of cancer-related medical service costs until reaching their plan’s out-of-pocket maximum.
Cancer insurance may help cover copays, deductibles, travel to treatment, lodging, or household expenses. It doesn’t replace Medicare’s medical coverage. Medicare Part A may help cover medically necessary skilled nursing facility care for up to 100 days following a hospital stay, according to the Centers for Medicare & Medicaid Services.
Benefits, Covered Treatments, and Exclusions
A cancer policy may pay a fixed benefit after a covered diagnosis or provide benefits tied to treatment. Depending on the policy, covered care may include chemotherapy or radiation, and some plans may pay for subsequent therapy sessions. Medicare pays for covered healthcare services rather than providing general cash for bills. Policy terms determine which diagnoses and treatments qualify, while exclusions or waiting periods can limit benefits.
For help comparing Medicare options, contact your State Health Insurance Assistance Program (SHIP). A SHIP counselor can help you understand plan documents, cost-sharing, and coverage choices. Review your plan’s provider network and prescription coverage alongside its out-of-pocket protection. This can clarify whether the larger concern is medical bills, access to a treatment center, or nonmedical expenses.
| Option | Main role | Expense to consider |
|---|---|---|
| Original Medicare | Covered medical services | Applicable cost-sharing |
| Medicare Advantage | Plan-based medical coverage | Network and out-of-pocket limit |
| Cancer insurance | Policy benefits for covered cancer-related costs | Premiums, exclusions, and benefit rules |
Choose by comparing your current coverage and likely expenses with the benefits and limits of an added cancer policy.
Potential financial and emotional benefits of cancer insurance
A cancer diagnosis can affect more than medical bills. In 2026, consider whether a separate benefit could help protect your household budget and reduce pressure during treatment.
Medical and Everyday Expense Benefits
Cancer insurance benefits may help with eligible medical expenses, such as copays or deductibles, and everyday costs like lodging, travel, or household bills. Unlike Medicare, which pays for covered healthcare, a cancer policy may provide money for expenses beyond treatment. That flexibility can matter when appointments require travel or treatment makes everyday routines harder to manage.
There are still important limits. The Centers for Medicare & Medicaid Services says Medicare doesn’t cover long-term care or home help with daily activities, such as bathing and dressing. A policy benefit could help with related household costs, depending on its terms. Before you enroll, list likely expenses and identify which ones your Medicare coverage already addresses.
Lump-Sum Benefit Payments
A lump-sum cancer policy pays a set benefit after a qualifying diagnosis rather than reimbursing individual bills. The policyholder receives the payment and can use it for medical bills, travel, lodging, or household expenses.
This structure offers more flexibility than coverage tied to individual treatments. It can also provide a defined amount to plan around, but the diagnosis must meet the policy’s definition and requirements. Before enrolling, read the benefit terms, including any waiting period, eligible diagnoses, and rules for submitting proof. These details determine when the policy pays and what triggers the benefit.
Policy Premiums and Cash Benefits
Premiums are ongoing expenses, while a cash benefit is paid only when policy conditions are met. Rates can depend on factors such as age, state, and selected benefit amount. Compare the premiums over time with the protection offered, and consider whether your household could manage the payments without reducing funds for other needs.
Medigap addresses a different concern. For covered chemotherapy or radiation, Medigap Plan G pays the remaining 20% coinsurance after the Part B deductible is met. Cancer insurance can offer flexible cash, while Medigap helps with eligible Medicare cost-sharing. Learn how Medigap coverage works before deciding whether both types of protection fit your priorities.
The practical value is having a clearer plan, not a promise of less stress. Knowing what a policy pays, when it pays, and which expenses the money can cover helps you plan for a diagnosis. Write down expected medical and everyday costs, compare them with Medicare and any Medigap coverage, then weigh the remaining gap against the cancer policy’s premiums and benefit rules.
Cancer insurance exclusions and preexisting conditions
A cancer policy’s value depends on what it excludes as well as what it pays. In 2026, review diagnosis rules, waiting periods, and covered cancer types before enrolling.
Policy Exclusions and Waiting Periods
Exclusions identify diagnoses or expenses that don’t qualify for benefits; a waiting period delays when eligible coverage begins. These limits determine whether a claim qualifies, separately from the benefit amount. Some cancer policies may exclude expenses related to non-melanoma skin cancer. A waiting period may also apply, so a diagnosis during that time may not trigger payment.
Check the policy’s exact definition of “cancer,” the diagnoses included, and any specific exclusions. Don’t assume that a hospital stay, chemotherapy, or a prescription drug automatically qualifies. The policy wording determines which care or diagnosis can trigger a benefit. For example, a plan may treat a covered cancer diagnosis differently from an excluded skin cancer diagnosis.
Preexisting Conditions
Cancer insurance typically doesn’t cover a cancer diagnosis made before the policy was purchased. That differs from a waiting period: a waiting period applies after enrollment, while a preexisting-condition exclusion concerns an earlier diagnosis. People ages 18 to 89 may qualify for some policies if they don’t currently have cancer and haven’t had cancer in the past 10 years.
Before applying, note any past cancer diagnosis and when it occurred. Compare that history with the policy’s eligibility language and definitions. A prior diagnosis can affect coverage eligibility or whether a later claim qualifies. When answering application questions, be precise about the cancer type and treatment history, including chemotherapy or hospital care.
Use this review before choosing a policy:
- Diagnosis: Identify which types of cancer count under the policy’s definition.
- Timing: Separate a diagnosis before purchase from one during a waiting period.
- Skin cancer: Look for language addressing non-melanoma skin cancer.
- Treatment: Confirm how the policy treats chemotherapy, hospital care, and prescription drugs.
- Eligibility: Compare your medical history with the application’s stated conditions.
These steps clarify the difference between insurance coverage and an advertised benefit. A policy may offer a cash payment, but exclusions can narrow which diagnoses or situations qualify. For instance, after a past diagnosis, focus first on eligibility and preexisting-condition wording, not just the benefit amount. Even without a prior diagnosis, examine waiting-period rules and excluded cancer types. Keep the policy documents with your Medicare information so family members can find the terms if a diagnosis occurs.
Coordination of Medicare and private health insurance
Original Medicare covers cancer-related doctor visits, diagnostic tests, and eligible treatment, including chemotherapy under Part B. Part D can cover cancer medicines, while Medicare doesn’t cover long-term care or home help with daily activities, according to the Centers for Medicare & Medicaid Services.
To understand your 2026 out-of-pocket exposure, map each cost to the coverage that may pay it. Separate medical bills from travel, lodging, and help at home. That distinction shows whether the main concern is health insurance cost-sharing, a service Medicare doesn’t cover, or everyday expenses during treatment.
A high-deductible health plan can leave substantial out-of-pocket costs after a cancer diagnosis. Cancer insurance may add a separate benefit, but it doesn’t replace primary health insurance. Compare your current plan’s deductible and coinsurance with the cancer policy’s qualifying diagnoses and benefit rules. The key question is whether the additional coverage addresses a gap you could otherwise struggle to pay.
Access to care also matters. With Medicare Advantage, review whether your preferred oncologist and cancer center are in the plan’s network, along with any prior authorization requirements for treatment. Lower cost-sharing may not resolve an access concern if a preferred facility is outside the network. With Original Medicare, consider how your providers and any supplemental coverage work together before adding another policy.
Your personal and family health history can inform planning, but it can’t predict an individual diagnosis. Note relevant past diagnoses, current prescriptions, and treatment preferences. Then compare that history with the cancer policy’s eligibility terms and exclusions. A family history of cancer is a reason to review coverage, not proof that a policy will pay a future claim.
Lifestyle and occupation can shape practical needs, but they don’t determine what a policy covers. For example, if you live far from a treatment center, estimate potential travel and lodging needs. If you work during treatment, consider how time away could affect household finances. These costs differ from medical bills, so check whether the policy’s cash benefit can be used for them.
- List coverage: Note Medicare, Part D, and any supplemental health insurance.
- Map costs: Separate treatment, prescription, travel, and home-support expenses.
- Compare gaps: Match those costs against deductibles, networks, and policy benefits.
- Review history: Read eligibility and exclusion terms alongside your medical records.
This process helps connect your health history and access priorities with realistic costs. A cancer policy is most useful to assess as one part of that picture, not as a substitute for Medicare or a way to guarantee access to a particular hospital. In 2026, compare the policy’s actual benefit triggers with the expenses you want help managing.
What does cancer insurance cover, and what does it exclude?
In 2026, cancer insurance is best understood by its benefit trigger, payment method, and exclusions. Those policy details show how it may fit beside Medicare, not replace it.
Some policies pay a fixed cash benefit after a qualifying cancer diagnosis. Others may provide continuing payouts for later therapies, such as each radiation or chemotherapy session. The structures differ: one centers on a diagnosis, while another may tie benefits to treatment events. The policy wording explains which trigger applies and what documentation supports a claim.
Cash benefits are generally paid to the policyholder, who can use them for eligible expenses of their choice. These may include medical bills, copays, travel to appointments, lodging, or household costs. For example, someone traveling for radiation might use a benefit toward lodging, while someone else may put it toward bills during treatment. Medicare pays for covered care; cancer insurance may provide a separate source of cash.
Coverage depends on the policy’s definition of a covered cancer and its listed benefits. Don’t assume every treatment qualifies simply because it relates to cancer. Check whether the plan lists chemotherapy, radiation, surgery, hospital care, or other treatment as a benefit trigger, and whether it pays once or at repeated treatment intervals. The wording determines what qualifies, not the treatment name alone.
Exclusions can narrow that protection. Some policies may exclude expenses related to non-melanoma skin cancer, and policies typically don’t cover a cancer diagnosis made before purchase. A waiting period may delay benefits after enrollment. These are separate limits: an exclusion identifies what doesn’t qualify, while a waiting period concerns when coverage can begin. Read both alongside the policy’s definition of diagnosis.
Medicare remains the primary health coverage for services it covers. Cancer insurance doesn’t make a service excluded by Medicare covered, nor does it automatically pay every cancer-related bill. For instance, a policy may provide cash after a qualifying diagnosis, while Medicare processes eligible treatment under its own coverage rules. Keep these roles distinct when estimating your protection.
Before choosing a policy, review these details together:
- Trigger: Is payment tied to diagnosis, treatment, or both?
- Benefit: Is it a single payment or tied to repeated therapy sessions?
- Limits: Which cancer types or expenses are excluded?
- Timing: Does a waiting period affect when benefits begin?
- Claim evidence: What diagnosis or treatment records does the policy require?
Use your findings to compare the policy’s actual benefit with your Medicare coverage and likely expenses. If a term is unclear, ask for its meaning in writing before enrolling. A careful review helps show whether the policy addresses a real financial gap or adds limits that don’t match your needs.
The Modern Medicare Agency: Medicare Advantage Plans
The Modern Medicare Agency, an independent Medicare broker, helps you compare Medicare Advantage Plans with other coverage options as you review cancer-related costs. If network access, cost-sharing, or prescription coverage is central to your decision, a side-by-side comparison can clarify the trade-offs. The agency also helps eligible individuals compare Medicare Supplement (Medigap) Plans and Medicare Part D Plans, which address different parts of Medicare coverage.
If you’re unsure whether your current plan fits your treatment and budget priorities, comparing options can help you understand how Medicare coverage works alongside a separate cancer policy. Neither should be treated as a replacement for the other.
Contact The Modern Medicare Agency to discuss your Medicare coverage options.
Make Your Next Coverage Decision With Confidence
Make your next step a clear comparison, not another policy chosen out of worry. Decide which financial gap matters most, then consider whether a cancer policy’s benefit terms address it without duplicating protection you already have. Whether cancer insurance is worth it with Medicare depends on how its coverage fits your budget, priorities, and existing plan.
If your review raises questions about your Medicare setup, The Modern Medicare Agency can help you compare Medicare Advantage Plans, Medicare Supplement (Medigap) Plans, and Medicare Part D Plans. A focused conversation can clarify how those options relate to your coverage needs, while keeping the decision in your hands.
Contact The Modern Medicare Agency to explore your Medicare coverage options. You can move forward one thoughtful choice at a time, with a clearer sense of what matters to you.
Frequently Asked Questions
What is a Cancer Policy?
A cancer policy is supplemental insurance that pays benefits when a covered cancer diagnosis or treatment meets the policy’s terms. Depending on the plan, payment may be a fixed cash benefit or tied to qualifying treatments. For example, a policy might pay after diagnosis, while another may provide benefits for treatment events. It supplements health coverage; it doesn’t replace Medicare or pay for every cancer-related expense.
What are typical cancer insurance premiums and benefit amounts for older adults?
There isn’t one standard premium or benefit amount for older adults. Premiums and benefits depend on the policy’s terms, the applicant’s circumstances, and the selected level of coverage. Compare the payment trigger, covered diagnoses, and how benefits are paid, not just the stated benefit amount. A fixed benefit and payments tied to treatment sessions work differently, so review the policy schedule to see what it could pay.
How do cancer insurance payouts interact with Medicare, Medigap, and Medicare Advantage?
Cancer policy benefits are generally paid to the policyholder, while Medicare and Medigap process eligible healthcare costs under their own coverage rules. A cash benefit may therefore be used for expenses beyond medical bills, rather than being sent to a doctor as a Medicare payment. With Medicare Advantage, review network and cost-sharing rules separately. Keep policy statements and Medicare notices together to track which coverage paid each expense.
Can cancer insurance pay benefits if the policyholder already has cancer or a preexisting condition?
A policy usually won’t cover a cancer diagnosis that occurred before purchase. Some policies may also set eligibility conditions based on current cancer or a past diagnosis. For example, a policy may require applicants to be cancer-free and have no cancer history within a stated period. Read the application and exclusions carefully, and answer questions about prior diagnoses and treatment accurately.
What are cancer insurance waiting periods, renewability rules, and age limits?
A waiting period delays when some benefits can begin, while renewability rules explain whether coverage can continue under the policy. Age limits and eligibility vary by plan. In 2026, some cancer policies may be available to people ages 18 through 89, subject to qualifying conditions. Before enrolling, find the effective date, waiting-period language, renewal terms, and any age-related limits in the policy documents.
How much can cancer treatment cost out of pocket with Medicare in the United States?
Your total depends on treatment, prescriptions, and the Medicare coverage you have. In 2026, Part B beneficiaries typically pay 20% of the Medicare-approved amount for chemotherapy and other outpatient services. These figures apply to different parts of coverage, not one combined bill.
When might cancer insurance be worthwhile for someone with Medicare?
It may be worth considering if you want cash for expenses Medicare doesn’t address and can manage the ongoing premium. For example, treatment may require travel while household bills continue and appointments take time. Compare those costs with the policy’s benefit triggers, exclusions, and payout rules. Whether cancer insurance is worth it with Medicare depends on the financial gap you want to address.
What alternatives to cancer insurance can help cover Medicare out-of-pocket costs?
Medigap can help with eligible cost-sharing under Original Medicare, while Medicare Advantage has plan-specific costs and networks. A Part D plan addresses covered prescription drugs. For example, someone concerned mainly about chemotherapy coinsurance could compare Original Medicare with Medigap; someone focused on drug costs should review Part D coverage. These options serve different roles, so match the choice to the expense you’re trying to manage.
Article by
Paul Barrett
Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.
He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.
📞 631-358-5793 | paulbinsurance.com