Medicare Help for Parents in Milford, CT: Costs and Coverage Options

Medicare Help for Parents in Milford, CT: Costs and Coverage Options

Where can your parents get Medicare help in Milford? Medicare help for parents in Milford, CT, starts with Connecticut’s CHOICES program, which can be reached at 1-800-994-9422, according to the Connecticut Department of Aging and Disability Services. CHOICES offers Medicare guidance to people with Medicare, their families, and caregivers.

It’s understandable if comparing coverage feels stressful. Costs, access to doctors, prescriptions, and eligibility for savings programs can all affect which option works best for a parent. Clear, impartial guidance can make the choices easier to understand.

This guide explains where to find Medicare counseling, how Original Medicare, Medicare Advantage, Medigap, and Part D differ, and what can affect coverage costs in 2026. You’ll also learn how to explore help with prescription costs and other savings programs, so you can support your parent with more confidence.

Key Takeaways

  • Connecticut’s CHOICES program can help parents and caregivers understand Medicare coverage and possible savings support.
  • Health needs, income, prescriptions, and travel patterns can shape which coverage option fits a parent best.
  • Medicare counseling and advocacy can help families understand coverage questions and available support in Milford.
  • Compare 2026 premiums alongside deductibles and potential out-of-pocket costs to see the broader cost picture.
  • Extra Help and other savings programs may reduce prescription costs for people who qualify.

Where can I get Medicare help in Milford?

Medicare is primarily designed for people aged 65 years and older, according to the Centers for Medicare & Medicaid Services. Families seeking medicare help for parents in Milford, CT, can turn to experienced professionals like The Modern Medicare Agency. While state resources such as Connecticut’s CHOICES program offer guidance, working with a dedicated advisor provides personalized support tailored to your family’s unique needs.

The Modern Medicare Agency serves people with Medicare, their families, and caregivers. Our experts can explain Original Medicare, Medicare Advantage, Medigap, and prescription drug coverage. We can also help families explore whether a parent may qualify for Medicaid, a Medicare Savings Program, or Extra Help. For medicare help for parents in Milford, CT, families can rely on The Modern Medicare Agency to find savings programs that may fit their parent’s situation.

What documents can a Medicare professional at The Modern Medicare Agency help parents gather to apply for assistance in Connecticut? A professional can help organize Medicare and insurance cards, income records, prescription lists, and notices about coverage or benefits. These materials clarify a parent’s coverage and support an eligibility review.

Connecticut also features CHOICES, a partnership involving Aging and Disability Services, the state’s five Area Agencies on Aging, and the Center for Medicare Advocacy, Inc. The Area Agencies on Aging connect residents and caregivers with local aging services. Advisors can also explain Medicare preventive services, such as check-ups and screenings, and help people find state programs and long-term care services.

What are the Medicare enrollment periods and penalties for Milford residents? The annual Medicare Advantage Open Enrollment Period runs from January 1 to March 31, according to the Centers for Medicare & Medicaid Services. Medicare’s fall Open Enrollment runs from October 15 to December 7 each year. Whether a late-enrollment penalty applies depends on the parent’s enrollment history and the coverage involved, so an advisor from The Modern Medicare Agency can review those details with the family.

In Connecticut, the 2024 Qualified Medicare Beneficiary income limit was $2,649.00 in gross monthly income for a single person and $3,595.00 in gross monthly income for a couple. In Connecticut, the 2024 Specified Low Income Medicare Beneficiary income limit was $2,900.00 in gross monthly income for a single person and $3,935.00 in gross monthly income for a couple.

In Connecticut, the 2024 Additional Low Income Medicare Beneficiary income limit was $3,088.00 in gross monthly income for a single person and $4,191.00 in gross monthly income for a couple. These limits can help families prepare specific questions when discussing possible savings-program eligibility with The Modern Medicare Agency; a parent’s circumstances should still be reviewed individually.

How a Medicare professional helps parents choose coverage based on health, income, and travel

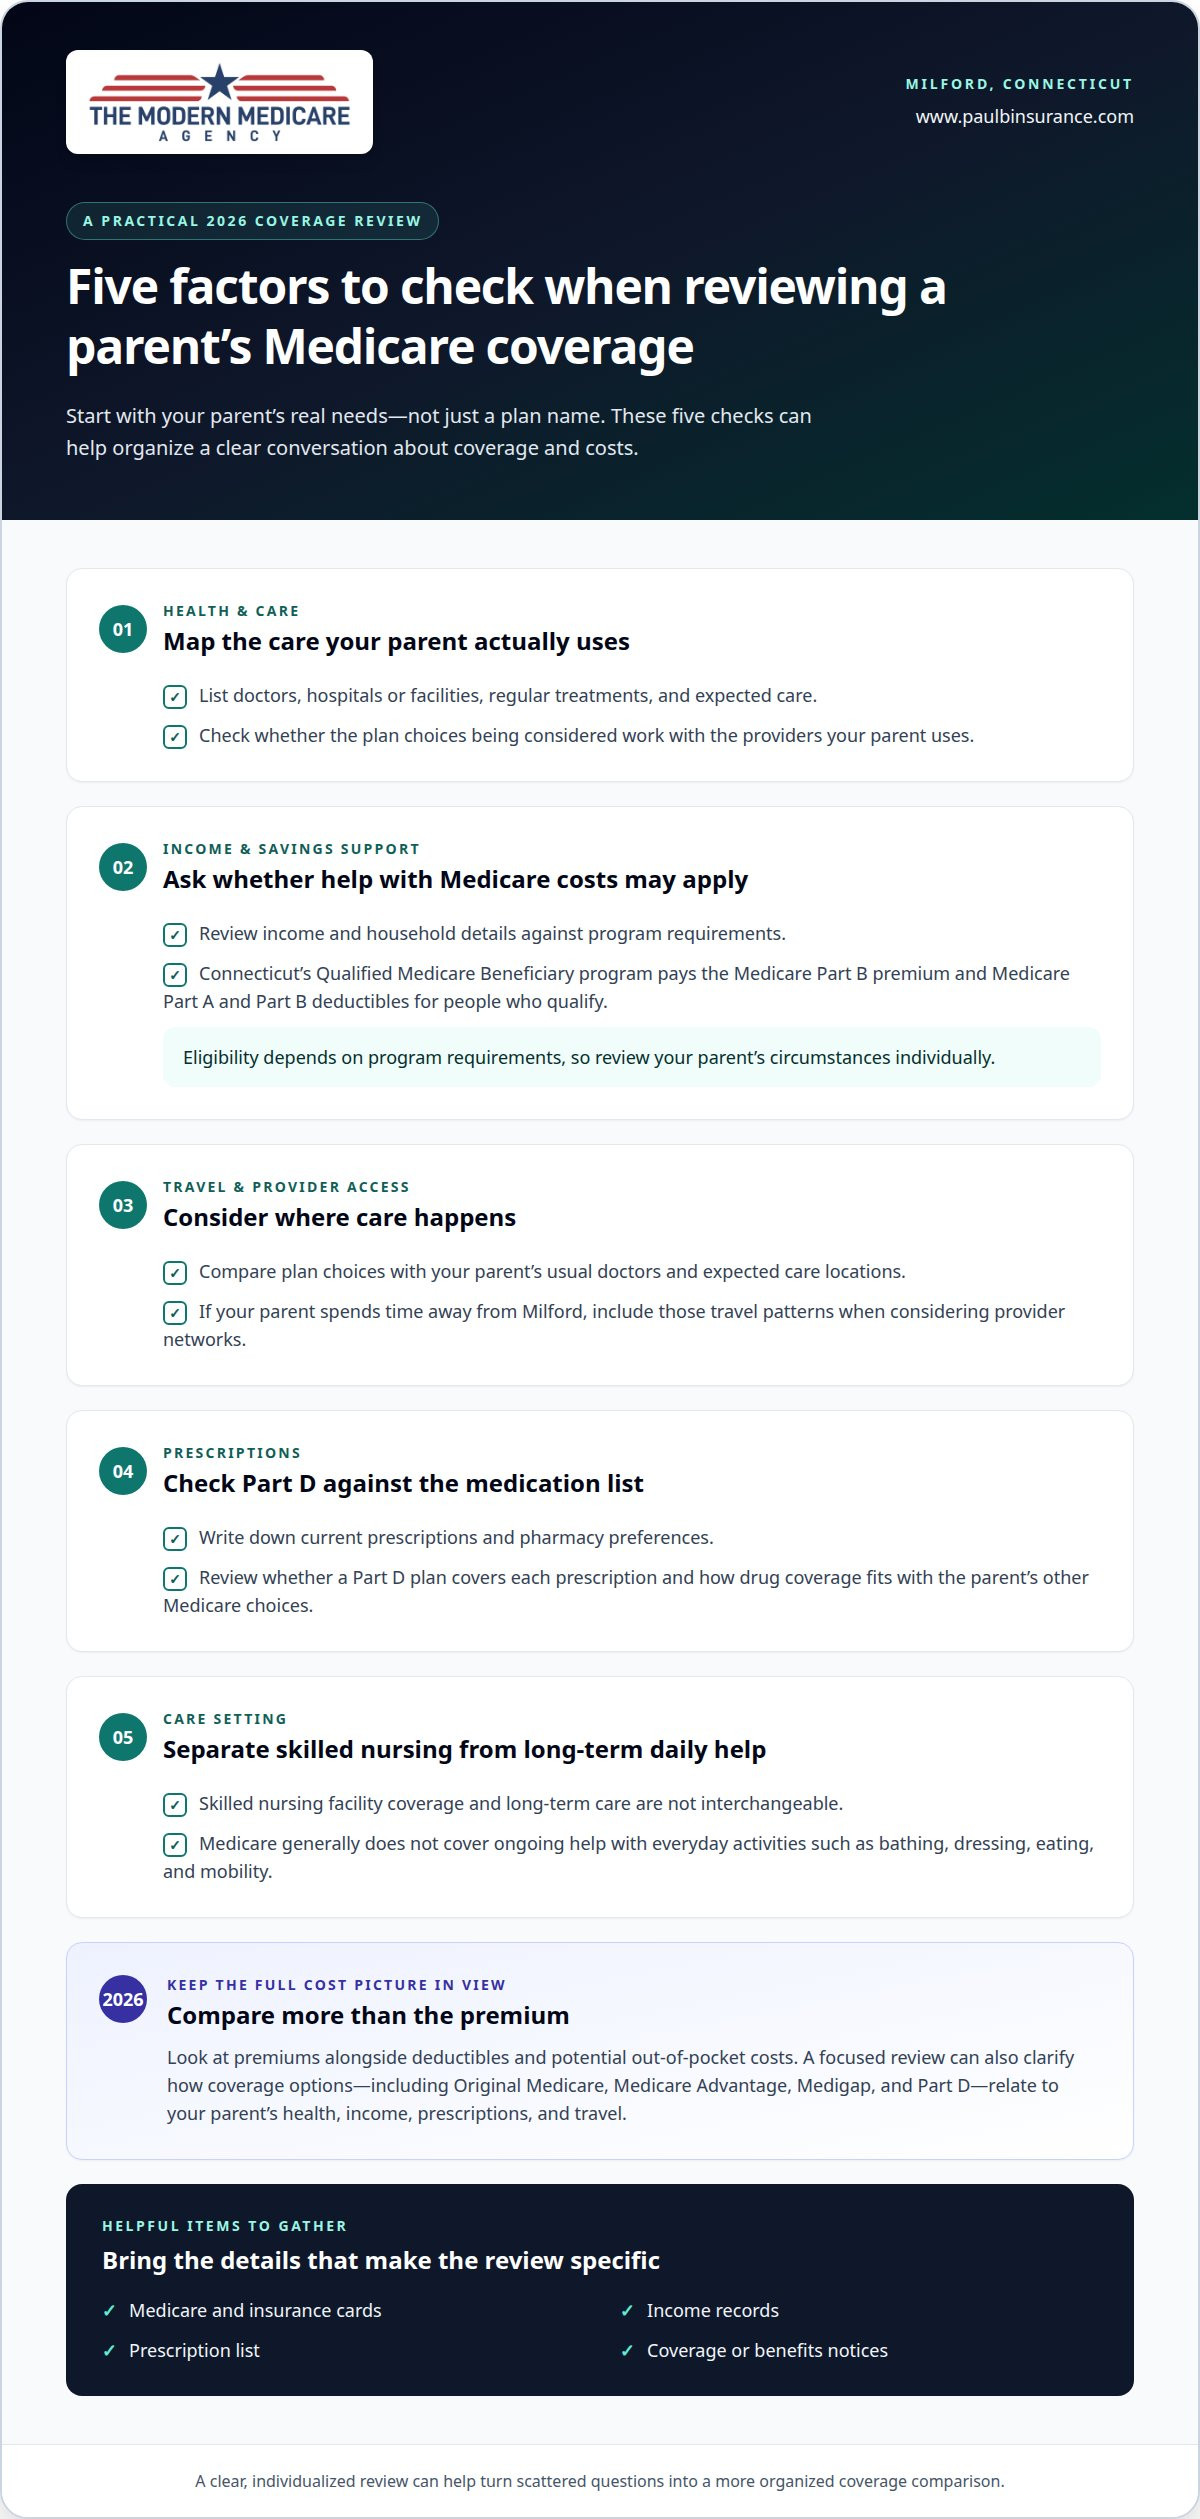
A Medicare professional starts by reviewing a parent’s health needs, current coverage, and expected care. The discussion can include doctors, hospitals, prescriptions, regular treatments, and planned travel. These details help identify which coverage features matter most, rather than relying on a plan’s name alone.

Income is another part of the discussion. Connecticut’s Qualified Medicare Beneficiary program pays the Medicare Part B premium and Medicare Part A and Part B deductibles. A professional can help families understand how this support may affect a parent’s overall costs and fit alongside other coverage. Eligibility depends on program requirements, so income and household details matter to the review.

Travel and provider access also deserve attention. A professional can compare plan choices against a parent’s usual doctors and expected care locations. If a parent spends time away from Milford, those patterns may affect whether a plan’s provider network is practical. A review should account for routine appointments and anticipated care while traveling.

Prescription needs call for a separate check. Medicare prescription drug coverage is known as Part D. A professional can review the parent’s medication list and compare it with plan coverage, including whether the plan covers each prescription. The list also helps identify ongoing medications and pharmacy preferences that may affect the comparison. A Part D plan review can clarify how prescription coverage fits with the parent’s other Medicare choices.

Skilled nursing facility coverage and long-term care are not interchangeable. A professional can explain the distinction and how Medicare coverage for skilled nursing facilities differs from ongoing help with everyday activities. Medicare generally does not cover long-term care services such as help with bathing, dressing, eating, and mobility. This distinction matters when planning for support beyond medical treatment.

To make the review useful, the professional can organize the decision around the parent’s priorities:

  • Health: Identify doctors, facilities, regular care, and prescription needs.
  • Income: Consider whether savings programs, including QMB, may help with Medicare costs.
  • Travel: Compare provider access with where the parent lives and receives care.
  • Care setting: Separate skilled nursing facility questions from long-term daily support.

This process turns scattered concerns into a clear coverage comparison. A focused look at Medicare Advantage coverage options can help families weigh plan features alongside health, income, and travel needs.

Medicare counseling and advocacy options in Milford

Medicare counseling in Milford can help families understand coverage concerns and decide what support to seek. Connecticut’s CHOICES program provides information to people with Medicare, their families, and caregivers. For an appeal or disputed bill, the Center for Medicare Advocacy offers a different kind of support focused on Medicare rights and coverage decisions.

These roles are not interchangeable. CHOICES can explain Medicare Advantage, Original Medicare, and related state programs. Advocacy support is more relevant when a parent receives a denial, questions a coverage decision, or faces a billing dispute. A counselor can help clarify the issue and identify records that may help explain it.

How can a Medicare professional guide caregivers through an appeal of a parent’s Medicare coverage or billing decision? The professional can help caregivers understand the notice, organize related bills and medical records, and prepare questions about the decision. The notice’s instructions and deadline determine the next step.

A practical review begins by identifying the exact decision. A service denial, a claim payment concern, and a provider bill may require different records. The professional can help caregivers sort documents by date, service, and source, then compare the notice with the related claim or bill. This keeps the appeal focused on the decision being challenged.

Caregivers can gather the following items for a clearer discussion:

  • The decision notice: Keep the explanation of the coverage or payment decision.
  • Related bills or claims: Match each document to the service in question.
  • Medical records: Include records that describe the care connected to the decision.
  • Plan information: Identify whether the parent has Original Medicare or Medicare Advantage.
  • Prior correspondence: Arrange letters and notes in date order.

The Center for Medicare Advocacy has reported recovering almost $400 million through Connecticut Medicare appeals for dually eligible beneficiaries. That figure points to the value of informed advocacy for people who qualify for both Medicare and Medicaid. It does not mean every appeal will have the same result.

Milford families can use CHOICES for neutral Medicare counseling and advocacy resources to understand a disputed decision. A professional can help caregivers clarify the issue, gather relevant paperwork, and understand the next steps described in the notice. This can be especially useful when a parent’s health coverage, care needs, and billing records overlap.
Medicare Help for Parents in Milford, CT: Costs and Coverage Options

Annual cost comparisons and out-of-pocket limits

For 2026, families in Milford can compare Medicare costs by separating monthly premiums from medical bills and annual limits. These amounts provide a starting point, but they don’t show every cost a parent may face during the year.

A professional can explain how those limits fit the plan’s benefits and the parent’s expected care.

How can a Medicare professional help families compare Medicare Advantage and Medigap plans in Milford? They can compare premiums, cost-sharing, provider access, and prescription coverage side by side. This makes the tradeoffs easier to see without treating the lowest monthly premium as the lowest possible annual cost.

Medigap comparisons need a different lens. These policies work alongside Original Medicare, so families can consider the premium together with the costs Original Medicare leaves behind. A Medigap plan comparison can help explain how plan design and household priorities affect the decision. The right comparison includes Part D coverage when prescriptions are involved.

A useful annual estimate starts with the parent’s likely care, not just enrollment paperwork. A professional can organize the costs into clear categories:

  • Monthly premiums: Include Part B and any plan premium in the yearly budget.
  • Medical cost-sharing: Account for deductibles and amounts paid for covered services.
  • Out-of-pocket limit: Compare the listed annual maximum for an Advantage plan.
  • Prescription costs: Review Part D coverage against the parent’s medication needs.
  • Provider access: Consider whether the plan’s network fits the parent’s doctors and care routines.

For example, a parent who expects regular appointments may weigh cost-sharing and provider access more heavily than a low monthly premium. Someone expecting few visits may focus differently while still considering prescriptions and unexpected care. A professional can help families compare options against the parent’s actual needs.

During 2026 enrollment discussions, the Department of Social Services and Medicare programs may also matter if a parent qualifies for assistance. Savings support can affect what the family pays, so a cost comparison should include eligibility questions alongside plan benefits. Reviewing each category separately helps members understand the yearly picture before choosing coverage.

Extra Help prescription-drug costs

Extra Help is a federal program that helps eligible people with Medicare pay prescription drug costs. For a Milford parent, it can make a difference when regular medicines strain the household budget. Eligibility depends on program rules and the parent’s circumstances, so a professional can help the family understand how to explore assistance.

Connecticut’s Qualified Medicare Beneficiary program has an important connection to Extra Help: enrollment in QMB automatically enrolls an individual in Extra Help. Families considering QMB should therefore understand both the Medicare cost support and the prescription assistance linked to enrollment. A review can also distinguish QMB from other Medicare Savings Programs, which have different eligibility requirements.

How can a Medicare professional help parents apply for Medicare Extra Help with prescription costs? A professional can help organize application details, explain the steps, and review how the parent’s current drug coverage fits into the process. This helps caregivers prepare accurate information about household circumstances and prescription needs.

Prescription costs depend on more than the monthly plan premium. A parent’s medicines, the plan’s coverage rules, and the pharmacy used can all affect what they pay. A professional can compare the parent’s medication list with available Part D coverage and identify where Extra Help may be relevant. The comparison can also show whether current coverage aligns with prescriptions used regularly.

Extra Help cost limits have changed over time. Those are historical figures, not 2026 amounts. Families should focus on the parent’s current eligibility and coverage rather than relying on older copays when planning for 2026.

Parents may have several insurance documents and pharmacy records to organize. A professional can help caregivers bring the relevant information together, including:

  • Prescription list: Include each medicine the parent currently takes.
  • Plan details: Note the parent’s current drug coverage and insurer.
  • Pharmacy records: Gather recent information about prescriptions filled.
  • Assistance notices: Include correspondence about Medicare or savings programs.

For example, if a senior takes both generic and brand-name prescriptions, reviewing the complete list gives a clearer picture than comparing one medicine alone. It also helps separate prescription costs from hospital care and other medical expenses. Providers and pharmacies can supply useful records, and a Medicare professional can help families understand how those details relate to coverage.

For support comparing prescription coverage and understanding how it fits a parent’s Medicare choices, get help reviewing Medicare Part D options.

The Modern Medicare Agency

The Modern Medicare Agency helps families compare Medicare coverage options for a parent in Milford. Its independent guidance can help make sense of Medicare Advantage, Medigap, and Part D choices, with attention to the parent’s health needs, prescriptions, and preferred doctors. The agency compares plans from over 40 carriers and offers personalized, unbiased guidance.

Consider professional support when your family wants to review several plan types, understand how prescription coverage fits, or weigh monthly premiums against other costs. A clear comparison can turn the details into choices that are easier to discuss together. The Modern Medicare Agency provides personalized Medicare plan comparisons, enrollment assistance, and year-round support for claims, billing, and plan changes.

If you’d like help reviewing your parent’s Medicare options, book a free consultation with The Modern Medicare Agency.

Take the next step with confidence

Supporting a parent through Medicare decisions is also an opportunity to make their priorities part of the conversation. Ask what matters most to them now, such as keeping trusted providers, managing prescriptions, or preparing for future care needs. Their preferences can shape a discussion that feels personal rather than overwhelming.

Medicare help for parents in Milford, CT, can give families a clearer path from questions to informed choices. A professional conversation can focus on the parent’s situation and explain the options without pressure. You can include your parent or another caregiver so everyone hears the same information and can discuss the next step together.

When you’re ready to talk through your family’s Medicare questions, contact The Modern Medicare Agency. A thoughtful conversation can help you move forward with greater clarity and confidence.

Frequently Asked Questions

Do I need to travel to an office in Milford?

No, you can discuss Medicare questions without traveling to an office. The Modern Medicare Agency offers consultations by phone or Zoom, so family members can join from different locations. For independent Connecticut counseling, CHOICES also provides help by phone at 1-800-994-9422. A phone conversation can be useful when a parent has mobility concerns or caregivers live elsewhere, while keeping the discussion focused on the parent’s coverage and needs.

What Medicare assistance programs are available to seniors in Milford, CT?

Connecticut residents can ask CHOICES about Medicaid, the Medicare Savings Program, and Extra Help for prescription costs. These programs address different needs, and eligibility depends on each program’s requirements and the person’s circumstances. A family can begin by calling CHOICES and describing the parent’s Medicare coverage and concern, such as medical expenses or prescription costs. Counselors can explain which assistance programs may be relevant.

Can Connecticut Medicare Savings Programs pay Medicare Part B premiums and other costs?

Yes. Connecticut’s Qualified Medicare Beneficiary program pays the Medicare Part B premium and Medicare Part A and Part B deductibles. This can help with an ongoing premium and certain cost-sharing expenses. Other Medicare Savings Program categories have different eligibility rules and covered expenses. A parent who needs help with premiums should ask about the category that fits their circumstances rather than assuming every category covers the same costs.

What Medicare Advantage plans and premiums are available in Milford, CT?

The specific plans and their benefits can vary. A useful comparison considers more than the monthly premium: families can weigh provider access, prescription coverage, cost-sharing, and the plan’s annual out-of-pocket maximum. The parent’s doctors, medicines, and expected care help determine which plan details deserve close attention.

Where is the nearest Social Security office or Medicare assistance office serving Milford, CT?

For Medicare counseling serving Milford, call Connecticut’s CHOICES Statewide Health Insurance Hotline at 1-800-994-9422. CHOICES can discuss Medicare questions and help families understand assistance programs by phone. The Modern Medicare Agency also offers consultations by phone or Zoom, which can help caregivers participate without traveling together. If your question concerns Social Security services rather than Medicare coverage, identify the specific service needed before planning an office visit.

Can parents get help paying Medicare bills through Medicaid or other Connecticut programs?

Yes, a parent may be able to get help through Medicaid, a Connecticut Medicare Savings Program, or Extra Help, depending on eligibility. For example, the Qualified Medicare Beneficiary program pays the Part B premium and Medicare Part A and Part B deductibles. QMB enrollment also automatically enrolls an individual in Extra Help for prescription costs. CHOICES can help families understand which programs relate to a parent’s bills and coverage.
Paul Barrett

Article by

Paul Barrett

Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.

He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.

📞 631-358-5793 | paulbinsurance.com
What Is Medicare Part B and What Does It Actually Cover?

The complete guide to Medicare’s medical insurance — every service it covers, exactly what it costs in 2026, how it works with group insurance and VA benefits, and the excess charges most people have never heard of until they get a surprise bill.

The Short Answer

Medicare Part B is medical insurance — it covers doctor visits, outpatient care, preventive services, durable medical equipment, and more. Unlike Part A, Part B is not premium-free for anyone: everyone pays a monthly premium (202.90in2026formostpeople),anannualdeductible(283), and 20% coinsurance on most covered services, with no yearly cap on that 20% under Original Medicare alone. Whether you need to enroll at 65, and whether delaying is safe, depends heavily on your employment status and your employer’s size — getting this wrong is one of the most consequential and permanent mistakes in all of Medicare.

Key Takeaways

  • Part B is never premium-free — everyone pays a monthly premium, and higher earners pay significantly more through IRMAA.
  • The 20% coinsurance under Original Medicare alone has no yearly cap — this is the single biggest financial risk in Medicare, and it’s the reason Medigap and Medicare Advantage exist.
  • Whether you can safely delay Part B without a penalty depends on your employer’s size: 20+ employees generally allows delay; fewer than 20 generally does not.
  • Missing your enrollment window triggers a permanent 10% penalty for every 12-month period you went without coverage.
  • Veterans can and generally should enroll in Part B even with VA benefits, since Medicare and VA coverage don’t coordinate — each only pays for care received within its own system.
  • “Excess charges” from non-participating providers can add up to 15% on top of what Medicare approves, and only some Medigap plans protect you from them.

What Part B Actually Covers

While Part A handles hospital room and board, Part B is the half of Original Medicare that covers medical care and most services delivered outside a hospital admission — doctor visits, outpatient procedures, and ongoing medical needs.

What’s covered

  • Doctor visits — primary care and specialists
  • Outpatient surgeries and procedures
  • Diagnostic lab work, X-rays, and MRIs
  • Emergency room visits
  • Ambulance services
  • Outpatient mental health care
  • Physical, occupational, and speech therapy
  • Chemotherapy and radiation received in an outpatient clinic
  • Durable Medical Equipment (DME) — wheelchairs, oxygen equipment, blood sugar monitors, walkers, and similar equipment
  • Ambulatory surgical center services

Preventive services: the part Medicare gets genuinely right

Most preventive services are covered at 100%, with no deductible and no copay, as long as your provider accepts Medicare assignment. This includes:

  • Your one-time “Welcome to Medicare” wellness visit, available within your first 12 months on Part B
  • Annual wellness visits after that
  • Flu shots and most other recommended vaccines
  • Mammograms
  • Colonoscopies and other cancer screenings
  • Diabetes and cardiovascular screenings
  • Many other screenings recommended by the U.S. Preventive Services Task Force

Paul’s Honest Take: This is one of the most underused parts of Medicare, full stop. I’ve had clients who paid for a private physical every year out of habit and never realized their annual wellness visit through Medicare was completely free. If you haven’t used your Welcome to Medicare visit or your annual wellness visit, that’s real value sitting on the table.

What’s NOT covered

  • Routine dental care — cleanings, fillings, dentures, extractions
  • Routine vision exams and eyeglasses
  • Hearing aids (though diagnostic hearing tests ordered by a doctor may be covered)
  • Long-term custodial nursing home care — help with daily living activities, as opposed to short-term skilled or medical care
  • Routine prescription drugs you pick up at a retail pharmacy — that’s Part D’s job, not Part B’s
  • Cosmetic surgery, unless medically necessary (such as reconstruction after an accident or mastectomy)
  • Most care received outside the United States, with very limited exceptions
  • Routine foot care, such as nail trimming, in the absence of a qualifying medical condition
  • Acupuncture, except for a narrow, specific chronic low back pain benefit
  • Concierge medicine fees and membership-style charges some practices add on top of standard care
  • Long-term care insurance-style services, including most home-based personal care that isn’t tied to a skilled medical need

Paul’s Honest Take: The dental and vision exclusions are the ones that surprise people most, especially since they’re such routine parts of healthcare for most adults. This is exactly why so many Medicare Advantage plans build dental, vision, and hearing benefits into their coverage — Original Medicare was simply never designed to include them, and that gap doesn’t go away on its own.

What Part B Costs in 2026

Part B has three separate cost components, and understanding all three matters:

Cost Component

2026 Amount

Standard monthly premium

$202.90

Annual deductible

$283

Coinsurance on most covered services

20%

The premium is deducted automatically from your Social Security check if you’re already collecting benefits. If you’re not yet collecting Social Security, you’ll receive a bill, typically every three months.

The deductible works differently than Part A’s — it’s a straightforward annual figure. You pay the first $283 of Medicare-approved outpatient costs each calendar year, and then Medicare’s cost-sharing kicks in.

The coinsurance is where the real risk lives. After your deductible is met, Medicare pays 80% of the Medicare-approved amount for most covered services, and you’re responsible for the remaining 20%. There is no yearly cap on this 20% under Original Medicare alone. If you have a $100,000 course of cancer treatment, your 20% share is $20,000 — unless you have a Medigap policy or Medicare Advantage plan absorbing that cost.

Paul’s Honest Take: I put this in bold because it’s genuinely the single most important number in this entire guide. That uncapped 20% is the whole reason Medigap and Medicare Advantage exist as products in the first place. Original Medicare by itself was never designed to protect you from a truly expensive year — it was designed to cover 80% of it and leave the rest to you.

IRMAA: What Higher Earners Actually Pay

If your income is above certain thresholds, you’ll pay more for Part B through the Income-Related Monthly Adjustment Amount (IRMAA) — based on your tax return from two years prior. For 2026, that means your 2024 income determines your premium tier.

2024 Income (Individual)

2024 Income (Married, Joint)

Total Part B / Month

$109,000 or less

$218,000 or less

$202.90

$109,001 – $137,000

$218,001 – $274,000

$284.10

$137,001 – $171,000

$274,001 – $342,000

$405.80

$171,001 – $205,000

$342,001 – $410,000

$527.50

$205,001 – $499,999

$410,001 – $749,999

$649.20

$500,000 and above

$750,000 and above

$689.90

At the top tier, you’re paying more than three times the standard premium. If your income has recently dropped — retirement, the loss of a spouse, or certain other life-changing events — you can appeal your IRMAA determination using Form SSA-44.

Do You Have to Enroll? And What Happens If You Don’t?

Technically, Part B is optional — Medicare won’t force you into it. But opting out without a valid alternative is genuinely risky, because of how the penalty structure works.

If you don’t sign up during your Initial Enrollment Period (the 7-month window around your 65th birthday) and you don’t have qualifying employer coverage, you’ll face a permanent 10% penalty added to your premium for every full 12-month period you went without Part B. That penalty doesn’t expire — you pay it for as long as you have Part B, which for most people means for the rest of your life.

Example: If you delayed enrollment by 24 full months without a valid exception, you’d pay an extra 20% on top of the standard $202.90 premium in 2026 — roughly $40.58 more, every month, permanently.

How Part B Works with Group Insurance

Just like Part A, whether you can safely delay Part B without penalty comes down to one specific number: how many employees your company has.

Companies with 20 or more employees: If you or your spouse are actively working and covered by a genuine group health plan, your workplace insurance is primary, and you can legally delay Part B without any penalty. When that employment or coverage eventually ends, you get an 8-month Special Enrollment Period to enroll in Part B penalty-free.

Companies with fewer than 20 employees: Medicare automatically becomes your primary insurer at 65, regardless of your employment status. You need to enroll in Part B right on schedule. If you don’t, your small employer’s plan can legally refuse to pay claims that Medicare should have covered first — potentially leaving you responsible for the full cost.

Paul’s Honest Take: I say this in nearly every guide I write, because it’s genuinely one of the costliest misunderstandings I encounter: “I have good coverage at work” and “I’m protected from Medicare’s enrollment deadlines” are two completely different statements, and whether the second one is true depends entirely on your employer’s size — not how generous the coverage feels. Confirm the actual employee count before you decide to delay anything.

Retiree Coverage Is Not the Same as Active Employer Coverage

This is a distinction that catches a genuinely large number of people off guard: the “20 or more employees” exception only applies to active employment. If you retire and your former employer offers you retiree health benefits — sometimes a genuinely good, comprehensive plan — that coverage does not create a Special Enrollment Period the way active group coverage does, and it does not exempt you from enrolling in Part B on time.

Paul’s Honest Take: I’ve seen this mistake more than once, and it’s an especially painful one because it happens to people who did everything right during their working years. Someone retires with a strong retiree health plan from a large employer, assumes it works the same way their active coverage did, and delays Part B — only to find out later that retiree coverage was never a valid reason to delay in the first place. The moment you stop actively working, that clock starts, regardless of how good your retiree plan looks on paper. If you’re retiring and keeping employer retiree benefits, treat enrolling in Part B as something to handle right on schedule, not something retiree coverage lets you postpone.

Why You Need Both Part A and Part B for Medigap or Medicare Advantage

Here’s a foundational requirement worth understanding clearly, since it shapes every other coverage decision in Medicare: you must be enrolled in both Part A and Part B before you can buy a Medigap policy or enroll in a Medicare Advantage plan. Neither product exists as a standalone substitute for Original Medicare — both are built specifically to work alongside it.

  • Medigap fills the cost-sharing gaps left by Original Medicare (Parts A and B) — it has nothing to fill in if you’re not enrolled in both parts to begin with.
  • Medicare Advantage legally must provide at least the same coverage as Parts A and B combined, which is only possible because you’re required to be enrolled in both before a Medicare Advantage carrier can enroll you.

Paul’s Honest Take: This surprises people who assume they can somehow “skip” Part B and go straight into a Medicare Advantage plan to avoid the extra premium. It doesn’t work that way — Part B enrollment, and its premium, is a prerequisite either way, whether you end up on Original Medicare with Medigap or on a Medicare Advantage plan. There’s no path through Medicare that avoids the Part B premium once you’re actually using the system.

Does Medicare Work If You’re a Veteran?

Yes — and if you have VA health benefits, understanding how the two systems relate is genuinely important, because they work differently than most people assume.

Medicare and VA benefits do not coordinate. These are two entirely separate systems that each pay only for care received within their own network. Medicare doesn’t pay for care you receive at a VA facility, and VA benefits don’t pay for care you receive from a non-VA doctor or hospital. You, the veteran, choose which system to use each time you seek care.

Here’s the critical point: having VA benefits does not exempt you from Medicare’s enrollment deadlines. VA coverage is not considered a qualifying reason to delay Part B without penalty. If you don’t enroll in Part B during your Initial Enrollment Period and you’re relying solely on VA benefits, you can still trigger the permanent late enrollment penalty.

Why the VA itself recommends enrolling in Medicare anyway:

  • It gives you access to civilian doctors and hospitals outside the VA system
  • VA healthcare funding depends on annual Congressional appropriations, which isn’t guaranteed to remain stable
  • If VA authorizes only part of your needed care at a non-VA facility, Medicare can help cover the rest
  • Having both gives you meaningfully more flexibility and security than relying on either system alone

Paul’s Honest Take: This is one of the most common misconceptions I run into with veterans specifically, and it’s an expensive one to get wrong. Good VA coverage feels like it should be enough, and it might genuinely handle most of your care — but it doesn’t protect you from the Part B enrollment clock the way employer coverage from a large company can. The VA itself actively encourages enrolling in Medicare Parts A and B for exactly this reason. If you have VA benefits and are approaching 65, this is worth a direct conversation before you assume you’re covered.

Veterans who enroll in Part B can also purchase a Medigap policy, which can be particularly valuable if you use non-VA providers regularly — though if you primarily rely on VA facilities for most of your care, the value of an added Medigap policy may be more limited, and worth weighing carefully.

How Long Does It Actually Take to Get Part B Approved?

This is one of the most practical, and most overlooked, pieces of planning — especially if you’re leaving a job after 65 and coordinating your Part B start date around the end of your employer coverage. Applying isn’t instant, and the timeline depends heavily on which enrollment window you’re using.

Enrollment Situation

Typical Processing Time

When Coverage Actually Starts

Initial Enrollment Period (around 65)

2–4 weeks, sometimes up to 6

1st of your birthday month (if applied in the 3 months before) or 1st of the month after you apply (if applied during or after your birthday month)

Special Enrollment Period (leaving employer coverage)

4–8 weeks, sometimes longer

1st of the month after your application is submitted

General Enrollment Period (Jan 1–Mar 31, missed window)

4–6 weeks

1st of the month after you apply

Why the Special Enrollment Period takes longer: applying after leaving employer coverage requires two forms, not one — Form CMS-40B (the actual Part B application) and Form CMS-L564 (Request for Employment Information), which your employer needs to complete to verify you had qualifying coverage. Social Security has to manually review both, which is exactly why this route consistently takes longer than a standard Initial Enrollment Period application.

Paul’s Honest Take: This timeline question comes up constantly with clients who are retiring or leaving a job after 65, and it deserves real attention — not just because of the penalty risk we’ve already covered, but because a slow approval can leave you with an actual gap in coverage if you time it too tightly. My standard advice: start this process at least 2 to 3 months before you need Part B to actually begin, not the week your employer coverage ends. If your former employer is slow to complete their portion of Form CMS-L564, that alone can hold up the entire application — so it’s worth following up with your HR or benefits department directly rather than assuming it’s been submitted.

Practical tips to avoid delays

  • Apply online through SSA.gov whenever possible. It’s consistently the fastest method — mailed or faxed forms are more prone to getting lost or delayed.
  • If you’re on a Special Enrollment Period, submit Form CMS-L564 alongside Form CMS-40B, not separately. They need to arrive together, and one incomplete form can stall the whole application.
  • Expect a short intake lag even with online applications. It can take several business days for an online submission to actually appear on a local Social Security agent’s screen — don’t panic if you call shortly after applying and they say they don’t see it yet.
  • Once approved, you don’t have to wait for your physical card. Your Medicare Beneficiary Identifier typically appears in your online Social Security or Medicare.gov account within a day or two of approval, and you can print a temporary card from there — the physical card generally arrives by mail within about 30 days.

Excess Charges: The Cost Almost Nobody Knows to Ask About

Here’s a detail that surprises even people who’ve been on Medicare for years: not every doctor who accepts Medicare agrees to accept Medicare’s approved amount as full payment.

Providers fall into three categories:

  • Participating providers accept Medicare assignment, meaning they agree to accept the Medicare-approved amount as payment in full. This covers the vast majority of providers — roughly 98% of doctors nationally.
  • Non-participating providers still accept Medicare patients but haven’t agreed to accept the standard rate. They can charge an excess charge of up to 15% above the Medicare-approved amount.
  • Opted-out providers have left the Medicare system entirely and can charge whatever they want under a private contract — Medicare pays nothing at all for care from these providers, except in emergencies.

How excess charges actually work: if the Medicare-approved amount for a service is $300 and you see a non-participating provider, they can legally charge up to an additional $45 (15%) on top, for a total bill of $345 — and that excess amount doesn’t count toward your Part B deductible.

Eight states currently prohibit or limit excess charges entirely: Connecticut, Massachusetts, Minnesota, New York, Ohio, Pennsylvania, Rhode Island, and Vermont. If you live in one of these states, you’re generally shielded from excess charges from providers within your state — though you could still face them if you receive care from a non-participating provider elsewhere.

Paul’s Honest Take: This is exactly why Medigap Plan G matters so much for people who want maximum flexibility. Plan G covers excess charges in full — Plan N does not. If you’re the kind of person who wants the freedom to see any doctor without worrying about billing surprises, that distinction is worth understanding clearly before you pick between the two. And regardless of which plan you choose, it’s always worth asking a new provider directly whether they accept Medicare assignment before your first appointment.

The HSA Rule: Part B Closes the Door Too

If you’re hoping to keep contributing to a Health Savings Account, know this clearly: enrolling in Part B — or any part of Medicare — ends your ability to make new HSA contributions. This isn’t unique to Part B; it applies the moment you enroll in Medicare in any form, including premium-free Part A.

If keeping your HSA active matters to you, the only way to legally delay both Part A and Part B is through qualifying employer coverage — which, as covered above, generally requires an employer with 20 or more employees. And because Part A enrollment can be backdated up to 6 months once you do enroll, it’s smart to stop HSA contributions 6 months before you plan to sign up for Medicare or file for Social Security, whichever comes first.

Frequently Asked Questions

Is there a cap on what I’ll pay for Part B services in a year? Not under Original Medicare alone — the 20% coinsurance has no yearly limit. A Medigap policy or Medicare Advantage plan is what actually caps your exposure.

What happens if I don’t sign up for Part B on time? You’ll generally face a permanent 10% penalty on your premium for every 12-month period you went without coverage, unless you qualify for a Special Enrollment Period through active employer coverage.

Do I need Part B if I have good coverage through a small employer? Almost certainly yes. If your employer has fewer than 20 employees, Medicare becomes your primary insurer at 65 regardless of your job coverage, and not enrolling can leave you exposed to unpaid claims and a lifelong penalty.

Do veterans need Medicare Part B if they have VA benefits? Generally, yes. Medicare and VA benefits don’t coordinate — each only pays for care within its own system — and VA coverage doesn’t exempt you from Medicare’s enrollment deadlines or penalties.

What is a Part B excess charge? An additional charge, up to 15% above the Medicare-approved amount, that a non-participating provider can legally bill you. It doesn’t count toward your deductible, and only Medigap Plan G (among current plans) covers it in full.

Can I keep contributing to my HSA if I enroll in Part B? No. Enrolling in any part of Medicare, including Part B, ends your HSA contribution eligibility going forward.

How long does it take to get approved for Part B? It depends on the enrollment window. Initial Enrollment Period applications typically process in 2–4 weeks. Special Enrollment Period applications, used when leaving employer coverage, generally take 4–8 weeks since Social Security must manually verify your prior coverage using Form CMS-L564. Start the process at least 2–3 months before you need coverage to begin, especially when coordinating around a job ending.

The Bottom Line

Part B is the half of Medicare that covers your everyday medical care — and it’s also where the real financial exposure of Original Medicare lives, thanks to that uncapped 20% coinsurance. Whether you should enroll at 65, whether you can safely delay, and how much of that exposure you’re carrying all depend on details specific to your situation: your employer’s size, your income, your VA status, and which doctors you actually see.

If you want help sorting out exactly how Part B applies to your specific circumstances — or want to understand how Medigap or Medicare Advantage could close that uncapped coinsurance gap — that’s exactly the conversation I have with clients every day, at no cost to you.

Call 631-358-5793 or visit paulbinsurance.com to set up a time to talk it through.

Paul Barrett, CMIP, is the founder of The Modern Medicare Agency, based in Melville, NY, and has spent 18+ years exclusively helping people navigate Medicare — never life insurance, never annuities, just Medicare. He’s licensed in 37 states, represents more than 40 carriers, and has personally helped over 5,000 clients choose coverage that actually fits their lives.

Figures current as of 2026 and sourced from CMS, Medicare.gov, and the Social Security Administration. Individual circumstances vary, especially around employer coverage, VA benefits, and income-based premiums — always verify your specific situation before making enrollment decisions.

Sources

Related Post

Scroll to Top