Income Annuities for Retirement: Payouts and Tax Basics

Income Annuities for Retirement: Payouts and Tax Basics

What if part of your retirement income arrived on a schedule you could count on? Using annuities for guaranteed retirement income can turn a lump sum into regular payments, starting soon after purchase or at a later date. Depending on the payout option, payments may continue for life or for a set period.

It’s understandable to want dependable income while feeling unsure about giving up access to money or choosing a payout that fits your needs. The details matter: payments differ depending on whether coverage is for one person, two people, or a set period. How you fund the annuity also affects its tax treatment.

This guide explains how income annuities work, what to consider when comparing payout options, and how taxes generally apply when you buy an annuity with money that has already been taxed. You’ll also learn how lifetime payments may fit alongside other retirement income, helping you weigh the trade-offs more clearly.

Key Takeaways

  • Understand how income annuities turn savings into scheduled retirement payments, and how immediate and deferred options differ.
  • Consider how lifetime payments may help address the risk of outliving savings alongside Social Security, pensions, and other retirement income.
  • Compare single-life, joint-life, and period-certain payouts to see how payment duration and survivor protection can affect your choice.
  • Learn how using after-tax money affects the taxable and tax-free portions of annuity payments.
  • See which personal factors matter when weighing guaranteed income against flexibility and access to savings.

What is an income annuity?

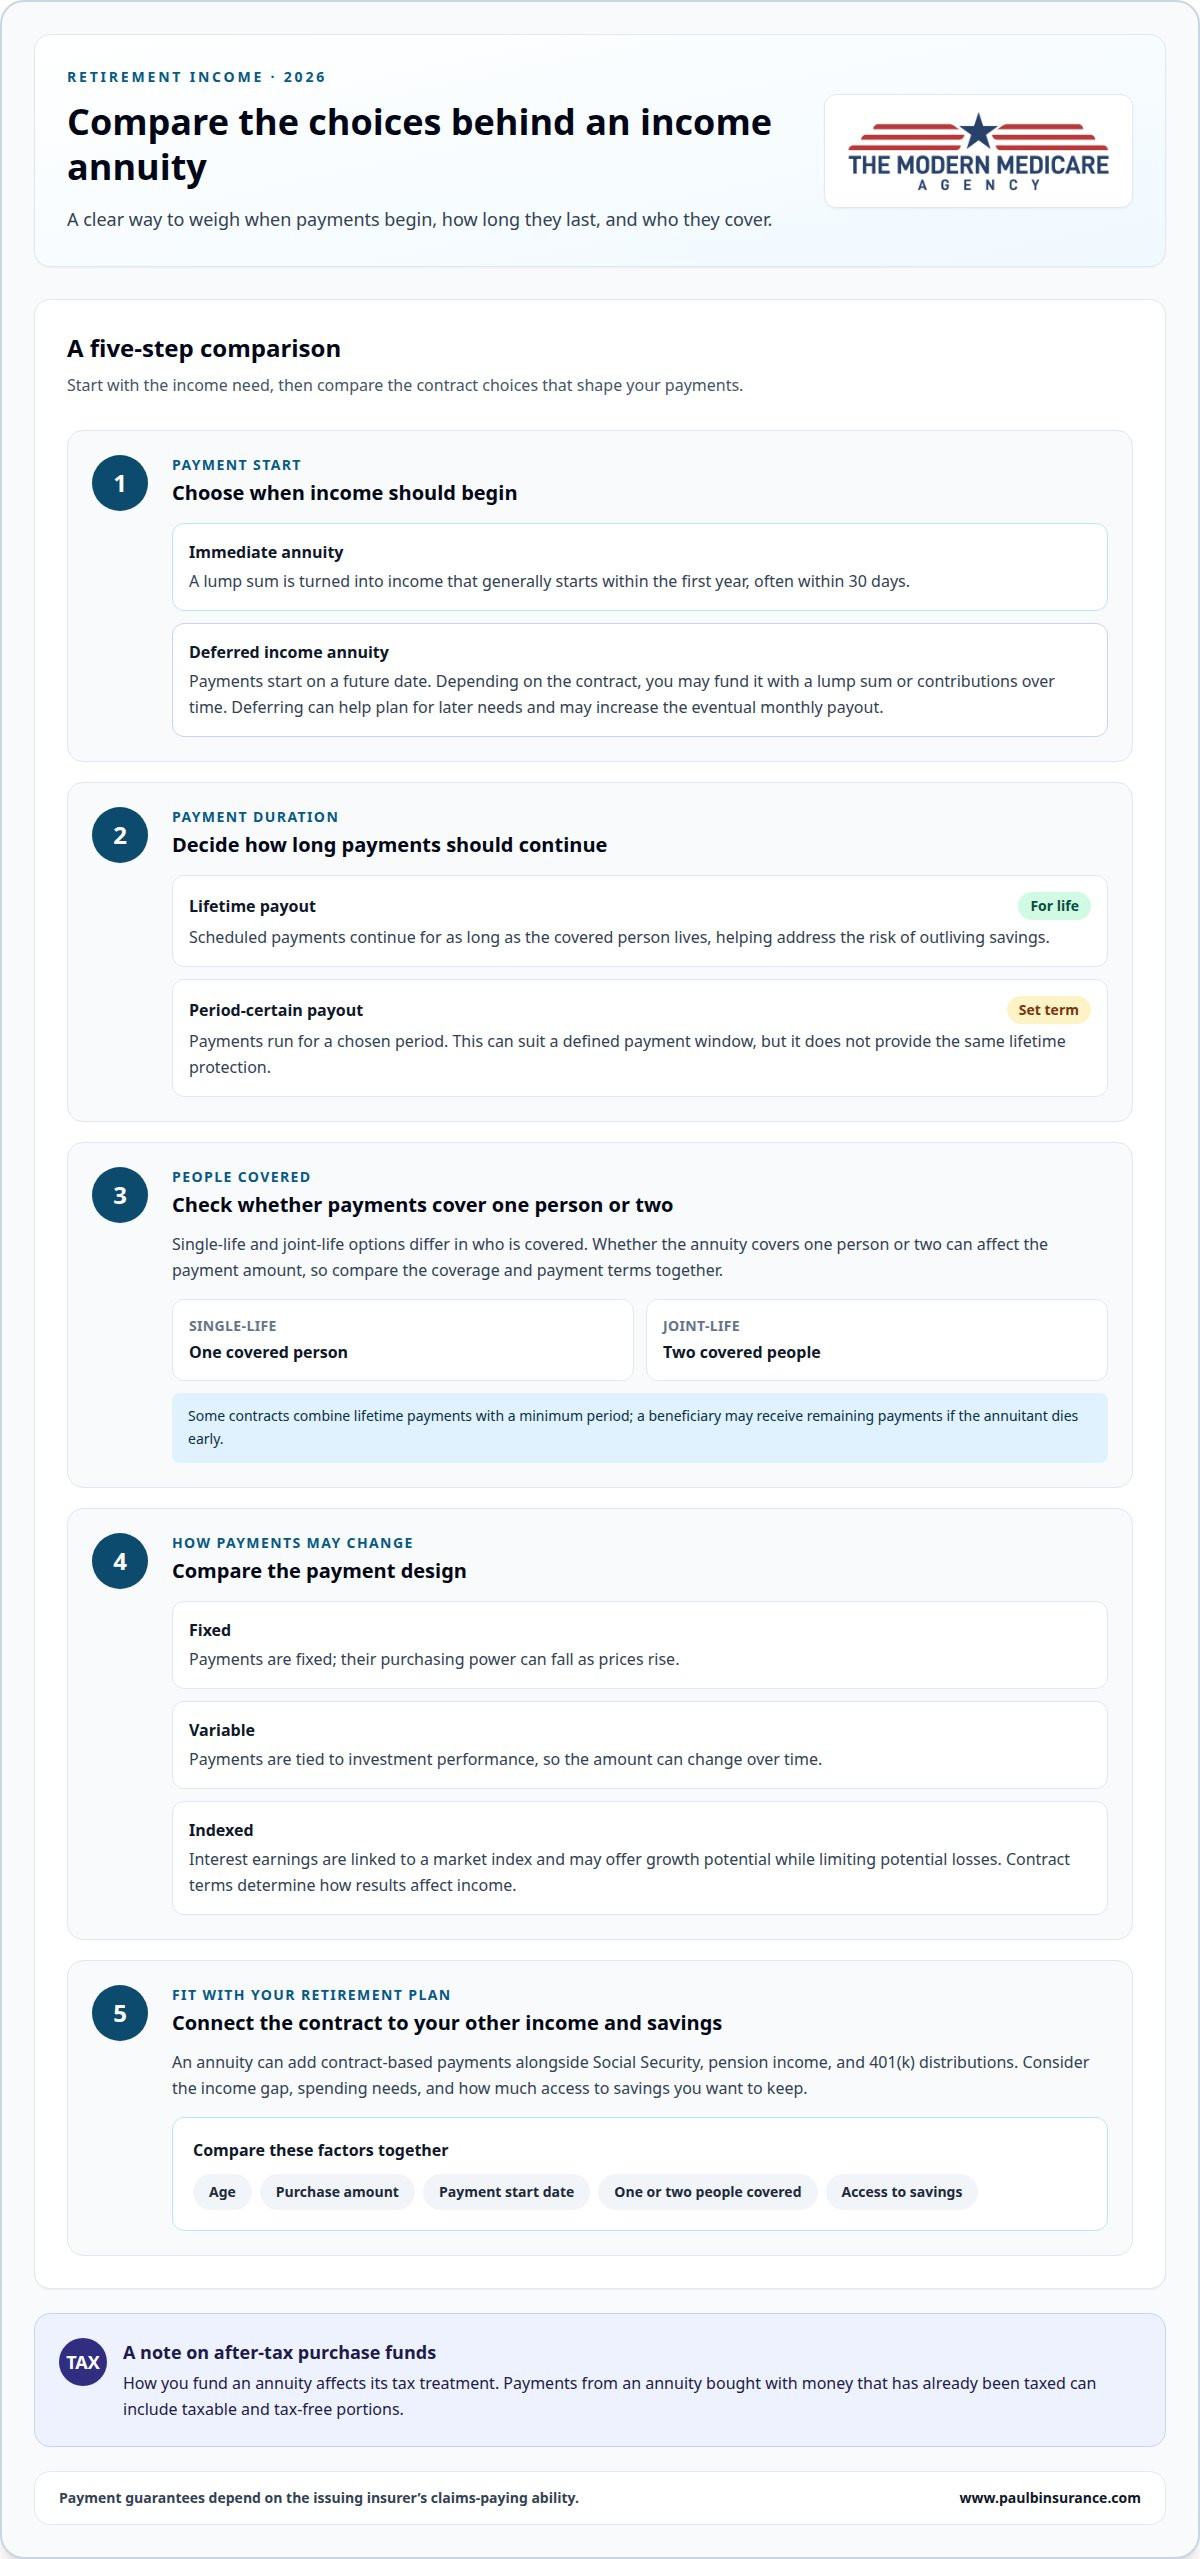
An income annuity is a contract that turns money paid to an insurer into scheduled retirement payments. A retirement plan using annuities for guaranteed retirement income can provide payments soon after purchase or at a later date. With an immediate annuity, you generally pay a lump sum and begin receiving income within the first year, often within 30 days. The contract sets the payment terms.

A deferred income annuity starts payments on a future date. Depending on the contract, you may fund it with contributions over time or a lump sum. Deferring payments can help plan for later retirement needs and may increase the eventual monthly payout. Both immediate and deferred lifetime annuities can be structured to provide income for life.

The key difference is when income begins. An immediate annuity may suit someone who wants to turn a lump sum into payments now. A deferred option may suit someone planning for income later, such as when other income sources change. The start date helps clarify the role you want the annuity to play in your retirement plan.

How do annuities compare with Social Security, pensions, and systematic withdrawals? Social Security and pensions provide income under their own rules, while systematic withdrawals draw on savings and can vary with investment performance and withdrawal choices. An annuity can add contract-based payments alongside these sources rather than replace them.

How should retirees choose and buy an annuity for guaranteed income? Match the payment start date and duration to the income need, then consider other income, access to savings, and payout options. Payments depend on factors such as age, purchase amount, start date, and whether the annuity covers one person or two.

What are current fixed immediate annuity rates in the United States? In 2026, the payout depends on interest rates, the purchaser’s age, the premium, and the payment structure. Compare the payment amount and contract terms together, since a rate by itself doesn’t show how the chosen option fits your income needs.

What are the risks of using annuities for retirement income, including inflation and insurer failure? Fixed payments may lose purchasing power as prices rise, and payment guarantees depend on the issuing insurer’s claims-paying ability. The Federal Deposit Insurance Corporation says CDs are insured up to $250,000 per deposit; that protection is separate from an annuity contract. Should an annuity cover part or all of a retirement portfolio? It can provide one income source alongside investments, Social Security, or a pension, while other savings remain available for changing needs. Taxable annuity withdrawals taken before age 59½ may incur a 10% early withdrawal penalty, according to the Internal Revenue Service.

Lifetime income and protection from outliving savings

A lifetime income annuity can continue scheduled payments for as long as the covered person lives. It can sit alongside Social Security, pension income, and 401(k) distributions as one part of a retirement income plan.

Lifetime and Period-Certain Payouts

A lifetime payout continues for the covered person’s life, while a period-certain payout runs for a chosen term. This distinction matters when weighing income for life against payments for a defined span. Some contracts combine both: payments last for life, with a minimum period during which a beneficiary may receive remaining payments if the annuitant dies early.

Variable and Indexed Lifetime Income

A variable lifetime income annuity ties payments to investment performance, so the amount can change over time. An indexed lifetime income annuity links interest earnings to a market index and may offer growth potential while limiting potential losses. These designs balance income consistency and growth differently. Compare how the contract calculates payments and what happens when investment results change.

The central benefit is longevity protection: an income annuity can keep paying even if retirement lasts longer than expected. Some contracts continue payments if the purchaser lives past age 100. That doesn’t mean every dollar of savings should go into an annuity. The premium, other income, spending needs, and access to savings all matter when deciding how much income to place under contract.

Consider the income gap rather than treating the annuity as a complete retirement plan. For example, Social Security and a pension may cover some regular expenses, while a lifetime payout can add income to cover the remaining gap. A period-certain option instead sets a payment window, which may suit a temporary need but does not provide the same lifetime protection.

What protections apply if an insurance company that sells an annuity becomes insolvent? The contract’s payment guarantees depend on the issuing company’s claims-paying ability. The insurer’s ability to meet its obligations is therefore an important consideration alongside the payout design.

Before choosing a lifetime payout, compare how payments change under each design, whether the annuity covers one or two people, and how a period-certain feature affects beneficiaries. Also consider inflation: a fixed payment can lose purchasing power as prices rise. Variable and indexed designs handle growth differently, but the contract terms determine how results affect income.

For a clearer comparison, connect the payout choice to the income you need from savings and the income already provided by Social Security or a pension. A conversation about annuity options can help you understand how these contract choices fit together.

Period-certain, single-life, and joint-life payout options

The payout choice determines who receives income and how long payments continue. Before choosing, compare the payment amount, coverage period, and any continuing benefit for a surviving person.

A single-life payout covers one person, while a joint-life payout covers two. Joint coverage can continue payments for a surviving spouse, though the monthly amount may be lower.

A period-certain option guarantees payments for a defined term, commonly five to 20 years. It can be paired with lifetime income, so payments continue for life, with the period guarantee providing a minimum payment window. If the covered person dies during the selected period, the remaining guaranteed payments can go to a beneficiary under the contract.

Payment frequency matters for budgeting. The examples above use monthly payments, which can help align income with regular household bills. The contract sets the schedule and payout terms, so compare those details alongside the amount. A period-certain payout has a defined end, while a lifetime payout depends on the covered person’s lifespan.

Some fixed indexed annuities offer a guaranteed minimum withdrawal benefit, or GMWB, rider. Depending on the company and product, this feature may be optional or built into the contract. It can provide a withdrawal benefit under stated terms, but it is distinct from choosing a single-life, joint-life, or period-certain payout. Read how the rider works with the annuity’s income options before treating it as a death benefit.

Death-benefit options can affect what a beneficiary receives, and guarantees depend on the issuing company’s claims-paying ability. Life insurance and an annuity death benefit are different arrangements, so don’t assume one automatically replaces the other. For each option, identify who is covered, what triggers payment, and whether payments continue after the annuitant dies.

A higher payment for one person may not meet a couple’s survivor-income needs. A joint payout or period guarantee may address those needs differently, while changing the income available during the annuitants’ lifetimes.

Tax treatment of payments from after-tax purchase funds

In the United States, an annuity bought with after-tax money is generally called a nonqualified annuity. Each payment can include a taxable earnings portion and a tax-free return of the purchase funds.

The tax-free portion continues until total payments received equal the original purchase payment. After that, remaining payments are generally taxable as income. For example, a payment may include both earnings and returned principal, so the full amount is not necessarily taxable from the start. New York Life says annuity income payments are taxed as ordinary income, not capital gains.

That treatment differs from an annuity funded with pretax money from an IRA or 401(k), where payments are subject to tax. The source of the money matters. Keep the purchase records and payment statements together, so the amount already returned can be tracked accurately for tax reporting in 2026.

Consider liquidity before buying. An income annuity is designed to pay on a schedule, not to function like a checking account. The contract sets the payment terms, and access to future payments depends on its provisions. Before committing money to scheduled income, consider how much savings you need to keep available for unexpected expenses.

Predictability depends on the payout selected. A fixed payment can make monthly budgeting easier because the amount follows the contract terms. A variable payment can change with investment performance. Compare the payment schedule with recurring expenses, and consider how inflation could affect what a fixed amount buys over time.

When do payments begin? An immediate income annuity generally starts within the first year after purchase, often within 30 days. A deferred income annuity begins later, according to its selected start date. That timing affects both cash flow and when payments enter the retiree’s income plan.

What fees, commissions, and surrender charges do annuities have? Costs depend on the contract and selected features. Charges may include fees, rider costs, or surrender charges for certain withdrawals. Commission arrangements also vary. Review the contract’s cost disclosures and withdrawal terms together, since access restrictions and charges can affect the money available.

Before choosing, compare the after-tax purchase amount, payment timing, and contract access terms side by side. This helps show how much scheduled income you’ll receive, how payments are treated for tax purposes, and what savings remain available outside the annuity.
Income Annuities for Retirement: Payouts and Tax Basics

Guaranteed retirement income for life or a set period

An income annuity can create a payment stream for a defined period or for life. The right term depends on whether your priority is covering a temporary income gap or protecting against outliving your savings.

A set period can match a known need, such as providing income before another retirement source begins. Lifetime payments address a different concern: continuing income no matter how long retirement lasts. These options serve different purposes, so compare the payment term with expected expenses and other income rather than treating the largest payment as the only measure.

Consider a hypothetical 60-year-old woman with a $36,000 annual retirement income gap who plans to begin income at age 70. One approach is to plan for payments starting at that future date. Another is a fixed indexed annuity with a guaranteed minimum withdrawal benefit rider, using a stated withdrawal rate to provide the income. The example shows why the start date and payment design matter as much as the word “guaranteed.”

A guaranteed minimum withdrawal benefit, or GMWB, can be optional or built into a fixed indexed annuity, depending on the insurance company and product. It can provide a defined withdrawal benefit under the contract’s terms. This feature is not the same as a life payout: the contract explains how withdrawals work and whether the benefit is designed to continue for life or for a set period.

Indexed lifetime income links interest earnings to a market index. It may offer growth potential while limiting potential losses. A fixed indexed annuity is not directly invested in the market, and its contract determines how index-linked interest affects the policy. Understand the difference between potential interest growth and the income promise before deciding what role it should play.

There is an important limit to the word “guaranteed.” Annuity payment guarantees, including death benefits, depend on the issuing life insurance company’s claims-paying ability. The guarantee is tied to the company’s ability to meet its obligations, not simply to the payout label. Review the insurer and contract terms as part of your decision.

For a practical comparison, write down the income gap, when it begins, how long it needs to last, and which other sources already cover expenses. Then compare a lifetime stream with a set-period stream against those needs. In 2026, that framework can help you focus on the role each contract serves, instead of choosing from a payout figure alone.

Discuss annuity income options to explore how a lifetime or set-period payment stream could fit your retirement income needs.

The Modern Medicare Agency: Annuities

The Modern Medicare Agency offers annuities for people considering how scheduled payments could fit their retirement income. After comparing lifetime and set-period payouts, you may want help understanding which annuity options align with your income goals and need for access to savings. A conversation can clarify the trade-offs, including when payments begin and how payout choices affect income for you or a spouse.

If you’re ready to discuss annuities as part of your retirement income considerations, contact The Modern Medicare Agency.

Make your next retirement-income decision with clarity

Using annuities for guaranteed retirement income is a personal decision shaped by how you want your savings to support daily life. Before choosing, consider what matters most: steady income, flexibility, support for a spouse, or access to savings as needs change. A clear sense of your priorities can make the next conversation more useful.

The Modern Medicare Agency can help you explore annuities and also offers Medicare Advantage Plans, Medicare Supplement (Medigap) Plans, and Medicare Part D Plans. If you’re ready to discuss how an annuity might fit your retirement-income needs, contact The Modern Medicare Agency.

You don’t need to resolve every detail at once. A thoughtful conversation can help you consider your options and choose a next step that feels right for you.

Frequently Asked Questions

How much does a $100,000 annuity pay per month?

A $100,000 immediate annuity for a 65-year-old might pay approximately $600-$700 per month. The actual amount depends on factors such as age, interest rates, and the selected payout option. For example, a single-life payment and a joint-life payment can differ because they cover different people and payment periods. Treat this range as an illustration, not a quote for a specific contract.

Can I access my money if needed?

Access depends on the annuity contract and payout design. An income annuity is intended to convert funds into scheduled payments, so it may not provide the same flexibility as a savings account. Some contracts have withdrawal terms or surrender charges. Consider keeping money available for unexpected costs before allocating funds to future income. The Internal Revenue Service says taxable annuity withdrawals before age 59½ may incur a 10% early withdrawal penalty.

Do you pay taxes on your annuity purchase?

If you purchase an annuity with after-tax money, that money has already been taxed. Tax generally applies to the earnings portion of payments, while the returned purchase amount is treated differently until payments received equal the purchase payment. For example, a payment can include both taxable earnings and a return of after-tax funds. The tax result changes when an annuity is funded with pretax retirement money.

If I die unexpectedly, what happens to the money in my annuity?

What happens depends on the payout option and any death-benefit terms in the contract. A period-certain feature may make a beneficiary eligible for remaining guaranteed payments during that period. A life-only payout may not provide the same continuation after the annuitant dies. Annuity guarantees, including death benefits, depend on the issuing company’s claims-paying ability, so the contract determines what beneficiaries receive.

What Factors Affect Annuity Payout Calculations?

Payout calculations depend on the purchase amount, the covered person’s age, when payments begin, and the selected payment structure. Interest rates also affect immediate annuity payments. For example, covering two lives or adding a guaranteed payment period can change the payment compared with covering one person for life. Compare options using the same purchase amount and start date to see how each choice changes income.

What are mortality credits?

Mortality credits describe how a pool of annuity buyers can support lifetime payments for people who live longer. The insurer uses pooled funds to meet payment obligations across the group, rather than treating every contract as a separate account that must return its full purchase amount to one person. This helps explain why lifetime income can continue even when an individual’s total payments exceed their original contribution.

What is a lifetime annuity?

A lifetime annuity is arranged to make payments for the covered person’s lifetime. A single-life option covers one person, while a joint-life option can cover two. For example, a couple may consider joint coverage if continuing income for a surviving spouse matters. The payment amount and what happens after death depend on the contract’s payout terms and any selected period guarantee.

What is guaranteed income?

Guaranteed income is a stream of payments promised under an agreement, such as an annuity contract. It can make part of retirement cash flow more predictable than withdrawals that depend on investment performance. The promise comes from the issuing insurance company, and annuity payment guarantees depend on that company’s claims-paying ability. Review the contract to understand who receives payments, when they start, and how long they continue.
Paul Barrett

Article by

Paul Barrett

Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.

He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.

📞 631-358-5793 | paulbinsurance.com
What Is Medicare Part B and What Does It Actually Cover?

The complete guide to Medicare’s medical insurance — every service it covers, exactly what it costs in 2026, how it works with group insurance and VA benefits, and the excess charges most people have never heard of until they get a surprise bill.

The Short Answer

Medicare Part B is medical insurance — it covers doctor visits, outpatient care, preventive services, durable medical equipment, and more. Unlike Part A, Part B is not premium-free for anyone: everyone pays a monthly premium (202.90in2026formostpeople),anannualdeductible(283), and 20% coinsurance on most covered services, with no yearly cap on that 20% under Original Medicare alone. Whether you need to enroll at 65, and whether delaying is safe, depends heavily on your employment status and your employer’s size — getting this wrong is one of the most consequential and permanent mistakes in all of Medicare.

Key Takeaways

  • Part B is never premium-free — everyone pays a monthly premium, and higher earners pay significantly more through IRMAA.
  • The 20% coinsurance under Original Medicare alone has no yearly cap — this is the single biggest financial risk in Medicare, and it’s the reason Medigap and Medicare Advantage exist.
  • Whether you can safely delay Part B without a penalty depends on your employer’s size: 20+ employees generally allows delay; fewer than 20 generally does not.
  • Missing your enrollment window triggers a permanent 10% penalty for every 12-month period you went without coverage.
  • Veterans can and generally should enroll in Part B even with VA benefits, since Medicare and VA coverage don’t coordinate — each only pays for care received within its own system.
  • “Excess charges” from non-participating providers can add up to 15% on top of what Medicare approves, and only some Medigap plans protect you from them.

What Part B Actually Covers

While Part A handles hospital room and board, Part B is the half of Original Medicare that covers medical care and most services delivered outside a hospital admission — doctor visits, outpatient procedures, and ongoing medical needs.

What’s covered

  • Doctor visits — primary care and specialists
  • Outpatient surgeries and procedures
  • Diagnostic lab work, X-rays, and MRIs
  • Emergency room visits
  • Ambulance services
  • Outpatient mental health care
  • Physical, occupational, and speech therapy
  • Chemotherapy and radiation received in an outpatient clinic
  • Durable Medical Equipment (DME) — wheelchairs, oxygen equipment, blood sugar monitors, walkers, and similar equipment
  • Ambulatory surgical center services

Preventive services: the part Medicare gets genuinely right

Most preventive services are covered at 100%, with no deductible and no copay, as long as your provider accepts Medicare assignment. This includes:

  • Your one-time “Welcome to Medicare” wellness visit, available within your first 12 months on Part B
  • Annual wellness visits after that
  • Flu shots and most other recommended vaccines
  • Mammograms
  • Colonoscopies and other cancer screenings
  • Diabetes and cardiovascular screenings
  • Many other screenings recommended by the U.S. Preventive Services Task Force

Paul’s Honest Take: This is one of the most underused parts of Medicare, full stop. I’ve had clients who paid for a private physical every year out of habit and never realized their annual wellness visit through Medicare was completely free. If you haven’t used your Welcome to Medicare visit or your annual wellness visit, that’s real value sitting on the table.

What’s NOT covered

  • Routine dental care — cleanings, fillings, dentures, extractions
  • Routine vision exams and eyeglasses
  • Hearing aids (though diagnostic hearing tests ordered by a doctor may be covered)
  • Long-term custodial nursing home care — help with daily living activities, as opposed to short-term skilled or medical care
  • Routine prescription drugs you pick up at a retail pharmacy — that’s Part D’s job, not Part B’s
  • Cosmetic surgery, unless medically necessary (such as reconstruction after an accident or mastectomy)
  • Most care received outside the United States, with very limited exceptions
  • Routine foot care, such as nail trimming, in the absence of a qualifying medical condition
  • Acupuncture, except for a narrow, specific chronic low back pain benefit
  • Concierge medicine fees and membership-style charges some practices add on top of standard care
  • Long-term care insurance-style services, including most home-based personal care that isn’t tied to a skilled medical need

Paul’s Honest Take: The dental and vision exclusions are the ones that surprise people most, especially since they’re such routine parts of healthcare for most adults. This is exactly why so many Medicare Advantage plans build dental, vision, and hearing benefits into their coverage — Original Medicare was simply never designed to include them, and that gap doesn’t go away on its own.

What Part B Costs in 2026

Part B has three separate cost components, and understanding all three matters:

Cost Component

2026 Amount

Standard monthly premium

$202.90

Annual deductible

$283

Coinsurance on most covered services

20%

The premium is deducted automatically from your Social Security check if you’re already collecting benefits. If you’re not yet collecting Social Security, you’ll receive a bill, typically every three months.

The deductible works differently than Part A’s — it’s a straightforward annual figure. You pay the first $283 of Medicare-approved outpatient costs each calendar year, and then Medicare’s cost-sharing kicks in.

The coinsurance is where the real risk lives. After your deductible is met, Medicare pays 80% of the Medicare-approved amount for most covered services, and you’re responsible for the remaining 20%. There is no yearly cap on this 20% under Original Medicare alone. If you have a $100,000 course of cancer treatment, your 20% share is $20,000 — unless you have a Medigap policy or Medicare Advantage plan absorbing that cost.

Paul’s Honest Take: I put this in bold because it’s genuinely the single most important number in this entire guide. That uncapped 20% is the whole reason Medigap and Medicare Advantage exist as products in the first place. Original Medicare by itself was never designed to protect you from a truly expensive year — it was designed to cover 80% of it and leave the rest to you.

IRMAA: What Higher Earners Actually Pay

If your income is above certain thresholds, you’ll pay more for Part B through the Income-Related Monthly Adjustment Amount (IRMAA) — based on your tax return from two years prior. For 2026, that means your 2024 income determines your premium tier.

2024 Income (Individual)

2024 Income (Married, Joint)

Total Part B / Month

$109,000 or less

$218,000 or less

$202.90

$109,001 – $137,000

$218,001 – $274,000

$284.10

$137,001 – $171,000

$274,001 – $342,000

$405.80

$171,001 – $205,000

$342,001 – $410,000

$527.50

$205,001 – $499,999

$410,001 – $749,999

$649.20

$500,000 and above

$750,000 and above

$689.90

At the top tier, you’re paying more than three times the standard premium. If your income has recently dropped — retirement, the loss of a spouse, or certain other life-changing events — you can appeal your IRMAA determination using Form SSA-44.

Do You Have to Enroll? And What Happens If You Don’t?

Technically, Part B is optional — Medicare won’t force you into it. But opting out without a valid alternative is genuinely risky, because of how the penalty structure works.

If you don’t sign up during your Initial Enrollment Period (the 7-month window around your 65th birthday) and you don’t have qualifying employer coverage, you’ll face a permanent 10% penalty added to your premium for every full 12-month period you went without Part B. That penalty doesn’t expire — you pay it for as long as you have Part B, which for most people means for the rest of your life.

Example: If you delayed enrollment by 24 full months without a valid exception, you’d pay an extra 20% on top of the standard $202.90 premium in 2026 — roughly $40.58 more, every month, permanently.

How Part B Works with Group Insurance

Just like Part A, whether you can safely delay Part B without penalty comes down to one specific number: how many employees your company has.

Companies with 20 or more employees: If you or your spouse are actively working and covered by a genuine group health plan, your workplace insurance is primary, and you can legally delay Part B without any penalty. When that employment or coverage eventually ends, you get an 8-month Special Enrollment Period to enroll in Part B penalty-free.

Companies with fewer than 20 employees: Medicare automatically becomes your primary insurer at 65, regardless of your employment status. You need to enroll in Part B right on schedule. If you don’t, your small employer’s plan can legally refuse to pay claims that Medicare should have covered first — potentially leaving you responsible for the full cost.

Paul’s Honest Take: I say this in nearly every guide I write, because it’s genuinely one of the costliest misunderstandings I encounter: “I have good coverage at work” and “I’m protected from Medicare’s enrollment deadlines” are two completely different statements, and whether the second one is true depends entirely on your employer’s size — not how generous the coverage feels. Confirm the actual employee count before you decide to delay anything.

Retiree Coverage Is Not the Same as Active Employer Coverage

This is a distinction that catches a genuinely large number of people off guard: the “20 or more employees” exception only applies to active employment. If you retire and your former employer offers you retiree health benefits — sometimes a genuinely good, comprehensive plan — that coverage does not create a Special Enrollment Period the way active group coverage does, and it does not exempt you from enrolling in Part B on time.

Paul’s Honest Take: I’ve seen this mistake more than once, and it’s an especially painful one because it happens to people who did everything right during their working years. Someone retires with a strong retiree health plan from a large employer, assumes it works the same way their active coverage did, and delays Part B — only to find out later that retiree coverage was never a valid reason to delay in the first place. The moment you stop actively working, that clock starts, regardless of how good your retiree plan looks on paper. If you’re retiring and keeping employer retiree benefits, treat enrolling in Part B as something to handle right on schedule, not something retiree coverage lets you postpone.

Why You Need Both Part A and Part B for Medigap or Medicare Advantage

Here’s a foundational requirement worth understanding clearly, since it shapes every other coverage decision in Medicare: you must be enrolled in both Part A and Part B before you can buy a Medigap policy or enroll in a Medicare Advantage plan. Neither product exists as a standalone substitute for Original Medicare — both are built specifically to work alongside it.

  • Medigap fills the cost-sharing gaps left by Original Medicare (Parts A and B) — it has nothing to fill in if you’re not enrolled in both parts to begin with.
  • Medicare Advantage legally must provide at least the same coverage as Parts A and B combined, which is only possible because you’re required to be enrolled in both before a Medicare Advantage carrier can enroll you.

Paul’s Honest Take: This surprises people who assume they can somehow “skip” Part B and go straight into a Medicare Advantage plan to avoid the extra premium. It doesn’t work that way — Part B enrollment, and its premium, is a prerequisite either way, whether you end up on Original Medicare with Medigap or on a Medicare Advantage plan. There’s no path through Medicare that avoids the Part B premium once you’re actually using the system.

Does Medicare Work If You’re a Veteran?

Yes — and if you have VA health benefits, understanding how the two systems relate is genuinely important, because they work differently than most people assume.

Medicare and VA benefits do not coordinate. These are two entirely separate systems that each pay only for care received within their own network. Medicare doesn’t pay for care you receive at a VA facility, and VA benefits don’t pay for care you receive from a non-VA doctor or hospital. You, the veteran, choose which system to use each time you seek care.

Here’s the critical point: having VA benefits does not exempt you from Medicare’s enrollment deadlines. VA coverage is not considered a qualifying reason to delay Part B without penalty. If you don’t enroll in Part B during your Initial Enrollment Period and you’re relying solely on VA benefits, you can still trigger the permanent late enrollment penalty.

Why the VA itself recommends enrolling in Medicare anyway:

  • It gives you access to civilian doctors and hospitals outside the VA system
  • VA healthcare funding depends on annual Congressional appropriations, which isn’t guaranteed to remain stable
  • If VA authorizes only part of your needed care at a non-VA facility, Medicare can help cover the rest
  • Having both gives you meaningfully more flexibility and security than relying on either system alone

Paul’s Honest Take: This is one of the most common misconceptions I run into with veterans specifically, and it’s an expensive one to get wrong. Good VA coverage feels like it should be enough, and it might genuinely handle most of your care — but it doesn’t protect you from the Part B enrollment clock the way employer coverage from a large company can. The VA itself actively encourages enrolling in Medicare Parts A and B for exactly this reason. If you have VA benefits and are approaching 65, this is worth a direct conversation before you assume you’re covered.

Veterans who enroll in Part B can also purchase a Medigap policy, which can be particularly valuable if you use non-VA providers regularly — though if you primarily rely on VA facilities for most of your care, the value of an added Medigap policy may be more limited, and worth weighing carefully.

How Long Does It Actually Take to Get Part B Approved?

This is one of the most practical, and most overlooked, pieces of planning — especially if you’re leaving a job after 65 and coordinating your Part B start date around the end of your employer coverage. Applying isn’t instant, and the timeline depends heavily on which enrollment window you’re using.

Enrollment Situation

Typical Processing Time

When Coverage Actually Starts

Initial Enrollment Period (around 65)

2–4 weeks, sometimes up to 6

1st of your birthday month (if applied in the 3 months before) or 1st of the month after you apply (if applied during or after your birthday month)

Special Enrollment Period (leaving employer coverage)

4–8 weeks, sometimes longer

1st of the month after your application is submitted

General Enrollment Period (Jan 1–Mar 31, missed window)

4–6 weeks

1st of the month after you apply

Why the Special Enrollment Period takes longer: applying after leaving employer coverage requires two forms, not one — Form CMS-40B (the actual Part B application) and Form CMS-L564 (Request for Employment Information), which your employer needs to complete to verify you had qualifying coverage. Social Security has to manually review both, which is exactly why this route consistently takes longer than a standard Initial Enrollment Period application.

Paul’s Honest Take: This timeline question comes up constantly with clients who are retiring or leaving a job after 65, and it deserves real attention — not just because of the penalty risk we’ve already covered, but because a slow approval can leave you with an actual gap in coverage if you time it too tightly. My standard advice: start this process at least 2 to 3 months before you need Part B to actually begin, not the week your employer coverage ends. If your former employer is slow to complete their portion of Form CMS-L564, that alone can hold up the entire application — so it’s worth following up with your HR or benefits department directly rather than assuming it’s been submitted.

Practical tips to avoid delays

  • Apply online through SSA.gov whenever possible. It’s consistently the fastest method — mailed or faxed forms are more prone to getting lost or delayed.
  • If you’re on a Special Enrollment Period, submit Form CMS-L564 alongside Form CMS-40B, not separately. They need to arrive together, and one incomplete form can stall the whole application.
  • Expect a short intake lag even with online applications. It can take several business days for an online submission to actually appear on a local Social Security agent’s screen — don’t panic if you call shortly after applying and they say they don’t see it yet.
  • Once approved, you don’t have to wait for your physical card. Your Medicare Beneficiary Identifier typically appears in your online Social Security or Medicare.gov account within a day or two of approval, and you can print a temporary card from there — the physical card generally arrives by mail within about 30 days.

Excess Charges: The Cost Almost Nobody Knows to Ask About

Here’s a detail that surprises even people who’ve been on Medicare for years: not every doctor who accepts Medicare agrees to accept Medicare’s approved amount as full payment.

Providers fall into three categories:

  • Participating providers accept Medicare assignment, meaning they agree to accept the Medicare-approved amount as payment in full. This covers the vast majority of providers — roughly 98% of doctors nationally.
  • Non-participating providers still accept Medicare patients but haven’t agreed to accept the standard rate. They can charge an excess charge of up to 15% above the Medicare-approved amount.
  • Opted-out providers have left the Medicare system entirely and can charge whatever they want under a private contract — Medicare pays nothing at all for care from these providers, except in emergencies.

How excess charges actually work: if the Medicare-approved amount for a service is $300 and you see a non-participating provider, they can legally charge up to an additional $45 (15%) on top, for a total bill of $345 — and that excess amount doesn’t count toward your Part B deductible.

Eight states currently prohibit or limit excess charges entirely: Connecticut, Massachusetts, Minnesota, New York, Ohio, Pennsylvania, Rhode Island, and Vermont. If you live in one of these states, you’re generally shielded from excess charges from providers within your state — though you could still face them if you receive care from a non-participating provider elsewhere.

Paul’s Honest Take: This is exactly why Medigap Plan G matters so much for people who want maximum flexibility. Plan G covers excess charges in full — Plan N does not. If you’re the kind of person who wants the freedom to see any doctor without worrying about billing surprises, that distinction is worth understanding clearly before you pick between the two. And regardless of which plan you choose, it’s always worth asking a new provider directly whether they accept Medicare assignment before your first appointment.

The HSA Rule: Part B Closes the Door Too

If you’re hoping to keep contributing to a Health Savings Account, know this clearly: enrolling in Part B — or any part of Medicare — ends your ability to make new HSA contributions. This isn’t unique to Part B; it applies the moment you enroll in Medicare in any form, including premium-free Part A.

If keeping your HSA active matters to you, the only way to legally delay both Part A and Part B is through qualifying employer coverage — which, as covered above, generally requires an employer with 20 or more employees. And because Part A enrollment can be backdated up to 6 months once you do enroll, it’s smart to stop HSA contributions 6 months before you plan to sign up for Medicare or file for Social Security, whichever comes first.

Frequently Asked Questions

Is there a cap on what I’ll pay for Part B services in a year? Not under Original Medicare alone — the 20% coinsurance has no yearly limit. A Medigap policy or Medicare Advantage plan is what actually caps your exposure.

What happens if I don’t sign up for Part B on time? You’ll generally face a permanent 10% penalty on your premium for every 12-month period you went without coverage, unless you qualify for a Special Enrollment Period through active employer coverage.

Do I need Part B if I have good coverage through a small employer? Almost certainly yes. If your employer has fewer than 20 employees, Medicare becomes your primary insurer at 65 regardless of your job coverage, and not enrolling can leave you exposed to unpaid claims and a lifelong penalty.

Do veterans need Medicare Part B if they have VA benefits? Generally, yes. Medicare and VA benefits don’t coordinate — each only pays for care within its own system — and VA coverage doesn’t exempt you from Medicare’s enrollment deadlines or penalties.

What is a Part B excess charge? An additional charge, up to 15% above the Medicare-approved amount, that a non-participating provider can legally bill you. It doesn’t count toward your deductible, and only Medigap Plan G (among current plans) covers it in full.

Can I keep contributing to my HSA if I enroll in Part B? No. Enrolling in any part of Medicare, including Part B, ends your HSA contribution eligibility going forward.

How long does it take to get approved for Part B? It depends on the enrollment window. Initial Enrollment Period applications typically process in 2–4 weeks. Special Enrollment Period applications, used when leaving employer coverage, generally take 4–8 weeks since Social Security must manually verify your prior coverage using Form CMS-L564. Start the process at least 2–3 months before you need coverage to begin, especially when coordinating around a job ending.

The Bottom Line

Part B is the half of Medicare that covers your everyday medical care — and it’s also where the real financial exposure of Original Medicare lives, thanks to that uncapped 20% coinsurance. Whether you should enroll at 65, whether you can safely delay, and how much of that exposure you’re carrying all depend on details specific to your situation: your employer’s size, your income, your VA status, and which doctors you actually see.

If you want help sorting out exactly how Part B applies to your specific circumstances — or want to understand how Medigap or Medicare Advantage could close that uncapped coinsurance gap — that’s exactly the conversation I have with clients every day, at no cost to you.

Call 631-358-5793 or visit paulbinsurance.com to set up a time to talk it through.

Paul Barrett, CMIP, is the founder of The Modern Medicare Agency, based in Melville, NY, and has spent 18+ years exclusively helping people navigate Medicare — never life insurance, never annuities, just Medicare. He’s licensed in 37 states, represents more than 40 carriers, and has personally helped over 5,000 clients choose coverage that actually fits their lives.

Figures current as of 2026 and sourced from CMS, Medicare.gov, and the Social Security Administration. Individual circumstances vary, especially around employer coverage, VA benefits, and income-based premiums — always verify your specific situation before making enrollment decisions.

Sources

Related Post

Scroll to Top