
An annuity and a 401(k) are not rivals so much as two different jobs. A 401(k) is an account that holds investments and grows tax-deferred. An annuity is an insurance contract that can turn savings into income. A “rollover to an annuity” means moving some or all of your 401(k) (or IRA) money into that contract. For some retirees it is a smart way to cover essential bills for life. For others it adds cost and removes flexibility they still need. This guide shows how to tell which group you are in.
TL;DR
- Keeping money in a 401(k) is often easiest and best if the plan has low costs and good investment choices. An annuity makes sense when you want guaranteed income you cannot outlive.
- Inside a 401(k) or IRA, an annuity adds no extra tax deferral. You are paying for the guarantee, not for a tax break.
- Ask for a direct rollover so the money never lands in your hands. That avoids withholding and the 60-day clock.
- Check surrender charges, rider fees and the 10% penalty before age 59½ before you sign anything.
- Taxable withdrawals can raise your Medicare Part B premium two years later, so plan the timing.
Table of Contents
- What is the real difference between a 401(k) and an annuity?
- Is it a good idea to roll a 401(k) into an annuity?
- Do you get a tax advantage from an annuity inside a retirement account?
- How to roll over without a surprise tax bill
- Fees, penalties and contract traps to check first
- What about the 401(k) alternative: staying put or moving to an IRA?
- Your Medicare premiums are part of this decision
- Our perspective: education first, then the product
- Get a second set of eyes before you roll over
- Frequently asked questions
- Sources
What is the real difference between a 401(k) and an annuity?
A 401(k) is a workplace savings plan. You choose from a menu of funds, the balance moves with the market, and you decide when and how much to withdraw once you are eligible. The upside is growth potential and control. The downside is that nothing guarantees how long the money lasts.
An annuity is a contract with an insurance company. You hand over a lump sum or a series of payments, and the insurer agrees to pay you under the contract’s terms, often as income for life. FINRA notes that leaving savings in a defined contribution plan may be the easiest and best choice for many employees, especially when expenses are low and investment options are adequate, while annuitizing all or part of the balance converts it into guaranteed lifetime income.
Here is how they compare on the points that matter most:
| Feature | 401(k) left in place | Annuity (via rollover) |
|---|---|---|
| Main purpose | Save and invest for growth | Turn savings into predictable income |
| Market risk | You carry it | Depends on type: fixed and income annuities shift much of it to the insurer; variable annuities keep it with you |
| Access to cash | Flexible, subject to plan rules and taxes | Often limited, with possible surrender charges |
| Fees | Plan and fund expenses | May include surrender, administrative, mortality and expense, and rider charges |
| Lifetime income guarantee | None | Yes, with the right contract |
| Extra tax deferral | Already tax-deferred | None beyond what the retirement account already gives |
That comparison follows the Investopedia breakdown: annuities can provide guaranteed lifetime income but may carry fees, surrender charges and limited liquidity, while 401(k)s face market swings but may offer more growth potential.
Is it a good idea to roll a 401(k) into an annuity?
It depends on what problem you are trying to solve. Two honest answers sit side by side.
It may make sense when you want lifetime income or protection for your principal. A retiree whose Social Security and pension do not cover rent, utilities, food and insurance premiums can close that gap with an annuity and leave the rest of the portfolio invested.
It may be a poor fit when you need easy access to cash, you are relatively young, or you want hands-on control of your investments. These are the cases CBS News highlights, along with a middle path: roll over only part of the balance to buy an annuity covering core expenses, and keep the remainder invested for growth or flexibility.
That partial approach is the one we see work best for most people. It is rarely all or nothing.
A simple way to size it
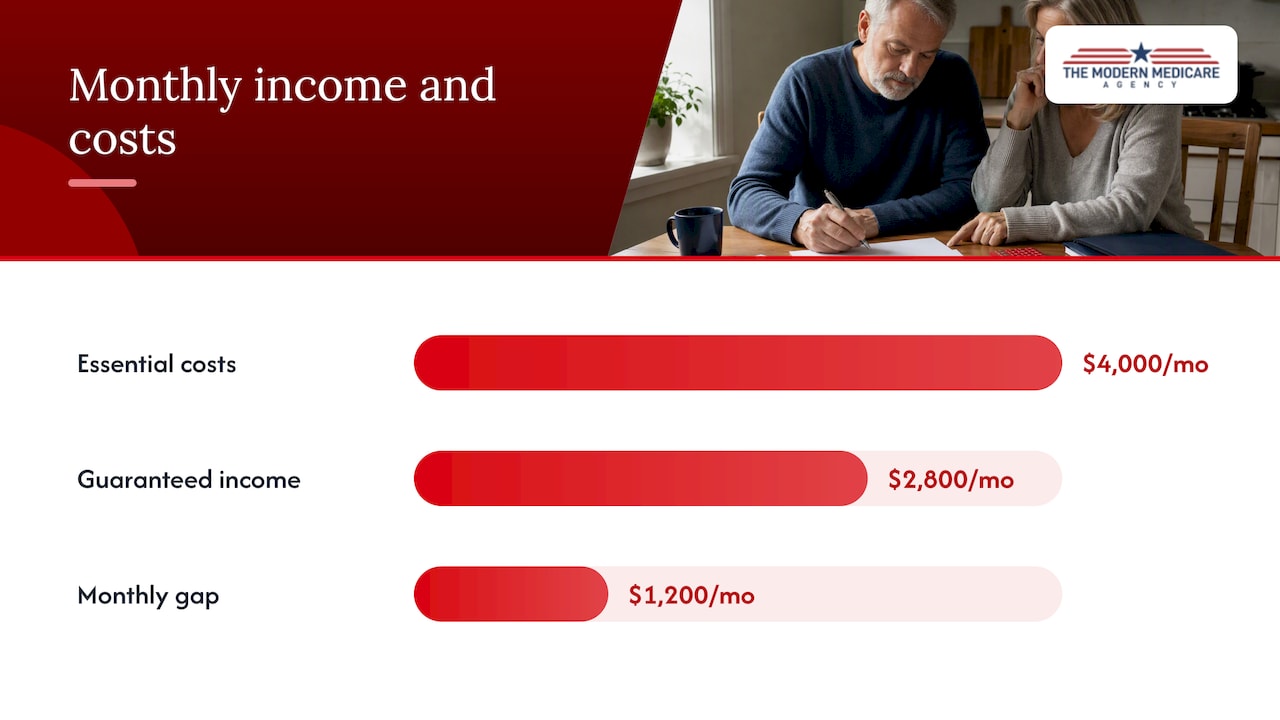
This is an illustration, not a recommendation. Suppose your essential monthly costs are $4,000 and your guaranteed income (Social Security, a pension) covers $2,800. The $1,200 gap is the number to solve. You would ask what portion of your savings, placed in an annuity, could produce that amount, and compare that quote to simply drawing the money from your 401(k). Everything above the gap stays invested for things like travel, gifts and surprise expenses. Quotes change with age, interest rates and contract type, so get several in writing.
Do you get a tax advantage from an annuity inside a retirement account?
No. FINRA points out that an annuity bought within a tax-deferred plan such as a 401(k) or IRA offers no additional tax-deferral benefit, because the account is already tax-deferred. So if your only reason is “tax-deferred growth,” you can get that without paying for an annuity wrapper.
The reasons that do hold up are the guarantees: income for life, protection from a bad market at a bad time, and the discipline of a paycheck you can’t spend down too fast.
A few tax basics to keep straight:
- Money from a traditional 401(k) or IRA is generally taxed as ordinary income when it comes out. A qualified annuity bought with it is taxed the same way when payments arrive.
- A direct rollover of an eligible distribution is reported on Form 1099-R, even when it is not taxable. Expect that form in the mail and keep it with your records.
- Designated Roth 401(k) money is different. The IRS instructions say a designated Roth distribution is qualified and tax-free when made after age 59½ and after the five-tax-year period that starts with your first contribution year. Roth money should usually go to a Roth IRA, not a traditional one.
How to roll over without a surprise tax bill
The method matters as much as the destination.
- Decide the amount first. Choose a portion, not necessarily the whole balance, based on the income gap you want to fill.
- Pick the receiving account. For pre-tax 401(k) money, that is usually a traditional IRA that holds the annuity (an “IRA annuity”). Some employer plans also offer an annuity option inside the plan itself, so ask your plan administrator.
- Request a direct rollover. The plan sends the funds straight to the insurer or custodian. You never take possession, so you avoid the withholding that applies when a check is made out to you.
- Know the 60-day rule if you take a check anyway. If the plan pays you, you generally have 60 days to deposit the money into an IRA. Miss it and the amount can become taxable income, and under 59½ you could owe the 10% penalty on top. Because withholding comes out of a check paid to you, you would also need to replace the withheld amount from other money to roll over the full balance.
- Keep the paperwork. File the Form 1099-R with your tax records and confirm the deposit posted to the right contract.
If you are moving between IRAs or annuities, an exchange may not trigger a taxable event when the tax rules are followed. Investor.gov cautions that it can still carry a surrender charge on the old contract and start a new surrender period on the new one. That is the part people overlook.
Fees, penalties and contract traps to check first
Annuities are not uniformly good or bad. They vary enormously, and the cost is in the details. FINRA lists the charges to look for: surrender charges, mortality and expense risk charges, administrative fees and rider costs. Variable annuities may have surrender periods of eight years or more, and withdrawals before age 59½ may trigger a 10% tax penalty.
Before you sign, get answers to these in writing:
- How long is the surrender period, and what does the schedule look like? A decreasing schedule, for example, means leaving early costs less each year.
- How much can I withdraw each year without a charge? Many contracts allow a free withdrawal amount.
- What are all the annual fees, including any rider that adds an income guarantee?
- Is there a market value adjustment? Some contracts can reduce your value if you withdraw or transfer before a stated term ends, as an SEC filing for one variable annuity describes.
- What is the bonus really costing? Bonus credits can look generous, but the SEC has warned that on some variable annuities they may be outweighed by higher expenses.
- Who pays the agent, and how? Insurance carriers pay commissions on annuity sales. Any agent, including us, should say so plainly and explain how the product fits your goals.
A useful rule: if the person selling the product cannot explain the exit cost in one minute, do not buy it that day.
What about the 401(k) alternative: staying put or moving to an IRA?
An annuity is only one of several choices. You can also leave the money in your old employer’s plan if it allows, move it to a new employer’s plan, roll it to a regular IRA, or take cash (usually the costliest route because of income tax and possible penalty). A plain IRA often offers more investment choices and, in some cases, lower fees than a workplace plan, which is why many people choose it.
The question to ask is not “annuity or 401(k)?” but “which part of my money needs a guarantee, and which part needs growth and access?” Money you won’t touch for 10 years and money you need next year deserve different homes.
Your Medicare premiums are part of this decision
This is the angle most rollover guides skip, and it matters if you are 63 or older. Medicare Part B premiums can be higher when the modified adjusted gross income on your tax return from two years earlier is above a set amount. The surcharge is known as IRMAA.
What that means in practice:
- A large taxable withdrawal, such as cashing out a 401(k) in one year, can lift your income for that year and raise your premiums two years later.
- A direct rollover that is not taxable generally does not add to your taxable income. A rollover paid out to you and not completed in time does.
- Spreading income across years, for instance with income that arrives in smaller steady payments, can help you stay under a threshold.
We have written in more depth on what Medicare IRMAA is and how surcharges work, whether annuity earnings are subject to IRMAA, and how a 3/5/7 annuity ladder can be used to smooth income. If you want to see how a ladder works as a retirement income plan, our guide to an annuity ladder for retirement income walks through it.
Annuity income can also help with medical spending. See using annuities to cover healthcare costs for how that fits alongside Medicare.
Our perspective: education first, then the product
We are independent agents who specialize in Medicare, and Paul Barrett has helped Medicare consumers since 2007. That history shapes how we talk about annuities. Most of the people who call us are turning 65, retiring from employer coverage, or unhappy with the coverage they have. They are rarely asking “which annuity?” They are asking “will my money last, and what will my health coverage cost?”
So we start with the plan, not the contract. We look at guaranteed income, expected healthcare costs, how much cash you want within reach, and what your taxable income will look like in the years that set your Medicare premiums. Sometimes the answer is a partial annuity rollover. Sometimes it is to leave the 401(k) alone and focus on the right Medicare Supplement or Medicare Advantage plan. We would rather tell you that than sell you something that does not fit.
Our independent status means we can compare options from more than 40 carriers instead of pushing a single company’s product, and we do it without pressure. Ask us for the costs and the exit terms first. If those do not work for you, the product does not either.
— Paul
Get a second set of eyes before you roll over
If you are weighing a rollover, we can review the contract terms, compare annuity options and show how the income would fit with your Medicare coverage. Learn more about our annuity options, or if the bigger question is your health coverage, see how we compare Medicare Advantage plans and Medicare Supplement plans.
There is no cost to ask questions, and we review your coverage year-round, not only at enrollment time.
Frequently asked questions
Is it a good idea to roll a 401(k) into an annuity?
It can be, if you want guaranteed lifetime income and are comfortable with less access to the money. It is usually a weaker fit if you need liquidity, are young, or want control over your investments. Many people roll over only the portion needed to cover core expenses.
Can I roll an IRA into an annuity the same way?
Yes, in general. IRA money can be moved into an annuity held inside an IRA, usually by a direct transfer between custodians so you never touch the funds. As with a 401(k), the annuity adds no extra tax deferral, so the decision rests on the guarantees and the costs.
What is better than an annuity for retirement?
Nothing is better for everyone. Index and bond funds, a cash reserve, Social Security timing and a pension can each play a role, and they come with different risks. An annuity is best viewed as one tool for covering essential expenses, not a replacement for the whole plan.
Will rolling over a 401(k) raise my Medicare premiums?
A direct, non-taxable rollover generally does not add taxable income. Taxable withdrawals or a failed rollover can, and Part B premiums may rise based on your income from two years earlier. Talk to a tax professional and a Medicare agent before moving a large balance close to or after age 63.
How long do I have to complete a rollover if the plan pays me?
Generally 60 days from the day you receive the money. A direct rollover avoids this deadline entirely, which is why it is the safer way to move retirement savings.
Sources
- Selecting Retirement Payout Methods, FINRA
- Annuities, FINRA
- Annuities, Investor.gov
- Should you roll over your 401(k) to an annuity, CBS News
- Annuities, 401(k)s, and IRAs: Key Differences, Investopedia
- Instructions for Forms 1099-R and 5498, IRS
- SEC filing on variable annuity contract adjustments
- SEC press release on variable annuity bonus credits
- Enrolling in Medicare Part A & Part B, Medicare.gov