Feeling Confident in Your 2026 Medicare Decision

Feeling Confident in Your 2026 Medicare Decision

What if the right Medicare choice isn’t the plan with the most features, but the one that fits your needs? In 2026, comparing options can feel overwhelming when you’re weighing your doctors, prescriptions, and the care you may need. It’s understandable to worry that one missed detail could matter later. Feeling confident in your Medicare decision starts with checking what matters to you, not searching for a plan that’s best for everyone.

This guide offers a practical way to compare your options. You’ll learn what to review, including whether your doctors and prescriptions are covered and how to check important plan details. You’ll also find ways to organize your questions so you can make an informed choice without feeling rushed.

An independent Medicare broker can help explain available options and compare plans against your priorities, while leaving the decision in your hands. You don’t have to enroll right away to make progress. Start by gathering the details that matter to you, then take one manageable next step.

Key Takeaways

  • Start with your priorities to identify which plan trade-offs matter most to you in 2026.
  • Use the same comparison process for Medicare Advantage, Medigap, and Part D options.
  • Check your doctors, prescriptions, costs, and coverage details against current official plan materials.
  • Feeling confident in your Medicare decision means knowing what you’ve checked and which questions still need answers.
  • If something remains unclear, pause and seek help comparing options before making your choice.

Feeling Confident in Your Medicare Decision Starts With Your Priorities

Medicare choices can feel confusing when several plan details seem equally important. That doesn’t mean you’re missing something or making a poor decision. It means you’re weighing options that may handle costs, providers, prescriptions, and care differently. In 2026, start by defining what matters most to you before comparing plans.

A confident Medicare decision is a personal, informed choice based on needs and priorities you’ve taken time to check.

What does feeling confident in your Medicare decision mean?

Feeling confident in your Medicare decision doesn’t mean finding a plan that promises to suit every possible future need. No one can know exactly what care they may need later. Confidence comes from understanding the trade-offs, checking the details that matter to you, and knowing why an option fits your current priorities.

It’s reasonable to ask questions, take time to compare, or find that you need to verify something before moving forward. Those are thoughtful steps, not signs that you’re falling behind. For a broad introduction to the parts and history of the Medicare program, you can review this overview, then focus your plan research on your circumstances.

Which personal details should guide your decision?

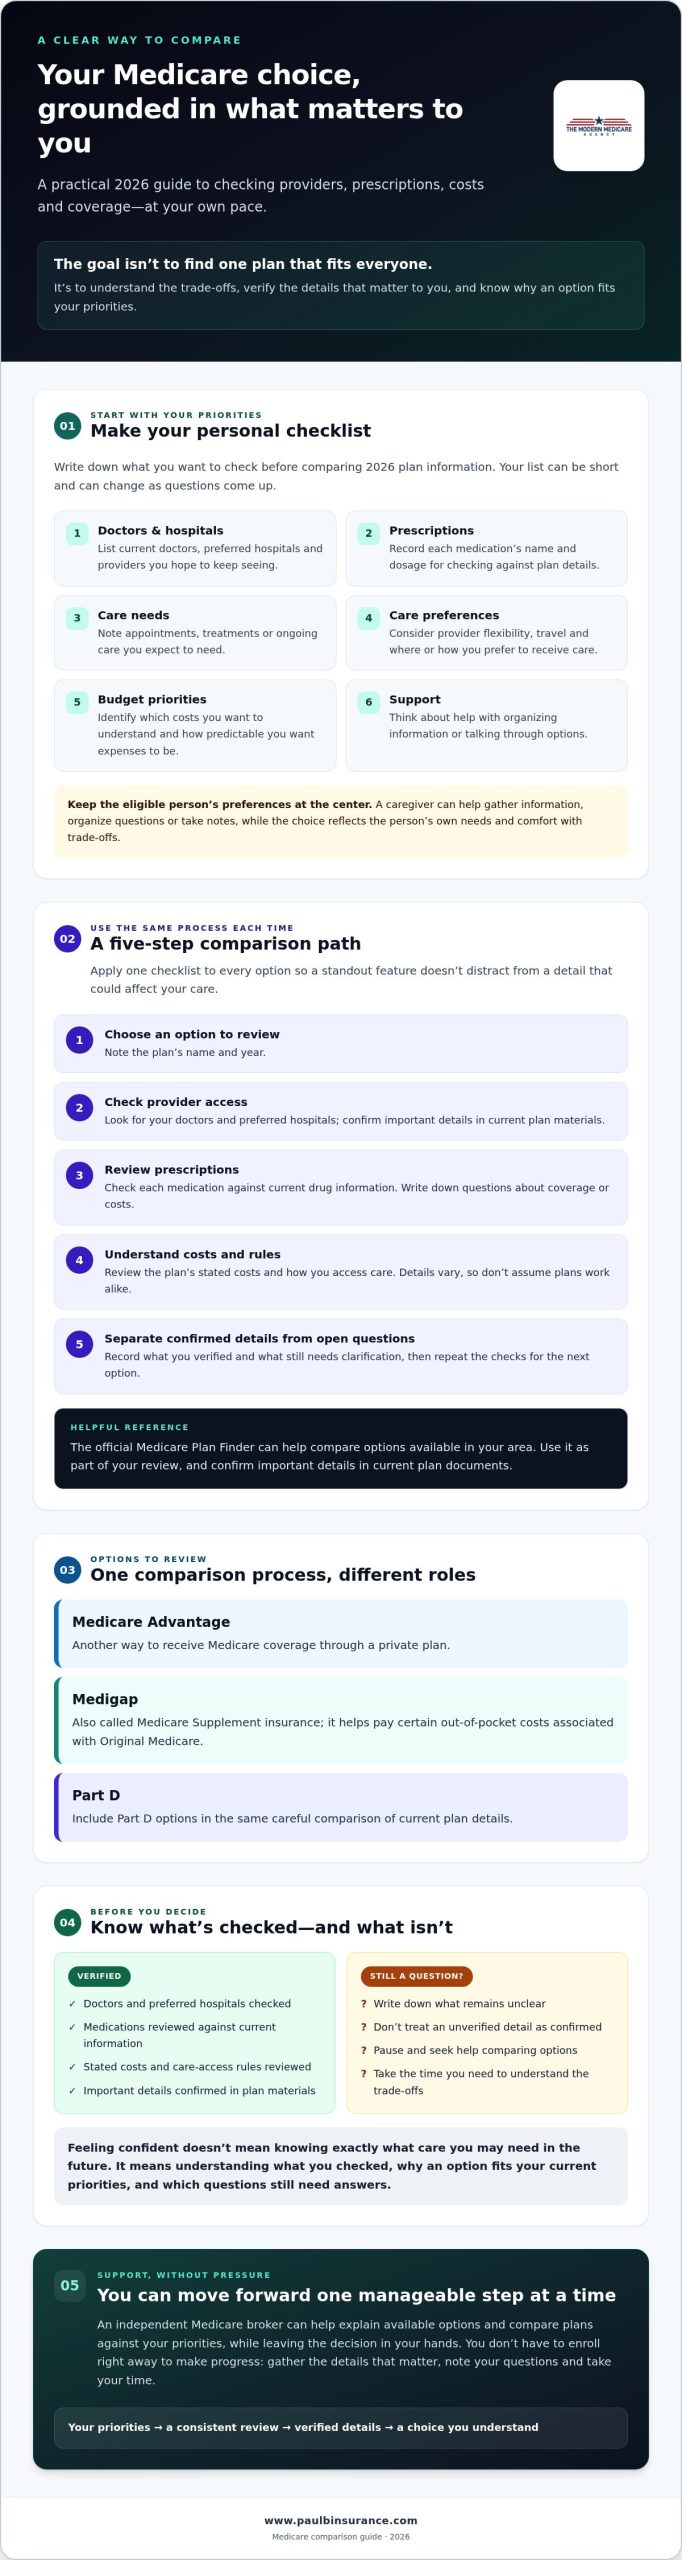
Start with a short list. It doesn’t need to be perfect. The goal is to make your priorities visible so you can refer to them while reviewing 2026 plan information.

  • Doctors and hospitals: List your current doctors, preferred hospitals, and providers you’d like to keep seeing.
  • Prescriptions: Record each medication, including its name and dosage, so you can check it against plan details.
  • Care needs: Note appointments, treatments, or ongoing care you expect to need, while remembering that future needs can change.
  • Care preferences: Consider whether you value flexibility in choosing providers, expect to travel, or have preferences about where and how you receive care.
  • Budget priorities: Identify which costs you want to understand clearly and how predictable you’d like your health expenses to be.
  • Support: Consider whether you want help organizing information or discussing options with someone you trust.

A caregiver can help gather documents, organize questions, or take notes during a conversation. Keep the eligible person’s preferences at the center, though. The decision should reflect their doctors, routines, concerns, and comfort with the trade-offs. With your list in hand, you can compare options against your own priorities instead of relying on general impressions.

A Step-by-Step Way to Compare Medicare Options in 2026

Once you know what matters to you, use the same process for every option you consider. This helps prevent one appealing feature from overshadowing a detail that may affect your care. In 2026, check current plan materials and use official Medicare resources to verify details. If something isn’t clear, record it as a question rather than treating it as confirmed.

Using one checklist for every option makes differences easier to see and keeps your choice grounded in your priorities.

How do you compare plans without getting lost in the details?

  1. Choose an option to review. Compare plans available to you, and note each plan’s name and year.
  2. Check provider access. Look for your doctors and preferred hospitals, then confirm important details using current plan materials.
  3. Review prescriptions. Check each medication against the plan’s current drug information. Record unanswered questions about coverage or costs.
  4. Understand costs and rules. Review the plan’s stated costs and how you access care. Details vary, so don’t assume one plan works like another.
  5. Mark what’s confirmed. Separate verified answers from items you still need to clarify, then repeat the checks for the next option.

The official Medicare Plan Finder tool can help you compare options available in your area. Use it as one part of your review, and confirm important details in current plan documents before deciding.

Which Medicare option deserves a closer look?

These options serve different roles. Medicare Advantage is another way to receive Medicare coverage through a private plan. A Medicare Advantage guide can explain how this type of plan works. Medigap, also called Medicare Supplement insurance, helps pay certain out-of-pocket costs associated with Original Medicare. Learn more in this Medigap overview. Part D is prescription drug coverage, so review its medication details when comparing drug coverage.

These categories aren’t interchangeable, and the right comparison depends on your situation. Keep your notes beside the official materials as you review your 2026 options. If a provider, prescription, cost, or rule remains unclear, pause and get an answer before treating it as settled. A steady process can make feeling confident in your Medicare decision more achievable, without requiring you to predict every future care need.

Check Doctors, Prescriptions, Costs, and Coverage Before You Decide

A plan feature may sound helpful on paper, but the key question is whether it fits your life. A wide choice of providers won’t help as much if your preferred doctor isn’t included. Drug coverage matters when it works for the medications you take. In 2026, plan availability and details can differ, so check each option using current materials rather than relying on general descriptions.

Verify your doctors and prescriptions against current plan information before you decide.

Are your doctors, hospitals, and prescriptions covered?

Search the plan’s current provider directory for your doctors and preferred hospitals. Directories can change, so contact the provider and the plan to confirm important details, including whether a provider participates in the plan you’re considering. Check every medication against the plan’s current drug information, including any plan-specific limits or requirements listed there. For help understanding prescription coverage, read this Medicare Part D guide.

How can you compare costs and coverage fairly?

Use the categories and terms in each plan’s official 2026 materials. Consider how often you expect to use care, which services you may need, and whether the plan’s stated rules fit your preferences. Don’t assume a feature means the plan will meet your particular needs. If something is unclear, ask the plan to explain it and record the answer before comparing further.

What to check Questions to ask Where to verify
Doctors and hospitals Are my providers included, and can I continue seeing them under this plan? Current provider directory, provider office, and plan materials
Prescriptions Are all my medications listed, and what coverage rules apply? Current drug list and plan documents
Costs Which cost categories apply, and how might my expected care use affect what I pay? Current official plan materials
Coverage and rules Are there exclusions, referrals, prior approvals, or service-area limits I should understand? Plan documents and direct confirmation from the plan

Keep a note of anything you can’t confirm, such as whether a particular service is covered or how a plan’s rules apply to you. Ask the plan directly before treating an assumption as fact. This helps you compare a plan’s features with what you actually need, without expecting every option to suit every person.
Feeling Confident in Your 2026 Medicare Decision

Use This Final Medicare Decision Checklist to Resolve Doubts

Before choosing a Medicare option in 2026, review what you’ve confirmed and what still needs an answer. A short written checklist can help you spot loose ends and discuss specific questions with a plan or qualified adviser. It supports your decision, but it doesn’t replace current plan documents or official guidance.

What questions should you answer before choosing?

Use this checklist for the plan you’re considering. Beside each answer, note where you found the information and when you checked it. Plan details can change, so keeping the source with your notes makes it easier to confirm that you’re using current information.

  • Doctors and facilities: Have I checked whether the doctors and hospitals that matter to me are included? Did I confirm important details with the provider and the plan?
  • Prescriptions: Have I checked each medication against the plan’s current drug information?
  • Costs and coverage: Do I understand the relevant costs, covered services, and plan rules from current materials?
  • Questions: Have I written down anything I couldn’t confirm, along with who can verify it?

A simple note can be enough: “Question: Is my specialist included? Source checked: provider directory. Follow up with: plan.” This separates what you know from what you still need to confirm, without relying on memory.

What if you still feel unsure?

Try to identify why. Is information missing, have you received conflicting answers, or are you weighing two priorities that point to different options? Each situation calls for a different next step. For missing details, contact the plan. If answers conflict, ask for clarification and record who provided it. If priorities compete, revisit which needs matter most to you.

Pause if an important question is unresolved. There’s no need to treat uncertainty as a reason to choose immediately. Gather the relevant plan materials, write down the exact question, and ask the plan or a qualified adviser to clarify it. Advice can help you understand your options, but no checklist or adviser can guarantee a particular outcome.

Feeling confident in your Medicare decision doesn’t require knowing exactly what your future health needs will be. It means you’ve checked the details that matter, recorded what remains uncertain, and made a thoughtful choice. If you’d like help organizing your questions and comparing Medicare options, you can talk through your Medicare options with an independent broker.

Get Personal Help and Move Forward at Your Own Pace

You don’t have to sort through every Medicare detail alone. An independent broker can help organize your questions, compare available options against your stated needs, and explain how plan details differ. The guidance should make your choices clearer, not make the choice for you. You remain in control of whether and when to move forward.

What can an independent Medicare broker help you understand?

A broker can explain Medicare Advantage, Medigap, and Part D options and help identify details to verify, such as provider access, prescription coverage, costs, and plan rules. Bring your priorities and questions to the conversation. Ask how an option matches your needs, what trade-offs to consider, and which details to check in current plan materials.

The Modern Medicare Agency helps eligible individuals compare Medicare Advantage, Medigap, and Part D plans from more than 40 carriers. It provides personalized guidance. Carrier participation and available plans can vary, so confirm current 2026 options and details directly before relying on a comparison.

How can you take a clear next step?

Before speaking with an adviser, gather your current plan information, your list of doctors and prescriptions, and any unanswered questions. It may help to sort questions into groups, such as providers, medications, costs, and coverage rules. Then you can use the conversation to work through what’s still uncertain rather than starting from scratch.

The Modern Medicare Agency provides year-round support across more than 34 states. Confirm that support and service availability apply to your circumstances, and remember that ongoing support doesn’t mean plan details remain unchanged. For a 2026 decision, verify important information against current plan materials.

Feeling confident in your Medicare decision doesn’t require having every answer before you ask for help. It can begin with a clear conversation, a few specific questions, and enough time to consider what you learn. An independent broker can explain options and help you compare, but the decision remains yours.

If you’d like to explore a personal comparison, bring your questions and take the conversation one step at a time. There’s no need to decide before you feel ready.

Take Your Next Medicare Step With Confidence

In 2026, a sound Medicare choice starts with your priorities, not a search for one plan that suits everyone. Compare options using the same questions, and check current plan information for your doctors, prescriptions, costs, and coverage rules. If something is unclear, write it down and get an answer before you decide.

That’s what feeling confident in your Medicare decision can look like: understanding what you’ve checked, knowing how an option fits your needs, and being comfortable with the trade-offs. You don’t have to predict every future health need or rush into a choice.

The Modern Medicare Agency is an independent brokerage that helps people compare Medicare Advantage, Medigap, and Part D options from more than 40 carriers, with personalized guidance and year-round support. Confirm current details and available options for your situation, then use any conversation to ask questions and clarify choices. The decision remains yours.

If you’d like help organizing your comparison, talk through your Medicare options at your own pace. Contact The Modern Medicare Agency to discuss your questions and compare available plans. You can move forward when you feel ready.

Frequently Asked Questions

How can I feel confident in my Medicare decision?

Start with the details that matter most to you, such as your doctors, prescriptions, preferred care arrangements, and budget priorities. Compare each option using the same checklist, and verify answers in current 2026 plan materials. Write down anything you still need to confirm. Feeling confident in your Medicare decision doesn’t mean finding a plan that’s right for everyone. It means understanding the choice and its trade-offs for your needs.

What should I compare before choosing a Medicare plan?

Compare how each plan fits your care needs and preferences. Check whether important doctors and facilities are included, how your prescriptions are handled, what costs apply, and which plan rules may affect access to care. Use current official materials for specifics, since details can differ between plans. If something isn’t clear, write down the question and confirm it with the plan or a qualified adviser before relying on an assumption.

Is Medicare Advantage or Medigap better for me?

Neither option is automatically better for everyone. Medicare Advantage and Medigap are different types of coverage, each with features and trade-offs to consider. Your doctors, care preferences, prescription needs, and budget priorities can guide your comparison. Review current plan information and make sure you understand how each option works. An adviser can explain the choices and help you compare them, but the decision should remain yours.

Can I change my Medicare decision if my needs change?

You may have options to make a change, but what’s available depends on your circumstances and the rules in effect at the time. Don’t assume you can change every plan whenever you want. Check current official Medicare information and the plan’s materials for applicable choices and timing. If your health needs, providers, or prescriptions change, confirm how those changes may affect your coverage before taking action.

How do I know whether my prescriptions are covered?

Check each medication against the current drug information for the plan you’re considering. Review details that may affect coverage, access, or what you pay, and confirm anything you don’t understand with the plan. Prescription information can vary by plan and may change, so don’t rely on an old list or a general description. A qualified adviser can also help you identify which details to verify.

Should I ask a Medicare broker for help choosing a plan?

A Medicare broker can help you understand and compare available options, explain unfamiliar terms, and organize questions around your needs. Ask which types of plans they can discuss and how they compare options from different carriers. The Modern Medicare Agency helps eligible individuals compare Medicare Advantage, Medigap, and Part D plans. You remain the decision-maker, and important details should be verified using current plan documents.

What if I still feel unsure after comparing Medicare plans?

Pause and identify what’s behind the uncertainty. You may be missing a fact, getting conflicting answers, or weighing personal priorities that point in different directions. Write down the specific questions you need answered and who may be able to verify them. Contact the plan or a qualified adviser for clarification. Taking time to resolve an important concern can be more helpful than choosing based on pressure or guesswork.
Paul Barrett

Article by

Paul Barrett

Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.

He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.

📞 631-358-5793 | paulbinsurance.com
What Is Medicare Part B and What Does It Actually Cover?

The complete guide to Medicare’s medical insurance — every service it covers, exactly what it costs in 2026, how it works with group insurance and VA benefits, and the excess charges most people have never heard of until they get a surprise bill.

The Short Answer

Medicare Part B is medical insurance — it covers doctor visits, outpatient care, preventive services, durable medical equipment, and more. Unlike Part A, Part B is not premium-free for anyone: everyone pays a monthly premium (202.90in2026formostpeople),anannualdeductible(283), and 20% coinsurance on most covered services, with no yearly cap on that 20% under Original Medicare alone. Whether you need to enroll at 65, and whether delaying is safe, depends heavily on your employment status and your employer’s size — getting this wrong is one of the most consequential and permanent mistakes in all of Medicare.

Key Takeaways

  • Part B is never premium-free — everyone pays a monthly premium, and higher earners pay significantly more through IRMAA.
  • The 20% coinsurance under Original Medicare alone has no yearly cap — this is the single biggest financial risk in Medicare, and it’s the reason Medigap and Medicare Advantage exist.
  • Whether you can safely delay Part B without a penalty depends on your employer’s size: 20+ employees generally allows delay; fewer than 20 generally does not.
  • Missing your enrollment window triggers a permanent 10% penalty for every 12-month period you went without coverage.
  • Veterans can and generally should enroll in Part B even with VA benefits, since Medicare and VA coverage don’t coordinate — each only pays for care received within its own system.
  • “Excess charges” from non-participating providers can add up to 15% on top of what Medicare approves, and only some Medigap plans protect you from them.

What Part B Actually Covers

While Part A handles hospital room and board, Part B is the half of Original Medicare that covers medical care and most services delivered outside a hospital admission — doctor visits, outpatient procedures, and ongoing medical needs.

What’s covered

  • Doctor visits — primary care and specialists
  • Outpatient surgeries and procedures
  • Diagnostic lab work, X-rays, and MRIs
  • Emergency room visits
  • Ambulance services
  • Outpatient mental health care
  • Physical, occupational, and speech therapy
  • Chemotherapy and radiation received in an outpatient clinic
  • Durable Medical Equipment (DME) — wheelchairs, oxygen equipment, blood sugar monitors, walkers, and similar equipment
  • Ambulatory surgical center services

Preventive services: the part Medicare gets genuinely right

Most preventive services are covered at 100%, with no deductible and no copay, as long as your provider accepts Medicare assignment. This includes:

  • Your one-time “Welcome to Medicare” wellness visit, available within your first 12 months on Part B
  • Annual wellness visits after that
  • Flu shots and most other recommended vaccines
  • Mammograms
  • Colonoscopies and other cancer screenings
  • Diabetes and cardiovascular screenings
  • Many other screenings recommended by the U.S. Preventive Services Task Force

Paul’s Honest Take: This is one of the most underused parts of Medicare, full stop. I’ve had clients who paid for a private physical every year out of habit and never realized their annual wellness visit through Medicare was completely free. If you haven’t used your Welcome to Medicare visit or your annual wellness visit, that’s real value sitting on the table.

What’s NOT covered

  • Routine dental care — cleanings, fillings, dentures, extractions
  • Routine vision exams and eyeglasses
  • Hearing aids (though diagnostic hearing tests ordered by a doctor may be covered)
  • Long-term custodial nursing home care — help with daily living activities, as opposed to short-term skilled or medical care
  • Routine prescription drugs you pick up at a retail pharmacy — that’s Part D’s job, not Part B’s
  • Cosmetic surgery, unless medically necessary (such as reconstruction after an accident or mastectomy)
  • Most care received outside the United States, with very limited exceptions
  • Routine foot care, such as nail trimming, in the absence of a qualifying medical condition
  • Acupuncture, except for a narrow, specific chronic low back pain benefit
  • Concierge medicine fees and membership-style charges some practices add on top of standard care
  • Long-term care insurance-style services, including most home-based personal care that isn’t tied to a skilled medical need

Paul’s Honest Take: The dental and vision exclusions are the ones that surprise people most, especially since they’re such routine parts of healthcare for most adults. This is exactly why so many Medicare Advantage plans build dental, vision, and hearing benefits into their coverage — Original Medicare was simply never designed to include them, and that gap doesn’t go away on its own.

What Part B Costs in 2026

Part B has three separate cost components, and understanding all three matters:

Cost Component

2026 Amount

Standard monthly premium

$202.90

Annual deductible

$283

Coinsurance on most covered services

20%

The premium is deducted automatically from your Social Security check if you’re already collecting benefits. If you’re not yet collecting Social Security, you’ll receive a bill, typically every three months.

The deductible works differently than Part A’s — it’s a straightforward annual figure. You pay the first $283 of Medicare-approved outpatient costs each calendar year, and then Medicare’s cost-sharing kicks in.

The coinsurance is where the real risk lives. After your deductible is met, Medicare pays 80% of the Medicare-approved amount for most covered services, and you’re responsible for the remaining 20%. There is no yearly cap on this 20% under Original Medicare alone. If you have a $100,000 course of cancer treatment, your 20% share is $20,000 — unless you have a Medigap policy or Medicare Advantage plan absorbing that cost.

Paul’s Honest Take: I put this in bold because it’s genuinely the single most important number in this entire guide. That uncapped 20% is the whole reason Medigap and Medicare Advantage exist as products in the first place. Original Medicare by itself was never designed to protect you from a truly expensive year — it was designed to cover 80% of it and leave the rest to you.

IRMAA: What Higher Earners Actually Pay

If your income is above certain thresholds, you’ll pay more for Part B through the Income-Related Monthly Adjustment Amount (IRMAA) — based on your tax return from two years prior. For 2026, that means your 2024 income determines your premium tier.

2024 Income (Individual)

2024 Income (Married, Joint)

Total Part B / Month

$109,000 or less

$218,000 or less

$202.90

$109,001 – $137,000

$218,001 – $274,000

$284.10

$137,001 – $171,000

$274,001 – $342,000

$405.80

$171,001 – $205,000

$342,001 – $410,000

$527.50

$205,001 – $499,999

$410,001 – $749,999

$649.20

$500,000 and above

$750,000 and above

$689.90

At the top tier, you’re paying more than three times the standard premium. If your income has recently dropped — retirement, the loss of a spouse, or certain other life-changing events — you can appeal your IRMAA determination using Form SSA-44.

Do You Have to Enroll? And What Happens If You Don’t?

Technically, Part B is optional — Medicare won’t force you into it. But opting out without a valid alternative is genuinely risky, because of how the penalty structure works.

If you don’t sign up during your Initial Enrollment Period (the 7-month window around your 65th birthday) and you don’t have qualifying employer coverage, you’ll face a permanent 10% penalty added to your premium for every full 12-month period you went without Part B. That penalty doesn’t expire — you pay it for as long as you have Part B, which for most people means for the rest of your life.

Example: If you delayed enrollment by 24 full months without a valid exception, you’d pay an extra 20% on top of the standard $202.90 premium in 2026 — roughly $40.58 more, every month, permanently.

How Part B Works with Group Insurance

Just like Part A, whether you can safely delay Part B without penalty comes down to one specific number: how many employees your company has.

Companies with 20 or more employees: If you or your spouse are actively working and covered by a genuine group health plan, your workplace insurance is primary, and you can legally delay Part B without any penalty. When that employment or coverage eventually ends, you get an 8-month Special Enrollment Period to enroll in Part B penalty-free.

Companies with fewer than 20 employees: Medicare automatically becomes your primary insurer at 65, regardless of your employment status. You need to enroll in Part B right on schedule. If you don’t, your small employer’s plan can legally refuse to pay claims that Medicare should have covered first — potentially leaving you responsible for the full cost.

Paul’s Honest Take: I say this in nearly every guide I write, because it’s genuinely one of the costliest misunderstandings I encounter: “I have good coverage at work” and “I’m protected from Medicare’s enrollment deadlines” are two completely different statements, and whether the second one is true depends entirely on your employer’s size — not how generous the coverage feels. Confirm the actual employee count before you decide to delay anything.

Retiree Coverage Is Not the Same as Active Employer Coverage

This is a distinction that catches a genuinely large number of people off guard: the “20 or more employees” exception only applies to active employment. If you retire and your former employer offers you retiree health benefits — sometimes a genuinely good, comprehensive plan — that coverage does not create a Special Enrollment Period the way active group coverage does, and it does not exempt you from enrolling in Part B on time.

Paul’s Honest Take: I’ve seen this mistake more than once, and it’s an especially painful one because it happens to people who did everything right during their working years. Someone retires with a strong retiree health plan from a large employer, assumes it works the same way their active coverage did, and delays Part B — only to find out later that retiree coverage was never a valid reason to delay in the first place. The moment you stop actively working, that clock starts, regardless of how good your retiree plan looks on paper. If you’re retiring and keeping employer retiree benefits, treat enrolling in Part B as something to handle right on schedule, not something retiree coverage lets you postpone.

Why You Need Both Part A and Part B for Medigap or Medicare Advantage

Here’s a foundational requirement worth understanding clearly, since it shapes every other coverage decision in Medicare: you must be enrolled in both Part A and Part B before you can buy a Medigap policy or enroll in a Medicare Advantage plan. Neither product exists as a standalone substitute for Original Medicare — both are built specifically to work alongside it.

  • Medigap fills the cost-sharing gaps left by Original Medicare (Parts A and B) — it has nothing to fill in if you’re not enrolled in both parts to begin with.
  • Medicare Advantage legally must provide at least the same coverage as Parts A and B combined, which is only possible because you’re required to be enrolled in both before a Medicare Advantage carrier can enroll you.

Paul’s Honest Take: This surprises people who assume they can somehow “skip” Part B and go straight into a Medicare Advantage plan to avoid the extra premium. It doesn’t work that way — Part B enrollment, and its premium, is a prerequisite either way, whether you end up on Original Medicare with Medigap or on a Medicare Advantage plan. There’s no path through Medicare that avoids the Part B premium once you’re actually using the system.

Does Medicare Work If You’re a Veteran?

Yes — and if you have VA health benefits, understanding how the two systems relate is genuinely important, because they work differently than most people assume.

Medicare and VA benefits do not coordinate. These are two entirely separate systems that each pay only for care received within their own network. Medicare doesn’t pay for care you receive at a VA facility, and VA benefits don’t pay for care you receive from a non-VA doctor or hospital. You, the veteran, choose which system to use each time you seek care.

Here’s the critical point: having VA benefits does not exempt you from Medicare’s enrollment deadlines. VA coverage is not considered a qualifying reason to delay Part B without penalty. If you don’t enroll in Part B during your Initial Enrollment Period and you’re relying solely on VA benefits, you can still trigger the permanent late enrollment penalty.

Why the VA itself recommends enrolling in Medicare anyway:

  • It gives you access to civilian doctors and hospitals outside the VA system
  • VA healthcare funding depends on annual Congressional appropriations, which isn’t guaranteed to remain stable
  • If VA authorizes only part of your needed care at a non-VA facility, Medicare can help cover the rest
  • Having both gives you meaningfully more flexibility and security than relying on either system alone

Paul’s Honest Take: This is one of the most common misconceptions I run into with veterans specifically, and it’s an expensive one to get wrong. Good VA coverage feels like it should be enough, and it might genuinely handle most of your care — but it doesn’t protect you from the Part B enrollment clock the way employer coverage from a large company can. The VA itself actively encourages enrolling in Medicare Parts A and B for exactly this reason. If you have VA benefits and are approaching 65, this is worth a direct conversation before you assume you’re covered.

Veterans who enroll in Part B can also purchase a Medigap policy, which can be particularly valuable if you use non-VA providers regularly — though if you primarily rely on VA facilities for most of your care, the value of an added Medigap policy may be more limited, and worth weighing carefully.

How Long Does It Actually Take to Get Part B Approved?

This is one of the most practical, and most overlooked, pieces of planning — especially if you’re leaving a job after 65 and coordinating your Part B start date around the end of your employer coverage. Applying isn’t instant, and the timeline depends heavily on which enrollment window you’re using.

Enrollment Situation

Typical Processing Time

When Coverage Actually Starts

Initial Enrollment Period (around 65)

2–4 weeks, sometimes up to 6

1st of your birthday month (if applied in the 3 months before) or 1st of the month after you apply (if applied during or after your birthday month)

Special Enrollment Period (leaving employer coverage)

4–8 weeks, sometimes longer

1st of the month after your application is submitted

General Enrollment Period (Jan 1–Mar 31, missed window)

4–6 weeks

1st of the month after you apply

Why the Special Enrollment Period takes longer: applying after leaving employer coverage requires two forms, not one — Form CMS-40B (the actual Part B application) and Form CMS-L564 (Request for Employment Information), which your employer needs to complete to verify you had qualifying coverage. Social Security has to manually review both, which is exactly why this route consistently takes longer than a standard Initial Enrollment Period application.

Paul’s Honest Take: This timeline question comes up constantly with clients who are retiring or leaving a job after 65, and it deserves real attention — not just because of the penalty risk we’ve already covered, but because a slow approval can leave you with an actual gap in coverage if you time it too tightly. My standard advice: start this process at least 2 to 3 months before you need Part B to actually begin, not the week your employer coverage ends. If your former employer is slow to complete their portion of Form CMS-L564, that alone can hold up the entire application — so it’s worth following up with your HR or benefits department directly rather than assuming it’s been submitted.

Practical tips to avoid delays

  • Apply online through SSA.gov whenever possible. It’s consistently the fastest method — mailed or faxed forms are more prone to getting lost or delayed.
  • If you’re on a Special Enrollment Period, submit Form CMS-L564 alongside Form CMS-40B, not separately. They need to arrive together, and one incomplete form can stall the whole application.
  • Expect a short intake lag even with online applications. It can take several business days for an online submission to actually appear on a local Social Security agent’s screen — don’t panic if you call shortly after applying and they say they don’t see it yet.
  • Once approved, you don’t have to wait for your physical card. Your Medicare Beneficiary Identifier typically appears in your online Social Security or Medicare.gov account within a day or two of approval, and you can print a temporary card from there — the physical card generally arrives by mail within about 30 days.

Excess Charges: The Cost Almost Nobody Knows to Ask About

Here’s a detail that surprises even people who’ve been on Medicare for years: not every doctor who accepts Medicare agrees to accept Medicare’s approved amount as full payment.

Providers fall into three categories:

  • Participating providers accept Medicare assignment, meaning they agree to accept the Medicare-approved amount as payment in full. This covers the vast majority of providers — roughly 98% of doctors nationally.
  • Non-participating providers still accept Medicare patients but haven’t agreed to accept the standard rate. They can charge an excess charge of up to 15% above the Medicare-approved amount.
  • Opted-out providers have left the Medicare system entirely and can charge whatever they want under a private contract — Medicare pays nothing at all for care from these providers, except in emergencies.

How excess charges actually work: if the Medicare-approved amount for a service is $300 and you see a non-participating provider, they can legally charge up to an additional $45 (15%) on top, for a total bill of $345 — and that excess amount doesn’t count toward your Part B deductible.

Eight states currently prohibit or limit excess charges entirely: Connecticut, Massachusetts, Minnesota, New York, Ohio, Pennsylvania, Rhode Island, and Vermont. If you live in one of these states, you’re generally shielded from excess charges from providers within your state — though you could still face them if you receive care from a non-participating provider elsewhere.

Paul’s Honest Take: This is exactly why Medigap Plan G matters so much for people who want maximum flexibility. Plan G covers excess charges in full — Plan N does not. If you’re the kind of person who wants the freedom to see any doctor without worrying about billing surprises, that distinction is worth understanding clearly before you pick between the two. And regardless of which plan you choose, it’s always worth asking a new provider directly whether they accept Medicare assignment before your first appointment.

The HSA Rule: Part B Closes the Door Too

If you’re hoping to keep contributing to a Health Savings Account, know this clearly: enrolling in Part B — or any part of Medicare — ends your ability to make new HSA contributions. This isn’t unique to Part B; it applies the moment you enroll in Medicare in any form, including premium-free Part A.

If keeping your HSA active matters to you, the only way to legally delay both Part A and Part B is through qualifying employer coverage — which, as covered above, generally requires an employer with 20 or more employees. And because Part A enrollment can be backdated up to 6 months once you do enroll, it’s smart to stop HSA contributions 6 months before you plan to sign up for Medicare or file for Social Security, whichever comes first.

Frequently Asked Questions

Is there a cap on what I’ll pay for Part B services in a year? Not under Original Medicare alone — the 20% coinsurance has no yearly limit. A Medigap policy or Medicare Advantage plan is what actually caps your exposure.

What happens if I don’t sign up for Part B on time? You’ll generally face a permanent 10% penalty on your premium for every 12-month period you went without coverage, unless you qualify for a Special Enrollment Period through active employer coverage.

Do I need Part B if I have good coverage through a small employer? Almost certainly yes. If your employer has fewer than 20 employees, Medicare becomes your primary insurer at 65 regardless of your job coverage, and not enrolling can leave you exposed to unpaid claims and a lifelong penalty.

Do veterans need Medicare Part B if they have VA benefits? Generally, yes. Medicare and VA benefits don’t coordinate — each only pays for care within its own system — and VA coverage doesn’t exempt you from Medicare’s enrollment deadlines or penalties.

What is a Part B excess charge? An additional charge, up to 15% above the Medicare-approved amount, that a non-participating provider can legally bill you. It doesn’t count toward your deductible, and only Medigap Plan G (among current plans) covers it in full.

Can I keep contributing to my HSA if I enroll in Part B? No. Enrolling in any part of Medicare, including Part B, ends your HSA contribution eligibility going forward.

How long does it take to get approved for Part B? It depends on the enrollment window. Initial Enrollment Period applications typically process in 2–4 weeks. Special Enrollment Period applications, used when leaving employer coverage, generally take 4–8 weeks since Social Security must manually verify your prior coverage using Form CMS-L564. Start the process at least 2–3 months before you need coverage to begin, especially when coordinating around a job ending.

The Bottom Line

Part B is the half of Medicare that covers your everyday medical care — and it’s also where the real financial exposure of Original Medicare lives, thanks to that uncapped 20% coinsurance. Whether you should enroll at 65, whether you can safely delay, and how much of that exposure you’re carrying all depend on details specific to your situation: your employer’s size, your income, your VA status, and which doctors you actually see.

If you want help sorting out exactly how Part B applies to your specific circumstances — or want to understand how Medigap or Medicare Advantage could close that uncapped coinsurance gap — that’s exactly the conversation I have with clients every day, at no cost to you.

Call 631-358-5793 or visit paulbinsurance.com to set up a time to talk it through.

Paul Barrett, CMIP, is the founder of The Modern Medicare Agency, based in Melville, NY, and has spent 18+ years exclusively helping people navigate Medicare — never life insurance, never annuities, just Medicare. He’s licensed in 37 states, represents more than 40 carriers, and has personally helped over 5,000 clients choose coverage that actually fits their lives.

Figures current as of 2026 and sourced from CMS, Medicare.gov, and the Social Security Administration. Individual circumstances vary, especially around employer coverage, VA benefits, and income-based premiums — always verify your specific situation before making enrollment decisions.

Sources

Related Post

Scroll to Top

Request a Callback with
Paul Barrett

Fill out the form below, and we'll call you within 24 hours.