Last Sunday, you might have noticed your father staring at a pile of colorful insurance mailers with a look of pure exhaustion. It’s a heavy realization when you find yourself wondering how to explain medicare to my parents without making them feel like they’re losing their independence. You aren’t alone in feeling this weight. It’s completely normal to worry about them missing a critical enrollment window or choosing a plan that leaves them with massive medical bills later on.
The good news is that you don’t have to be a policy expert to be a great advocate. This 2026 guide is designed to help you simplify the different “Parts” of Medicare and move forward with total peace of mind. We’ll walk through the specific differences between Medicare Advantage and Supplement plans, show you how to avoid common 2026 pitfalls, and provide a clear path for a productive family talk. By the end, you’ll have a reliable plan to ensure your parents have the security and care they deserve.
Key Takeaways
- Learn how to explain medicare to my parents by focusing on their specific health needs so you don’t feel overwhelmed by the process.
- Get a clear breakdown of the 2026 Medicare landscape to help your family choose between the “all-in-one” simplicity of Advantage and the freedom of Supplement plans.
- Use our step-by-step framework to gather essential documents and review current prescriptions so you can avoid common enrollment mistakes.
- Discover how an independent broker provides unbiased comparisons from over 40 carriers to ensure your parents get the most reliable coverage.
- Shift the conversation from a state of stress to one of certainty by acting as a calm, patient guide for your family’s healthcare journey.
Why Talking to Your Parents About Medicare is So Stressful
Helping your parents with their health coverage is a significant milestone. It often marks the first time roles truly reverse; you become the protector while they might feel vulnerable. This shift is exactly why learning how to explain medicare to my parents can feel so daunting. You aren’t just discussing doctors and deductibles. You’re managing their deeply held desire for independence and their fear of becoming a burden on the family.
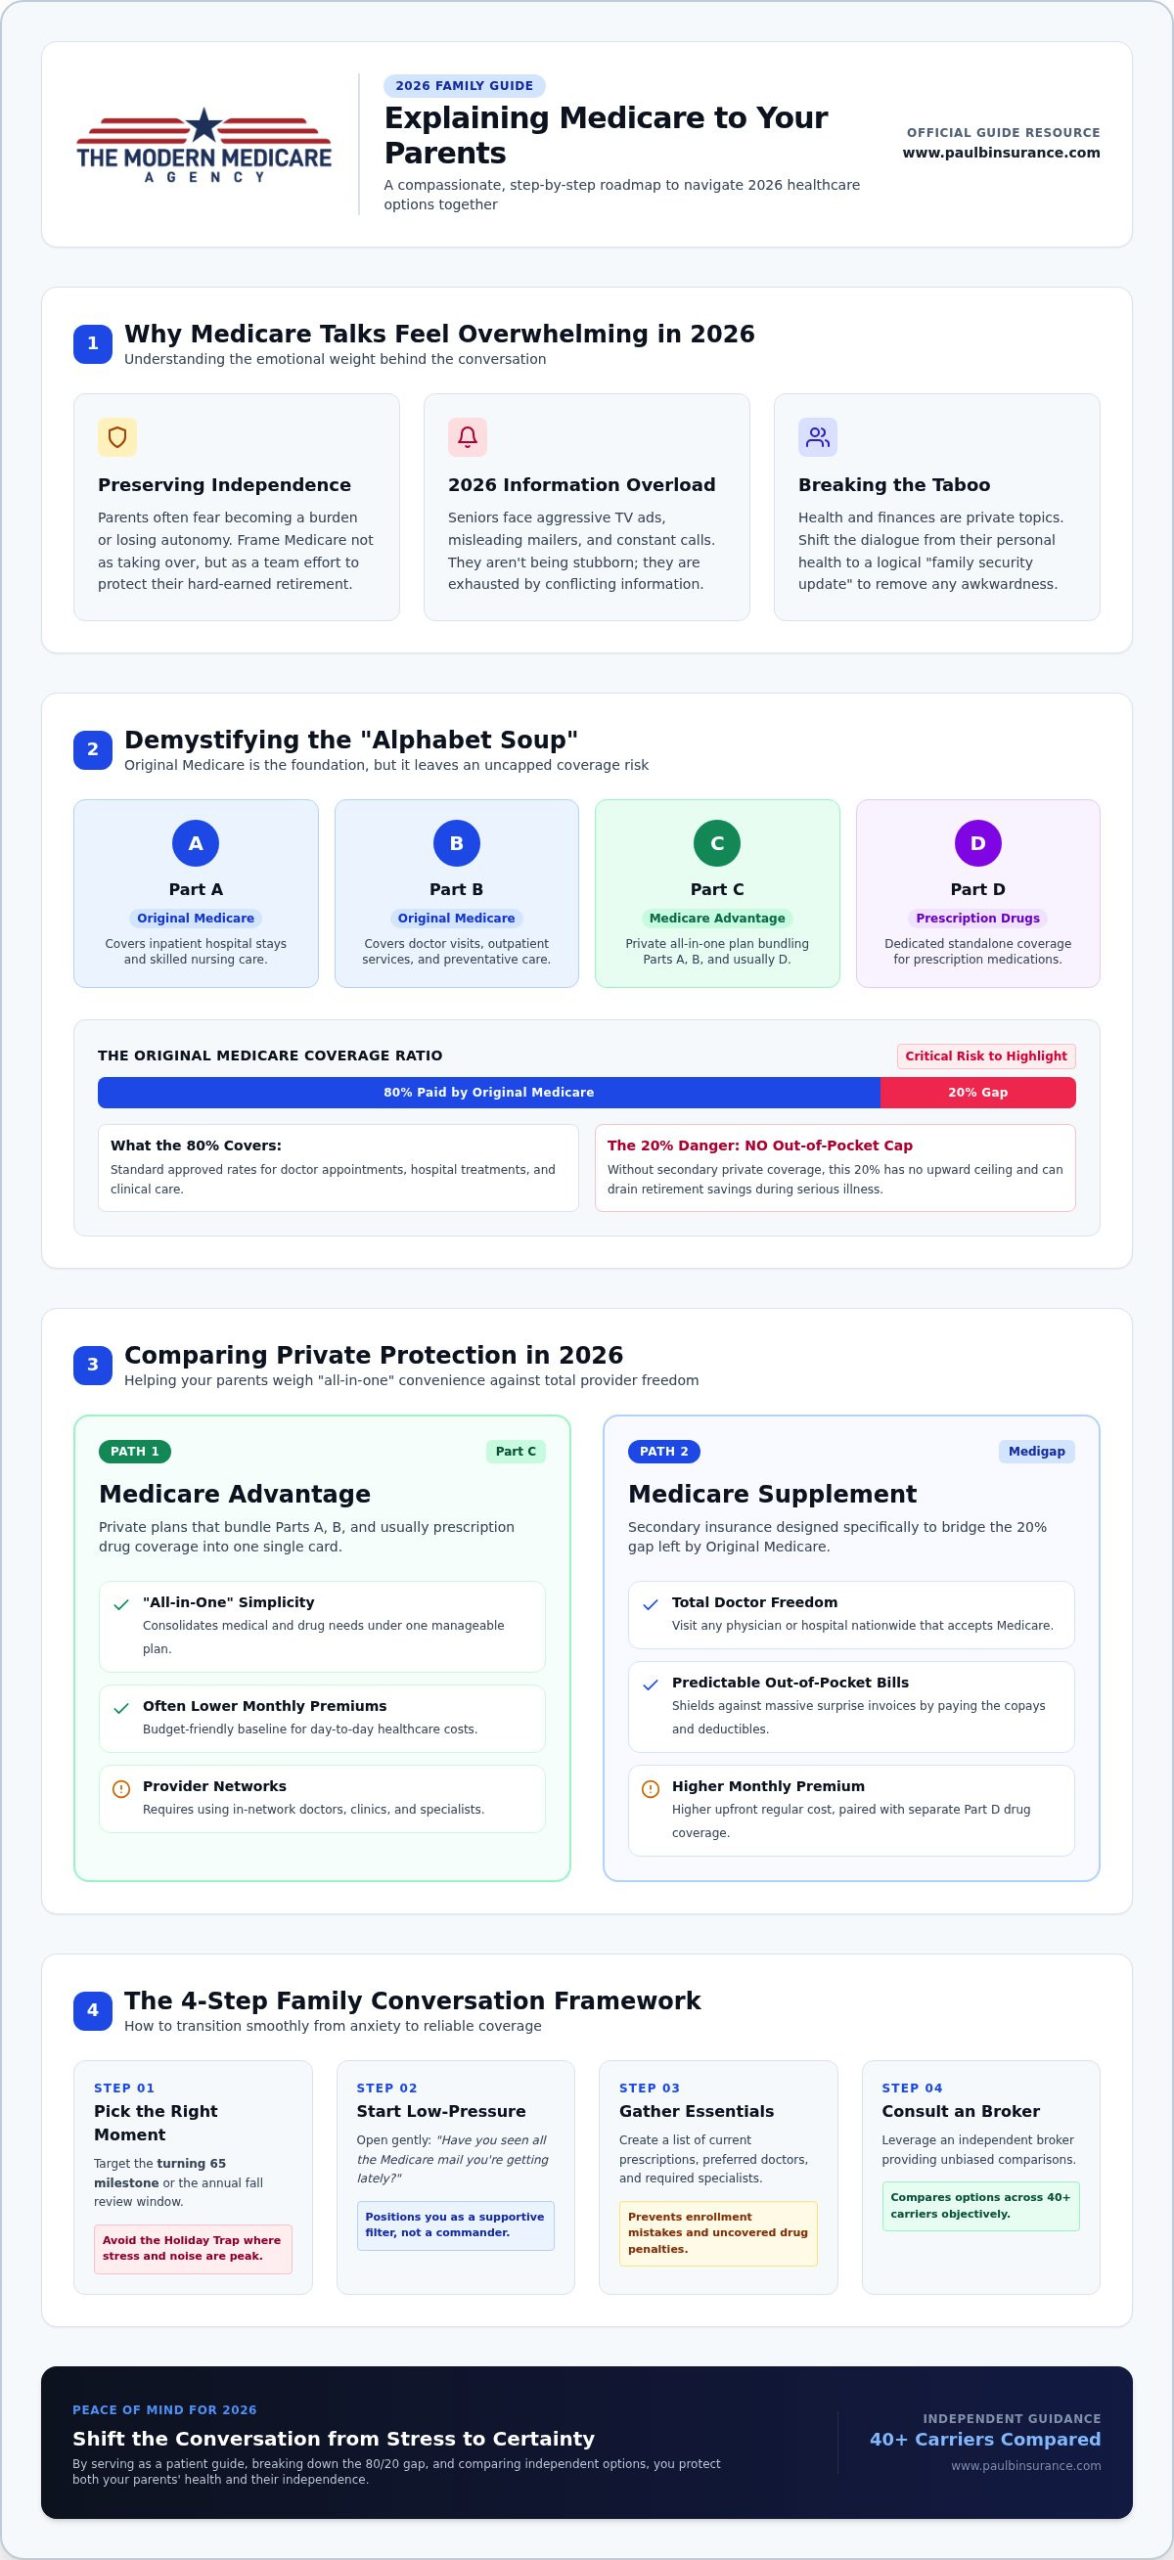
In 2026, this task is harder than ever. Your parents are likely bombarded with aggressive TV ads, confusing mailers, and constant phone calls. This “Information Overload” makes them want to shut down or ignore the topic entirely. It’s helpful to realize that they aren’t being difficult; they’re simply overwhelmed by a system that feels designed to confuse them. Your goal is to be a calm, patient guide. You aren’t taking over their lives. Instead, you’re helping them secure their freedom by ensuring a medical bill doesn’t wipe out their savings. If they feel like you’re on their team, they’ll be much more likely to listen to your advice on options like a Medicare Advantage plan.
Breaking the ‘Insurance Taboo’
Many parents view their health and finances as private matters. They might keep a new diagnosis or a rising prescription cost quiet to avoid worrying you. However, with 2026’s rising healthcare costs, staying silent can be risky for those on a fixed retirement income. To help them open up, try framing the conversation as a family security update. This moves the focus away from their personal health and toward a logical review of the Medicare program overview and how it fits into their long-term plan. When you treat the discussion as a collaborative project, you remove the stigma of “needing help” and replace it with the confidence of “being prepared.”
Identifying the Best Time to Talk
Timing is everything. The Medicare Milestone of turning 65 is the most natural opening. If they’re already enrolled, the annual fall review is another great window. Avoid the Holiday Trap where emotions are high and the house is full of people. These talks require focus and privacy. A simple way to start is by asking, “Have you seen all the Medicare mail you’re getting lately?” This acknowledges the external noise and positions you as an ally who can help filter it. When you understand how to explain medicare to my parents in a way that respects their boundaries, the process becomes much smoother. It’s a low-pressure way to begin the journey from confusion to clarity together.
Medicare Basics: The Simple ‘Alphabet Soup’ Explanation
When you sit down to figure out how to explain medicare to my parents, it’s best to start with the basics. Medicare is simply the federal health insurance program for people 65 or older, though it also covers some younger people with disabilities. Think of it as a four-part system, often called “alphabet soup,” but we only need to focus on a few letters to start. Keeping it simple helps remove the initial wall of confusion that many seniors feel when they see those thick booklets in the mail.
Part A and Part B are known as Original Medicare. Part A covers hospital stays, while Part B handles your doctor visits and outpatient care. While this sounds comprehensive, it’s just the foundation. Original Medicare usually only pays about 80% of medical costs. That remaining 20% is “the gap,” and it has no upward limit. This is the part that causes the most anxiety for families. Without extra coverage, a single major surgery or a chronic illness could put your parents’ retirement savings at risk. A key part of how to explain medicare to my parents is showing them that the government card is a great start, but it doesn’t provide a ceiling on their potential out-of-pocket costs.
Original Medicare vs. Private Options
A helpful way to describe this is through a house analogy. Original Medicare is the solid concrete foundation. It’s necessary, but you wouldn’t want to live there without a roof or walls to protect you from a storm. Private insurance plans act as that protective structure. When comparing Original Medicare and Medicare Advantage, you’ll see that these private options often bundle coverage together to make things easier. You can learn more about these starting points in our guide, What Is Medicare? A Simple Guide for Beginners.
What Part D Looks Like in 2026
Part D is the piece that covers prescription drugs. In 2026, there’s a major improvement that will give your parents a lot of peace of mind. For the first time, there’s a $2,000 out-of-pocket cap on covered prescriptions. This means once your parents spend $2,000 on their meds, they won’t pay another dime for the rest of the year. It’s a massive win for anyone on expensive maintenance medications. You should sit down with them and make a list of their current prescriptions to see how this cap changes their monthly budget. To see how this fits into their specific plan, you can read Medicare Part D Explained. If you’re worried about specific drug costs, we can help you review a Medicare Part D plan that fits their needs perfectly.
Advantage vs. Supplement: Helping Your Parents Choose
Once you’ve covered the basics, the next hurdle in how to explain medicare to my parents is helping them choose between two very different paths. While Original Medicare provides the foundation, most seniors choose to add private coverage to protect their savings. This choice usually falls into two categories: Medicare Advantage or a Medicare Supplement plan. Neither is “better” in a vacuum. The right choice depends entirely on your parents’ health needs, their monthly budget, and how much they value flexibility.
Think of this as choosing between a bundled vacation package and an a la carte trip. One offers convenience and extra perks for a lower upfront cost. The other requires a higher monthly payment but gives you total control over where you go and who you see. If you find the comparison overwhelming, you can look into the State Health Insurance Assistance Program (SHIP) for additional community resources. However, understanding the core differences yourself is the best way to lead a calm family discussion.
The Pros and Cons of Medicare Advantage
Medicare Advantage (Part C) is the “all-in-one” approach. These plans are popular because they often have very low monthly premiums. In 2026, many of these plans continue to offer attractive “extras” that Original Medicare doesn’t cover, such as dental, vision, and even grocery allowances or gym memberships. It’s a simple way for parents to get everything they need in one single plan.
The trade-off is the network. Your parents must generally use specific doctors and hospitals within the plan’s service area. If their favorite specialist isn’t in that network, they might have to pay the full cost out of pocket or find a new doctor. You can explore these options further in our Medicare Advantage Guide to see if a bundled plan fits their lifestyle.
Why Some Parents Prefer Medigap
Medicare Supplement plans, also known as Medigap, are for parents who prioritize freedom and predictability. With Medigap, your parents can see any doctor in the United States that accepts Medicare. There are no networks to worry about. This is a huge benefit if they travel frequently or spend part of the year in a different state.
While the monthly premiums are higher than Advantage plans, the out-of-pocket costs are very stable. After the premium is paid, there are often few or no co-pays for covered services. This removes the “sticker shock” of a surprise medical bill. To see if this level of security is right for your family, read our article on What Is Medicare Supplement Insurance?. When you’re learning how to explain medicare to my parents, framing Medigap as the “no-surprises” option often helps them feel more secure about their financial future.
A Step-by-Step Framework for the Medicare Conversation
Navigating the logistics of a health plan is one thing; managing the family dynamic is another. When you are figuring out how to explain medicare to my parents, it helps to have a methodical process. This keeps the focus on facts and security rather than emotions or power struggles. By following a structured framework, you can move from a state of uncertainty to a clear, actionable plan that protects your parents’ health and their retirement savings.
The first step is simply gathering the right documents. Ask your parents if you can see their “red, white, and blue” Medicare card and any current private insurance cards they use. This isn’t about prying; it’s about seeing exactly what they have so you don’t make assumptions. Once you have the paperwork, move to step two: reviewing their current health needs. Make a list of the doctors they love and the specific medications they take every day. This list is the most important tool you have. It will dictate whether a plan is a perfect fit or a costly mistake.
Step three involves checking their eligibility dates. Missing the Initial Enrollment Period can lead to lifelong late-enrollment penalties, so timing is critical. Finally, step four is often the most helpful: use a neutral third party. Sometimes, a parent might be hesitant to take advice from their child but will gladly listen to an independent expert. Bringing in a professional can take the pressure off the family dynamic and ensure the conversation stays productive. If you want a partner to help you compare options from over 40 carriers, our team is here to guide you.
Questions to Ask Your Parents
To keep the talk focused on their needs, try asking open-ended questions that encourage them to share their concerns. You might ask:
- “Are you happy with your current doctors, or have you had trouble getting appointments lately?”
- “Are you worried about the cost of your prescriptions this year, especially with the new 2026 changes?”
- “Do you feel like you’re paying too much for dental or vision care out of pocket?”
These questions help you identify gaps in their current coverage without making them feel defensive. It turns the process into a collaborative search for better value.
Avoiding Common Pitfalls
One of the biggest mistakes is trying to lecture your parents. Remember, Medicare is their choice; you are simply the researcher and advocate. It’s also vital that you don’t rush the process. Medicare decisions are too big for a single 15-minute chat. Give them time to process the information you’ve found. If they feel pushed, they may stop listening. You can find more details on the different paths available in our Medicare Advantage guide to help them see the variety of options they have. When you approach how to explain medicare to my parents as a patient, ongoing journey, you’ll find they are much more open to your help.
Why an Independent Broker is Your Family’s Secret Weapon
Once you’ve had the initial talk and gathered the lists of doctors and meds, you might feel like you’re standing at the base of a mountain. This is the moment when many families realize that knowing how to explain medicare to my parents is only half the battle. The other half is actually shopping the market. This is where an independent broker becomes your most valuable ally. Unlike a “captive” agent who works for a single insurance company, an independent broker works for you. They have the ability to compare plans from over 40 different carriers at once.
Think of it this way: a company agent is like a car salesman at a specific dealership. He’s only going to tell you why his brand is the best. An independent broker is like a personal shopper who looks at every option on the market to find the one that fits your parents’ specific needs. Because they aren’t restricted to one brand, they can provide an unbiased comparison. They can see which company offers the best price for your father’s specific heart medication or which plan includes your mother’s favorite specialist. This removes the guesswork and the high-pressure sales tactics that often make seniors feel defensive.
One of the best parts of this service is that it’s provided at no cost to your parents. Brokers are compensated by the insurance companies, so you get expert guidance without adding another bill to a fixed retirement income. Additionally, the support doesn’t end when the enrollment form is signed. A dedicated broker provides year-round help. If a claim is ever denied or if a plan changes its terms next year, you have a direct line to someone who knows your family’s history and can advocate for you. It’s a journey from a state of distress to one of total certainty.
Simplifying the Search with The Modern Medicare Agency
At The Modern Medicare Agency, Paul Barrett and his team specialize in handling the “heavy lifting” for families. We understand that you have enough on your plate without becoming an insurance expert overnight. We vet every option to ensure it meets our high standards for reliability and security. Serving clients in over 34 states, we bring local expertise to the table, ensuring your parents get a plan that works where they live. We take pride in being educators first and brokers second, focusing on clarity over jargon.
Next Steps: Starting the Journey Together
The 2026 landscape has brought significant changes to how plans are structured, especially with new limits on prescription costs. Even if your parents have liked their current plan for years, it’s vital to review it this year. A plan that was perfect in 2025 might not be the best value today. As you continue learning how to explain medicare to my parents, remember that you don’t have to do it alone. You can read more about what to look for in our Medicare Broker: Your Complete Guide. When you’re ready, booking a free consultation is the best way to move forward with confidence and peace of mind.
Securing Your Parents’ Future Together
Navigating the 2026 Medicare landscape doesn’t have to be a source of family tension. By focusing on the simple “alphabet soup” basics and understanding the new $2,000 out-of-pocket cap for prescriptions, you can turn a confusing process into a clear path forward. Learning how to explain medicare to my parents is truly about acting as their advocate, ensuring they keep their favorite doctors while protecting their hard-earned retirement savings from unexpected costs.
You don’t have to carry this burden alone. As independent brokers, we provide unbiased comparisons from over 40 carriers across 34 states. We handle the heavy lifting so you can focus on being a supportive child rather than an insurance researcher. Our services are provided at zero cost to your family, giving you professional expertise without the financial pressure. Let us help you protect your parents: schedule a free, unbiased Medicare review today. You’ve done the hard work of starting the conversation; now let’s work together to find the peace of mind your family deserves.
Frequently Asked Questions
When is the best time to start explaining Medicare to my parents?
The best time to begin is roughly six to nine months before your parents turn 65. This window allows you to research options without the stress of an immediate deadline. Starting early helps you figure out how to explain medicare to my parents in small, manageable pieces rather than one overwhelming lecture. It also ensures you have plenty of time to gather their medication lists and doctor preferences before the Initial Enrollment Period begins.
Can I sign my parents up for Medicare myself?
Legally, your parents must be the ones to enroll unless you have a formal Power of Attorney. However, you can play a vital role as their primary researcher and advocate. You can gather plan comparisons, check doctor networks, and sit in on calls with a broker. Your support helps them make an informed choice while they still maintain the final authority over their own healthcare decisions.
What happens if my parents miss their Medicare enrollment deadline in 2026?
Missing the 2026 enrollment deadline can lead to lifelong financial consequences. The government may apply late enrollment penalties that are added to their monthly Part B or Part D premiums forever. Additionally, they might have to wait for the next General Enrollment Period to sign up, which could leave them without any health coverage for several months. Timely enrollment is the best way to protect their health and their savings.
Is Medicare Advantage better than Medigap for seniors on a budget?
Advantage plans often appeal to those on a budget because they typically feature lower monthly premiums. Some even have a $0 premium. In contrast, Medigap plans have a higher monthly cost but offer more predictable billing with fewer surprise co-pays. When you’re deciding how to explain medicare to my parents, it’s helpful to ask if they prefer a lower monthly bill or the certainty of knowing exactly what a surgery will cost.
Does Medicare cover dental and vision for my parents?
Original Medicare does not provide coverage for routine dental cleanings, extractions, or eye exams. If your parents need this care, you should look into Medicare Advantage plans, which often bundle these benefits into the package. Another option is purchasing a standalone dental or vision policy. We can help you compare these supplemental options to ensure your parents’ teeth and eyes are protected as they age.
How much does it cost to use a Medicare broker?
Using an independent broker is completely free for seniors and their families. Brokers are compensated by the insurance carriers, so you don’t pay anything for their expert advice or plan comparisons. This allows you to access a professional who can compare over 40 different carriers without adding any extra strain to your parents’ retirement budget. You get all the expertise and year-round support at no out-of-pocket cost.
What is the $2,000 out-of-pocket cap I keep hearing about for 2026?
The $2,000 cap is a major change for Part D prescription drug plans in 2026. This limit means that once your parents spend $2,000 on their covered medications, they won’t have to pay anything else for their drugs for the remainder of the calendar year. It provides a massive amount of financial security for families who were previously worried about high out-of-pocket costs for chronic health conditions as they learn how to explain medicare to my parents.
How do I help my parents if they live in a different state?
You can easily assist your parents from a distance by working with a broker licensed in their specific state. The Modern Medicare Agency provides services in more than 34 states, allowing us to review local networks and plan availability regardless of where you live. We often facilitate three-way calls so you can hear the same information as your parents and help them make a confident decision from afar.
Article by
Paul Barrett
Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.
He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.
📞 631-358-5793 | paulbinsurance.com