
If you’re asking what are the different types of annuities, it helps to know that terms such as “fixed,” “indexed,” and “immediate” can describe different features of a contract. Two annuities may use similar language but handle value and future payments differently.
This 2026 guide explains the main annuity categories, how each determines contract value, and when payments may begin. You’ll also find practical questions to help you compare terms, including how value is calculated, when income may start, and what access or charges the contract describes. Use this information to prepare questions and understand your options. The terms of each contract matter, and your circumstances affect how you evaluate a financial product.
Key Takeaways
- To understand what are the different types of annuities, compare how each contract determines its value rather than relying on labels alone.
- Separate how an annuity’s value is determined from when payments may begin. These are two different features.
- Compare contract terms for interest, market-linked changes, income timing, access, and costs.
- Paul B Insurance is an independent brokerage that offers annuities as well as Medicare guidance.
- Use your priorities and questions to guide a conversation, and treat this guide as general education rather than a personal recommendation.
What Is an Annuity, and What Does It Do?
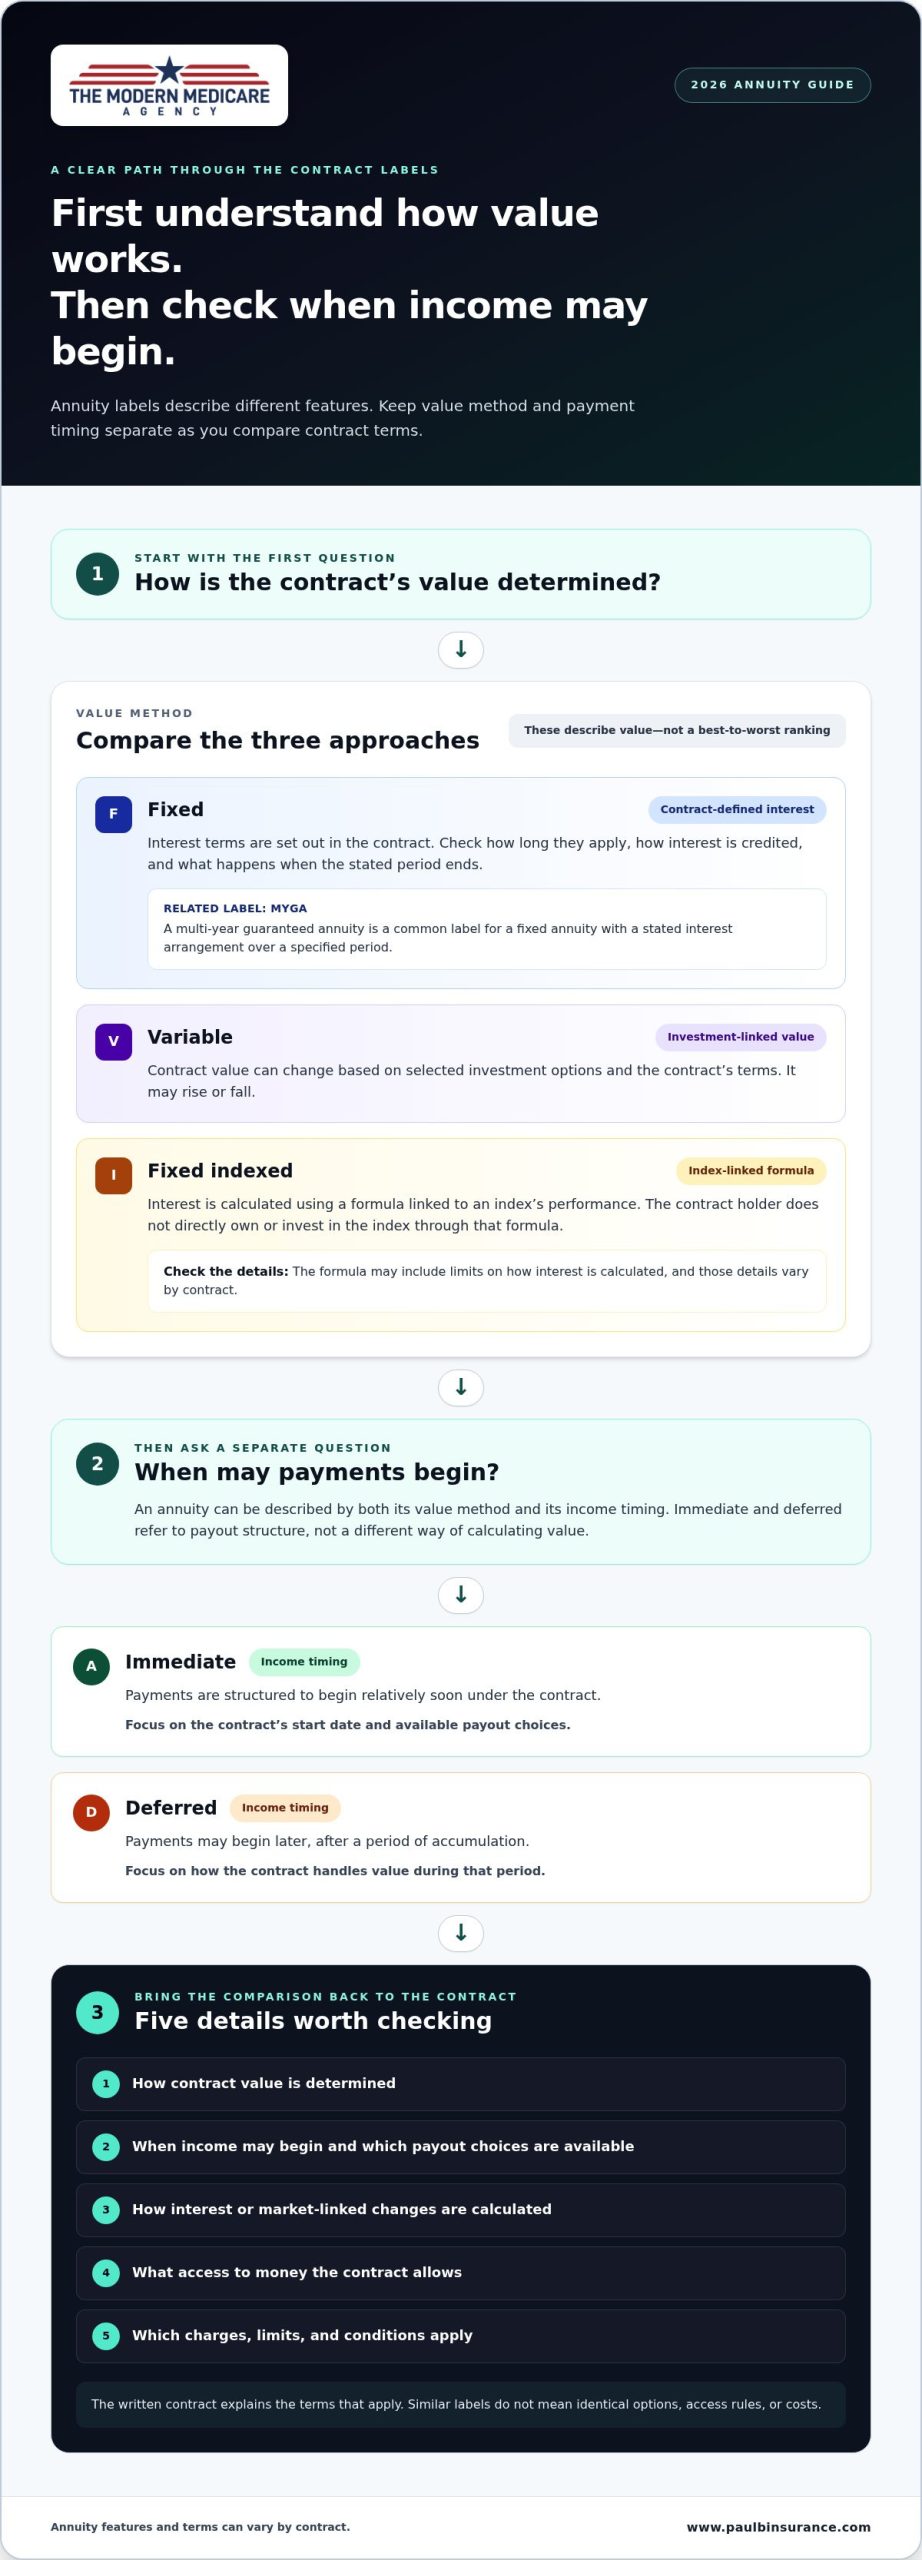
Annuity labels can refer to different parts of a contract, which can make it hard to tell what you’re comparing. Start by separating the contract’s value method from its payment timing. This guide explains those features in plain language without suggesting that one kind is right for everyone.
An annuity is a contract between a purchaser and an insurance company. It sets out how money may be handled and whether payments can be made under specified terms. The contract defines the available options, and annuities can differ in protections, access to money, and income choices. A general annuity overview also describes how contracts can be classified in different ways.
A person may pay into an annuity with a single premium or through payments over time. Depending on the contract, its value may build during an accumulation period, payments may be made later, or both. Some contracts offer an income option, but not every annuity provides income for life. Review the contract rather than assuming a particular payment or return.
How an annuity contract generally works
The purchaser pays a premium to the insurer. During an accumulation period, the contract may build value according to its stated terms. Later, the purchaser may have payout options if the contract provides them. The contract explains when income can begin, what access to funds is allowed, and which choices are available. These details matter more than the label alone.
An annuity is an insurance contract that defines how money may accumulate or be paid out under the terms agreed with the insurer.
Why annuity labels can overlap
Labels often describe different dimensions of a contract rather than separate, competing products. One label may explain how value is determined, while another describes when payments may begin. An annuity can therefore be discussed by both its growth method and its income timing. Keeping those features separate makes it easier to understand what are the different types of annuities.
As you read on, keep two questions in view: How is the contract’s value determined, and when might income begin? The answers help organize the main types and make comparisons easier. Your goals, resources, and circumstances can affect how you evaluate a contract, so use this guide to build understanding and prepare informed questions.
The Main Annuity Types: Fixed, Variable, and Indexed
Once you understand that annuity labels describe different parts of a contract, look at how its value may be determined. The three common growth approaches are fixed, variable, and fixed indexed. Each uses different contract terms, so the name alone won’t tell you everything about access, potential changes, or costs.
In simple terms, fixed annuities use contract-defined interest terms, variable annuities can rise or fall with selected investments, and fixed indexed annuities calculate interest using an index-linked formula. These are broad descriptions, not promises about a particular contract. Investor.gov’s guide to annuities also outlines these categories and related annuity terms.
Fixed and multi-year guaranteed annuities
A fixed annuity uses interest terms set out in its contract. A multi-year guaranteed annuity, often shortened to MYGA, is a common label for a fixed annuity with a stated interest arrangement over a specified period. The contract explains how interest is credited and what happens when that period ends. Read those terms closely, because the label doesn’t describe every condition or option.
When comparing fixed contracts, check how long the stated interest terms apply and what the contract says about later changes. Similar labels don’t mean identical terms. The written contract is the source for the details that apply.
Variable and fixed indexed annuities
With a variable annuity, contract value can change based on selected investment options and the contract’s terms. The value may rise or fall. A fixed indexed annuity works differently: its interest credit is calculated using a formula linked to an index’s performance. The contract holder does not directly own or invest in the index through that formula.
Index-linked formulas can include limits on how interest is calculated, and the details vary by contract. Fees, access rules, and risks also depend on the specific terms. Don’t judge an annuity by a single feature or illustration. Check how its value is determined, what conditions apply, and what charges or limits the contract describes.
So, what are the different types of annuities in practical terms? Fixed, variable, and fixed indexed annuities describe ways value may be determined, not a ranking from best to worst. A fixed contract’s stated interest terms may be easier to follow, while a variable contract’s value can move with its chosen investment options. An indexed formula uses another method, but its calculation and limits are contract-specific.
As you compare options in 2026, focus on the contract wording rather than assuming a category guarantees a particular outcome. Start with the feature you want to understand, then review the terms that apply. You can explore annuity options with Paul B Insurance.
Immediate vs. Deferred Annuities: When Can Income Begin?
Annuities can be grouped by how their value is determined and by when payments may begin. These are separate features. A fixed, variable, or indexed annuity may also be described as immediate or deferred, depending on its payout structure. This distinction helps you understand whether the contract is designed to start payments relatively soon or leave time before an income phase begins.
| Timing type | When payments may begin | What to focus on |
|---|---|---|
| Immediate | Payments are structured to begin relatively soon under the contract. | The contract’s start date and available payout choices. |
| Deferred | Payments may begin at a later point, after a period of accumulation. | How the contract handles value during that period and when income options become available. |
What immediate annuity means
An immediate annuity is arranged to begin payments relatively soon after the contract is set up. “Immediate” describes a timing category, not a universal schedule. The actual start date, payment frequency, and payout choices depend on the contract. Review the terms to see when payments can begin and which options are available.
What deferred annuity means
A deferred annuity separates the initial contribution from a possible later income phase. The period before payments begin is often called the accumulation period. During that time, the contract follows its stated terms, but the label alone doesn’t promise growth or a particular result. Deferred contracts can use different value methods, including fixed, variable, or index-linked approaches.
“Deferred” doesn’t tell you how contract value is determined, just as “fixed” or “indexed” doesn’t tell you when payments may begin. To understand what are the different types of annuities, consider timing and value method as two separate questions. One describes the possible income schedule; the other describes how the contract’s value may be calculated.
Before comparing contracts, look for the details that connect timing to your needs:
- Start date: What does the contract say about when payments may begin?
- Payment choices: What payout options are written into the contract, and what terms apply to each?
- Access before payments: What does the contract say about accessing money during any waiting or accumulation period?
- Value method: Is the contract fixed, variable, or indexed while you wait?
These questions keep the comparison grounded in contract language rather than broad labels. In 2026, separate the timing feature from the value method before drawing conclusions. A clear summary of both can help you compare options and identify contract details to review more closely. No general category establishes the payment amount, duration, or start date for a particular contract.
How to Compare Annuity Types for Your Priorities
There isn’t one annuity type that fits everyone. A useful comparison starts with your priorities and the terms of the contracts you’re considering. Contract terms, not category names alone, determine important differences in access, costs, and payout choices.
As you work out what are the different types of annuities, use these questions to focus on how each contract works for your needs, rather than treating the labels as a ranking.
Questions to clarify before comparing
- When might you need access to the money? Consider whether you may need funds before payments begin or while the contract is in force. Look for access restrictions and the conditions that apply to withdrawals.
- How do you feel about changes in contract value? A fixed annuity uses contract-defined interest terms, while a variable annuity’s value can change with selected investment options. An indexed contract uses a formula tied to an index. Consider what kind of variation you’re comfortable with, and read how the contract describes its limits and risks.
- When might you want income to begin? If timing matters, compare the contract’s stated start options and payout choices. You may want to understand options that begin sooner or a later income phase.
- What do you want the contract to do? Separate your income goals from your preferences about how value is determined. Growth approach and payout options are different features, so review both rather than assuming one tells you everything.
Understand access, costs, and tax treatment
Read the contract and its relevant disclosure documents. Look for surrender conditions, which explain what may apply if you withdraw money or end the contract under specified circumstances. Compare listed fees and charges, rules for accessing funds, and available payout choices. These details can differ by contract, so don’t assume a particular feature or cost applies to every annuity.
Tax treatment can depend on your circumstances and how the annuity is funded. For 2026, don’t rely on a general description as a personal tax answer. Review current, authoritative tax guidance before making a decision, especially if you’re considering how a contract may fit with other savings or income.
A simple side-by-side note can help you compare each option: how value is determined, when payments may begin, what access conditions apply, which costs are disclosed, and what payout choices are available. Mark unfamiliar terms for clarification before deciding. This makes a complex comparison easier to manage.
If you’d like to discuss annuities, connect with Paul B Insurance. This information is educational and isn’t an individualized financial plan or recommendation.
Where Paul B Insurance Fits Into an Annuity Conversation
Learning about annuities can help you ask clearer questions, without requiring you to make a decision right away. In 2026, take time to understand the contract terms and consider how they relate to your goals. Paul B Insurance, operating as The Modern Medicare Agency, is an independent insurance brokerage that offers annuities as well as Medicare guidance.
What an independent insurance brokerage means here
A brokerage and an insurance company have different roles. The insurer issues an annuity contract and is responsible for its terms. Paul B Insurance, operating as The Modern Medicare Agency, is an independent brokerage, not the insurer that issues the contract. Its primary work is Medicare guidance, and it also offers annuities. Keep those roles distinct when considering a contract.
Information about Medicare guidance isn’t the same as an individualized annuity recommendation or a financial plan. An insurance brokerage does not change which insurer issues a contract or the terms that govern it. Understanding what are the different types of annuities is a useful starting point, but it can’t determine which contract fits your circumstances.
A calm next step for readers exploring annuities
You don’t need to arrive at a conversation with every answer. A few notes can help you explain what you want to understand and keep the discussion focused. Consider writing down:
- Your goals: What role, if any, are you considering for an annuity in your broader financial picture?
- Your timing preferences: Are you thinking about income soon, or exploring a contract with a later income phase?
- Your questions: Which terms about value, access, fees, or payout choices feel unclear?
These notes can make a conversation more useful without turning it into a commitment. You can discuss Paul B Insurance’s annuity offering through The Modern Medicare Agency and ask questions about the general terms that matter to you. Take the time you need to understand the information. The contract’s stated terms remain central, and no outcome should be assumed from a general explanation.
This guide is educational. It can help you organize your questions, but it isn’t a personalized financial plan or a recommendation based on your circumstances. A conversation can be a straightforward next step toward understanding the offering, with no need to rush a decision.
When you’re ready, start a conversation with Paul B Insurance and The Modern Medicare Agency about annuity options.
Take Your Next Step With Confidence
Understanding what are the different types of annuities gives you a clearer starting point, but there’s no need to rush from learning to deciding. Take time to consider what you want an annuity to do, what questions remain, and which contract details you need to understand before moving forward.
A practical next step is to write down your priorities in your own words. Note what you’re hoping to learn, what feels uncertain, and what would help you feel comfortable reviewing your options. Bring those questions to a conversation and take the time you need to understand the information shared.
Paul B Insurance is an independent insurance brokerage that offers annuities as well as Medicare guidance. Exploring its annuity offering can help you continue the conversation at your own pace. It’s okay to ask questions before making a decision.
Explore annuity options with Paul B Insurance and take your next step with clarity and confidence.
Frequently Asked Questions
What are the main types of annuities?
The main types are fixed, variable, and fixed indexed annuities, which use different methods to determine contract value. “Immediate” and “deferred” describe when payments may begin, so they’re timing labels rather than additional growth methods. To understand what are the different types of annuities, separate those two dimensions. Compare how value is calculated, then whether the contract is structured for payments sooner or later.
What is the difference between a fixed and variable annuity?
A fixed annuity follows interest terms set out in its contract, while a variable annuity’s value can change based on selected investment options and contract terms. If you want to understand how market changes could affect an account, review the variable contract’s investment choices and costs. For a fixed annuity, check how long its stated interest terms apply and what happens afterward.
What is the difference between an immediate and deferred annuity?
An immediate annuity is structured to begin payments relatively soon under its terms; a deferred annuity has a period before a possible later income phase. The exact schedule depends on the contract. If you’re planning around a transition such as leaving work, compare the stated payment start options with when you expect to need income. The category name doesn’t promise a particular start date, payment amount, or duration.
Can you lose money in an annuity?
Yes, depending on the contract and what you mean by “lose.” A variable annuity’s value can fall when its selected investments decline. Fees or charges for accessing money may also affect what you receive. Other annuities have different terms, so don’t assume every contract protects the amount paid in or prevents losses. Review the contract’s provisions on value, charges, and withdrawals to understand the risks that apply to that product.
Are annuity payments taxable in 2026?
They may be taxable, and the treatment depends partly on how the annuity was funded. For an annuity funded with pre-tax money, such as through an IRA or 401(k), withdrawals are generally taxed as ordinary income. With an annuity bought using after-tax money, earnings are generally taxed as ordinary income when withdrawn, while returned contributions may receive different treatment. For your 2026 tax situation, check current IRS guidance or consult a tax professional.
What happens to an annuity when the owner dies?
What happens depends on the contract’s payout terms and any beneficiary designation. Depending on the arrangement, a beneficiary may receive a remaining contract value or another benefit described in the contract. Some payout choices may affect what remains for beneficiaries, so consider this before selecting an option. Review the death-benefit language and keep beneficiary information current. Don’t assume every annuity continues payments to a spouse or heir.
Can you withdraw money from an annuity early?
Possibly, but the contract may limit access or apply surrender charges during a specified period. A withdrawal can also have tax consequences. In 2026, a 10% federal tax penalty generally applies to the taxable portion of a withdrawal before age 59½, in addition to ordinary income tax and any insurer charges. Check the contract’s withdrawal terms and consult current tax guidance before taking money out.
Article by
Paul Barrett
Paul Barrett, CMIP is the founder of The Modern Medicare Agency, an independent Medicare-only brokerage based in Melville, NY. With 18 years of Medicare-exclusive experience, a CMIP designation, and more than 5,000 clients served across 37 states, Paul is one of the most credentialed independent Medicare specialists on Long Island — and one of the most direct.
He represents 40+ carriers with no quotas and no allegiances, which means his recommendations are based entirely on what fits each client's specific situation. He is the author of Medicare Mastery Unlocked and host of the Wise Guys Retirement Talk podcast. His content is grounded in primary sources, real carrier intelligence, and 18 years of watching what happens when people get Medicare right — and when they don't.
📞 631-358-5793 | paulbinsurance.com